Related Experiment Videos
Modified conjugate gradient method for diagonalizing large matrices
1Department of Physics, Wuhan University, Wuhan 430072, People's Republic of China. qljie@whu.edu.cn

Abstract:
We present an iterative method to diagonalize large matrices. The basic idea is the same as the conjugate gradient (CG) method, i.e, minimizing the Rayleigh quotient via its gradient and avoiding reintroducing errors to the directions of previous gradients. Each iteration step is to find lowest eigenvector of the matrix in a subspace spanned by the current trial vector and the corresponding gradient of the Rayleigh quotient, as well as some previous trial vectors. The gradient, together with the previous trial vectors, play a similar role as the conjugate gradient of the original CG algorithm. Our numeric tests indicate that this method converges significantly faster than the original CG method. And the computational cost of one iteration step is about the same as the original CG method. It is suitable for first principle calculations.
Related Concept Videos
 01:30
Gaussian Elimination: Problem Solving
 01:30
Lagrange Multipliers: Problem Solving
 01:24
Fast Decoupled and DC Powerflow
 01:28
Lagrange Multipliers: Two Constraints
 01:29
Implicit Differentiation: Problem Solving
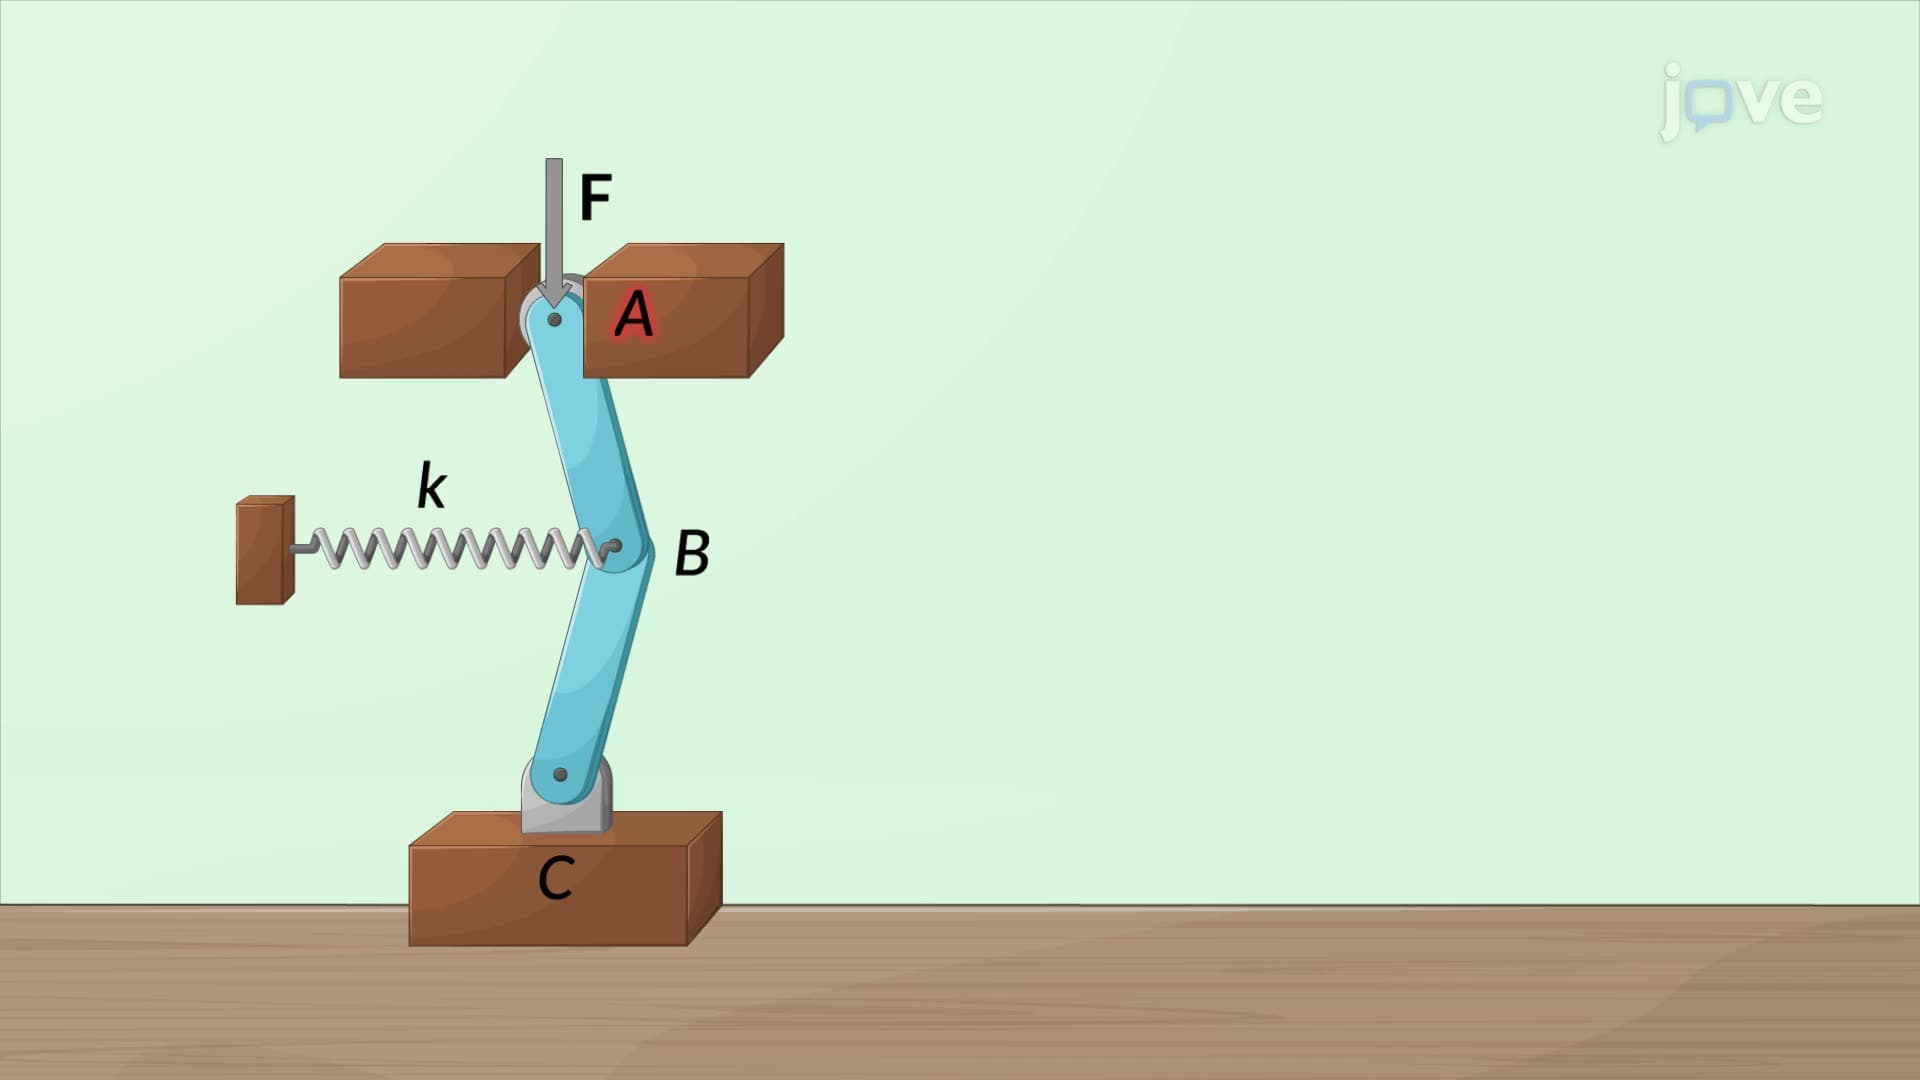 01:23
Euler's Formula to Columns: Problem Solving
The system comprises two vertical rigid bars, AB and BC, of...