First passage time problem for a drifted Ornstein-Uhlenbeck process
Related Experiment Video
Updated: Aug 24, 2026
Visually Based Characterization of the Incipient Particle Motion in Regular Substrates: From Laminar to Turbulent Conditions
Published on: February 22, 2018
1Laboratoire MAP5, Université Paris 5, 75006 Paris, France. madec@vjf.inserm.fr

Abstract:
We consider a continuous stochastic process defined as a drifted Ornstein-Uhlenbeck, for which the first passage time is of interest. The process being non-homogeneous, the first passage time probability density function cannot be found analytically, but numerical methods enable to find its estimate. Estimating the first passage time implies solving an unsteady convection-diffusion equation, with variable coefficients, and we use an implicit Euler scheme to solve it. This work is applied to simulated data, and the continuous process is inspired from recent work on biological marker modelling for HIV-positive patients. The first passage time probability density function can be useful to compare the marker progression in different groups. Numerical results show that the first passage time is highly dependent from the process perturbation, and is then more relevant than methods not considering the stochastic process directly to compare the progression.
Related Concept Videos
 03:33
Genetic Drift
 01:18
Second Order systems II
If ζ...
 01:22
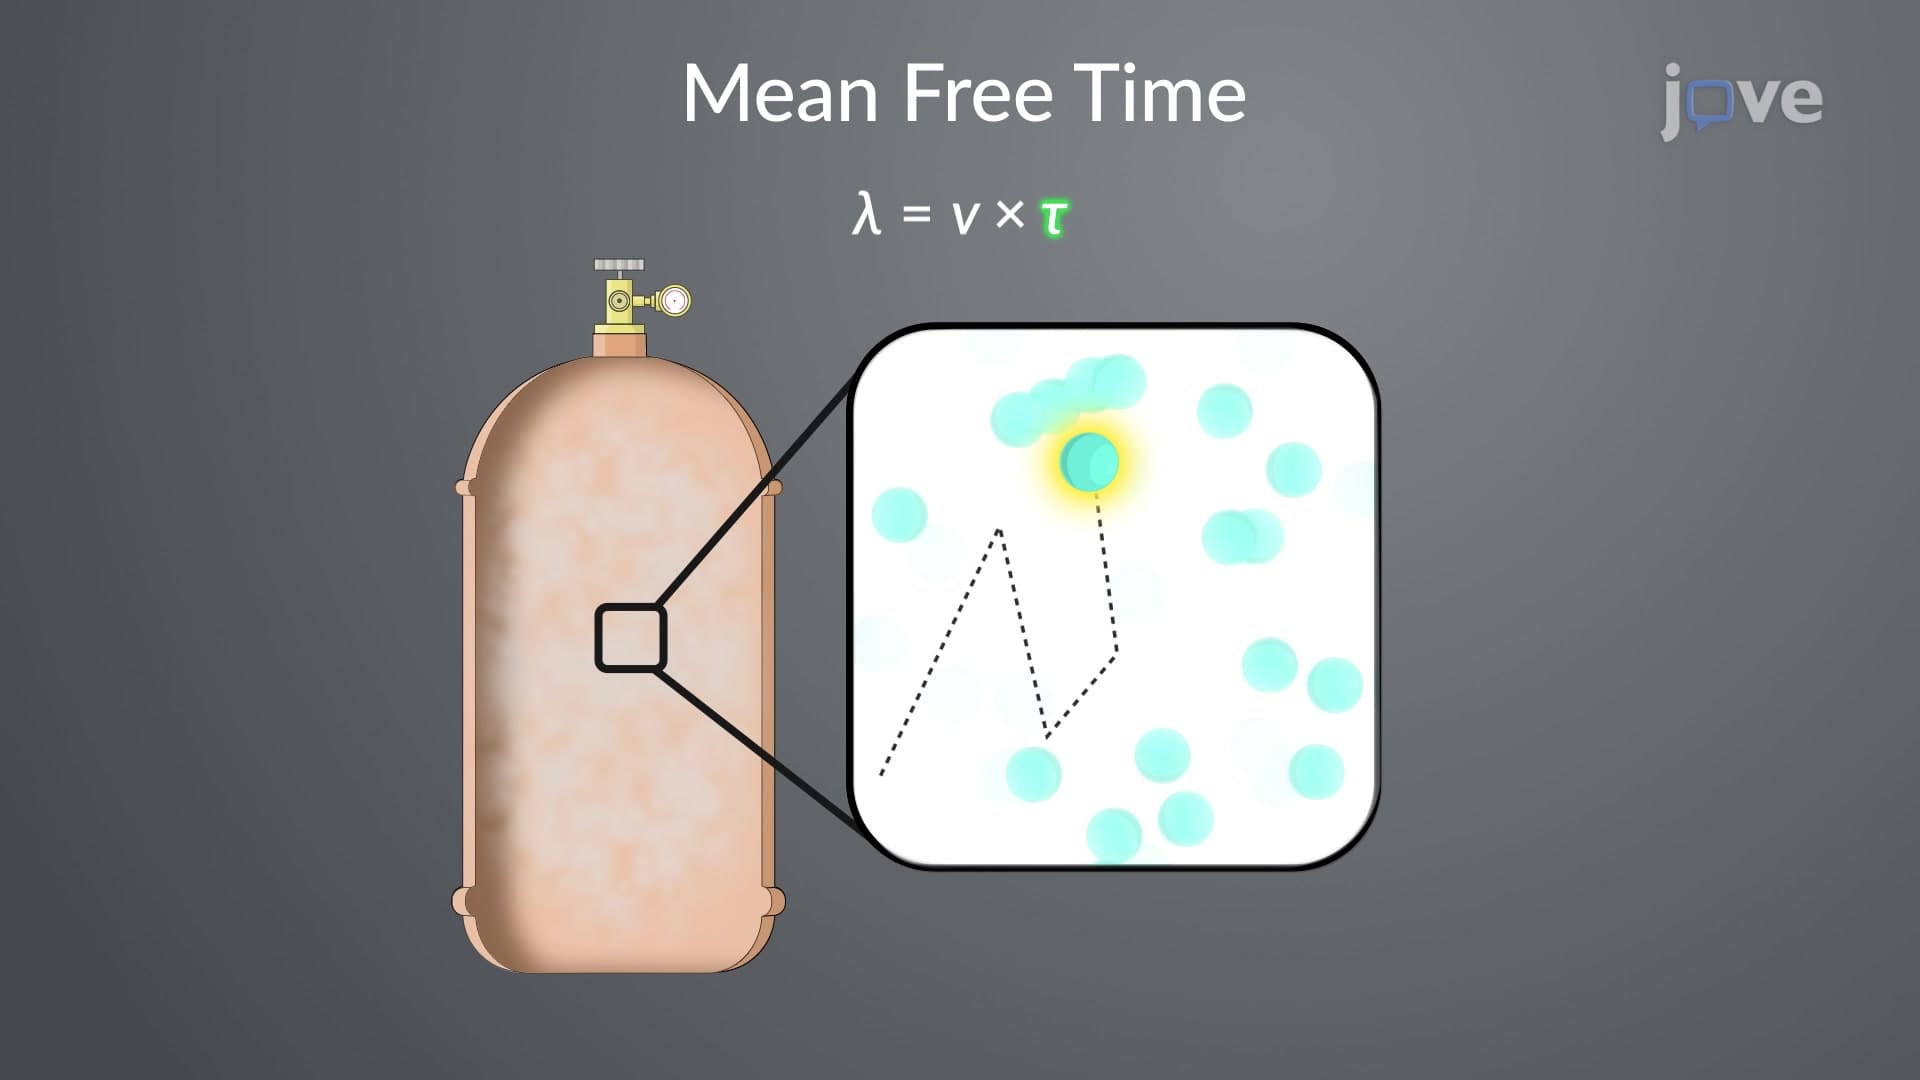
Mean free path and Mean free time
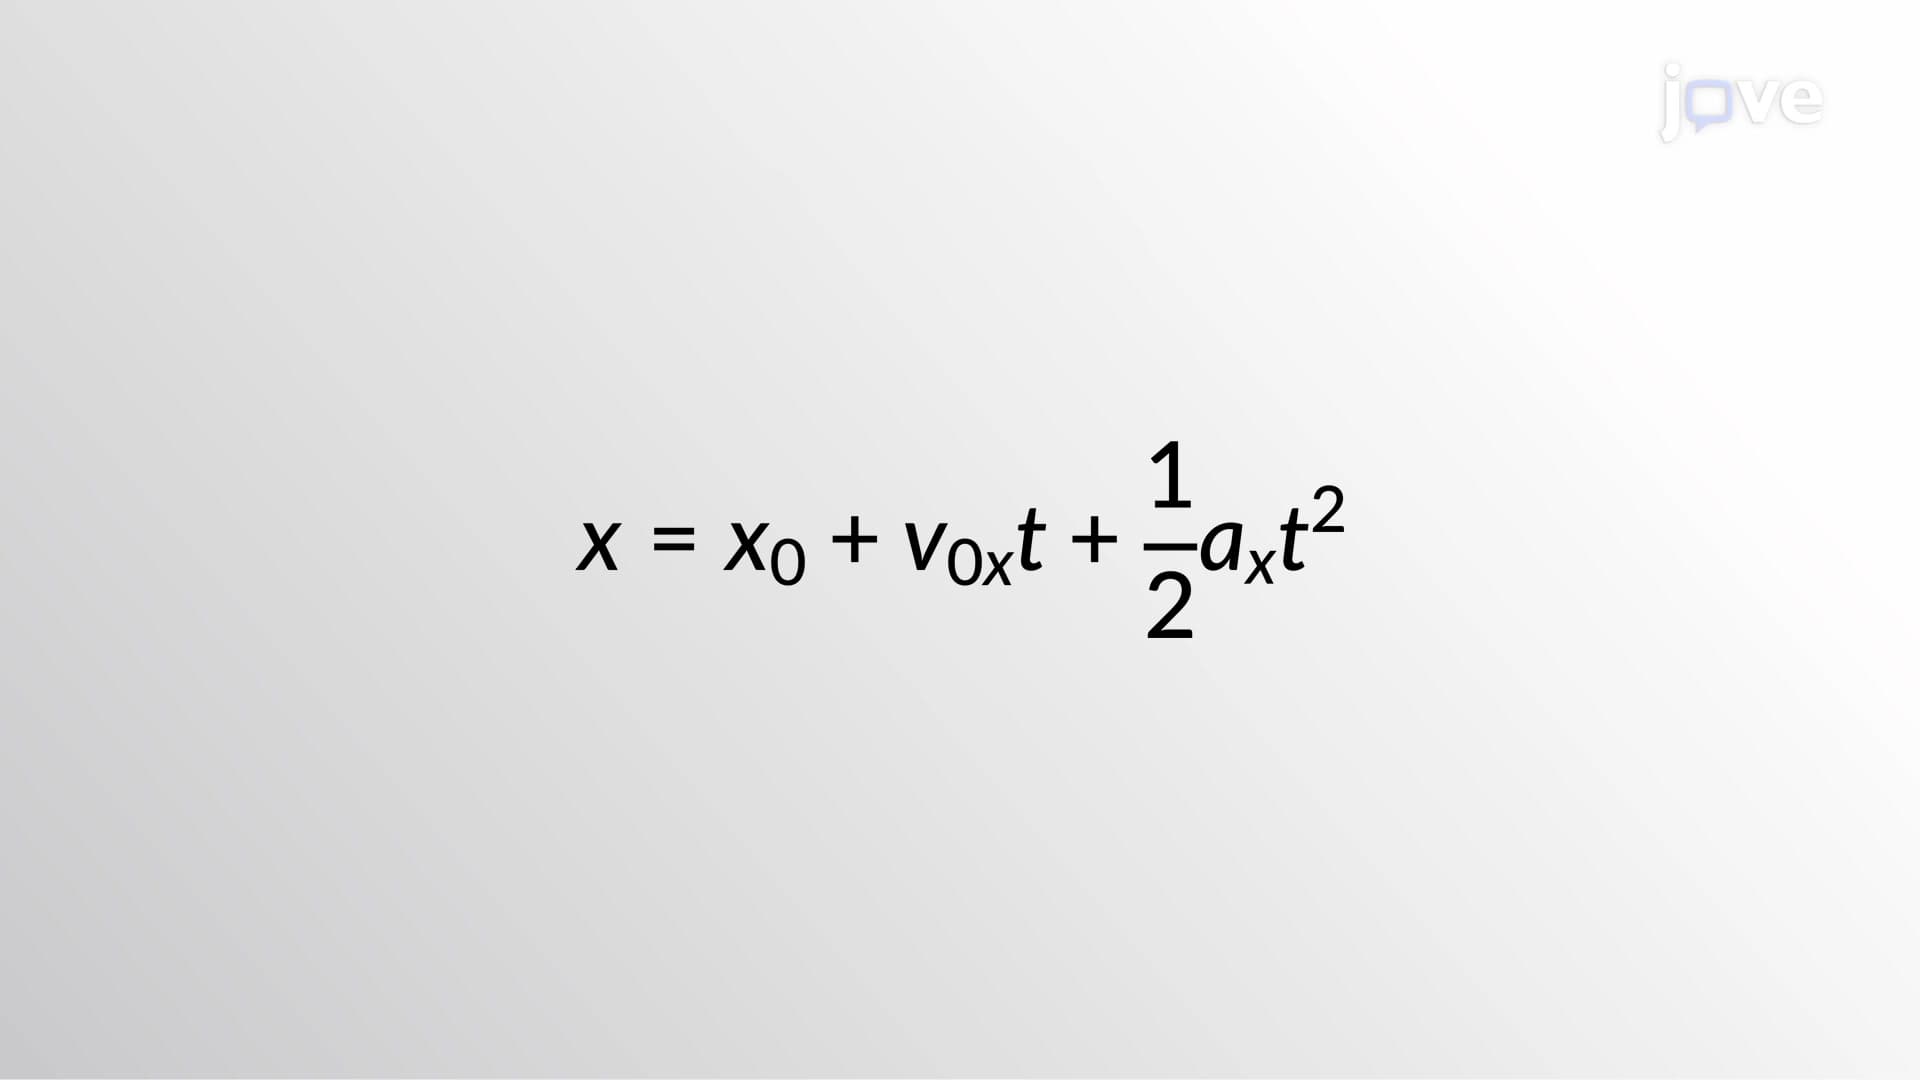 01:17
Kinematic Equations - II
Suppose a car merges into freeway traffic on a 200 m long ramp. If its initial velocity is 10 m/s and it accelerates at 2 m/s2, then the...
 01:21
Partial Differential Equations
 01:26
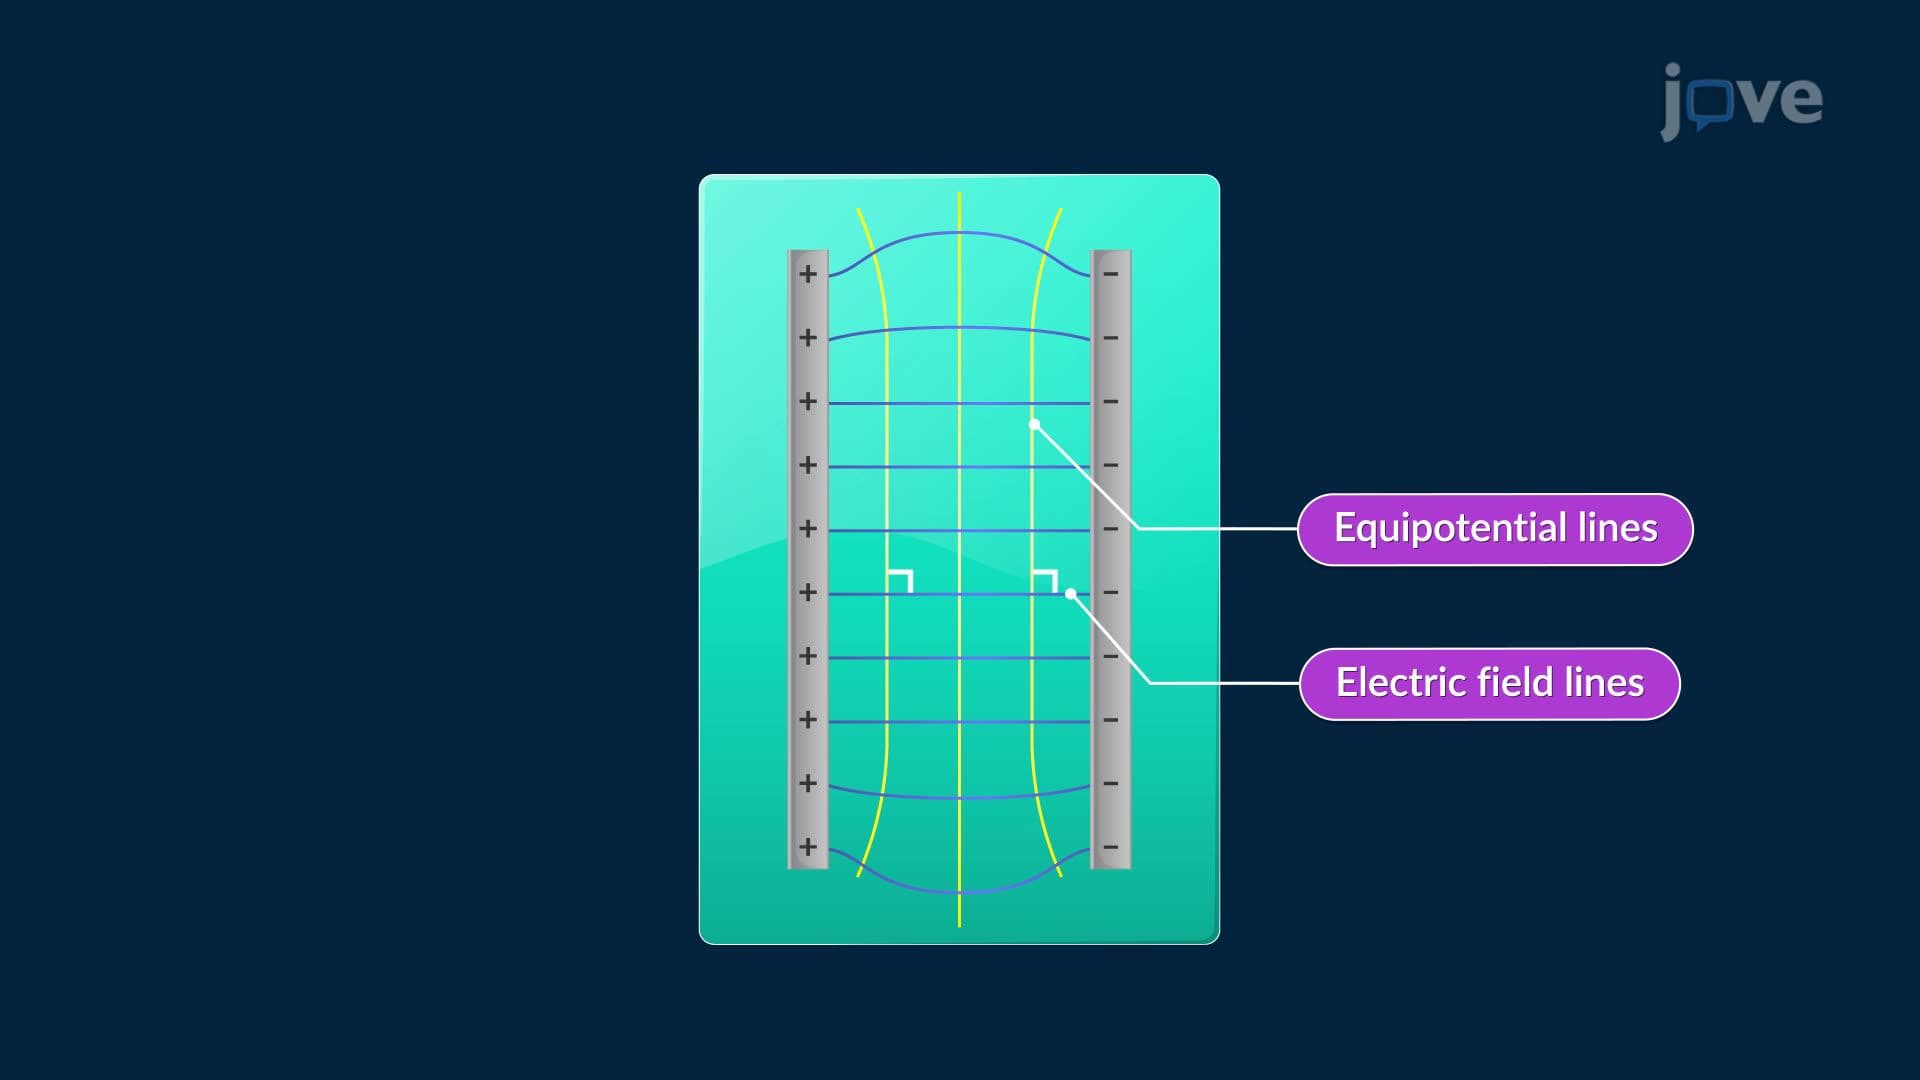
Orthogonal Trajectories