Related Experiment Video
Updated: Aug 17, 2026
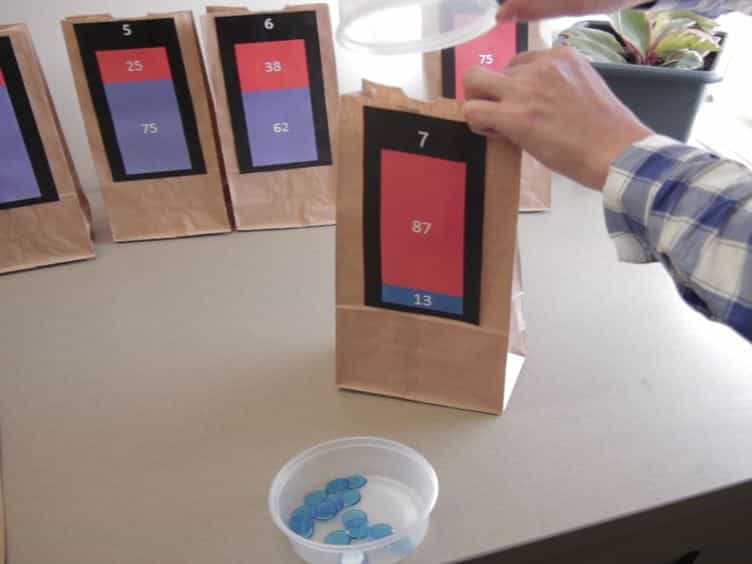

Measuring the Subjective Value of Risky and Ambiguous Options using Experimental Economics and Functional MRI Methods
Published on: September 19, 2012
Communicating asset risk: how name recognition and the format of historic volatility information affect risk
Elke U Weber1, Niklas Siebenmorgen, Martin Weber
1Graduate School of Business, Columbia University, 716 Uris Hall, 3022 Broadway, New York, NY 10027, USA. euw2@columbia.edu

Abstract:
An experiment examined how the type and presentation format of information about investment options affected investors' expectations about asset risk, returns, and volatility and how these expectations related to asset choice. Respondents were provided with the names of 16 domestic and foreign investment options, with 10-year historical return information for these options, or with both. Historical returns were presented either as a bar graph of returns per year or as a continuous density distribution. Provision of asset names allowed for the investigation of the mechanisms underlying the home bias in investment choice and other asset familiarity effects. Respondents provided their expectations of future returns, volatility, and expected risk, and indicated the options they would choose to invest in. Expected returns closely resembled historical expected values. Risk and volatility perceptions both varied significantly as a function of the type and format of information, but in different ways. Expected returns and perceived risk, not predicted volatility, predicted portfolio decisions.
Related Concept Videos
 01:15
Variance
 03:26
Framing Effects
 01:23
Types of Biopharmaceutical Studies: Controlled and Non-Controlled Approaches
Non-controlled studies, commonly employed for initial exploration, lack a control group, rendering them susceptible to biases and external influences. In contrast, controlled...
 01:11
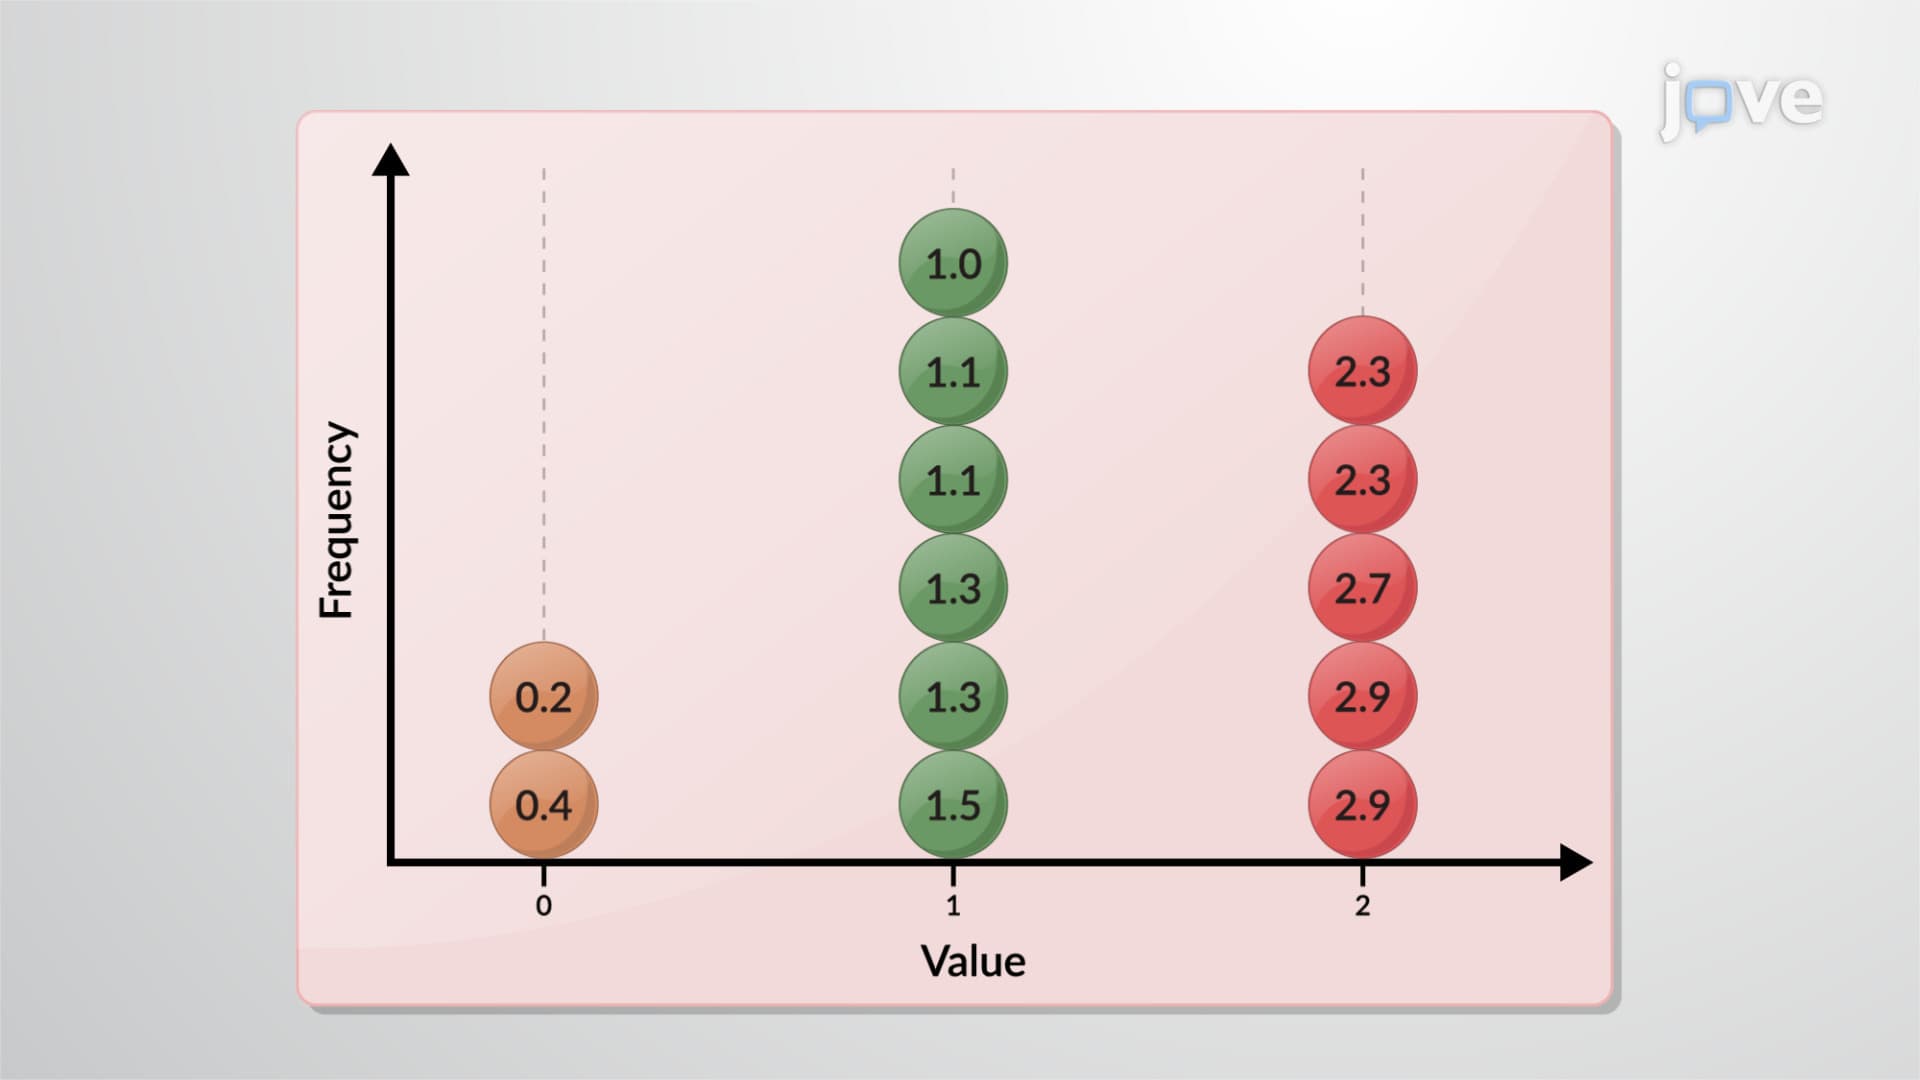
Variability: Analysis
The range is a simple measure of variability, indicating the difference between the highest and...
 01:12
Relative Risk
 01:10
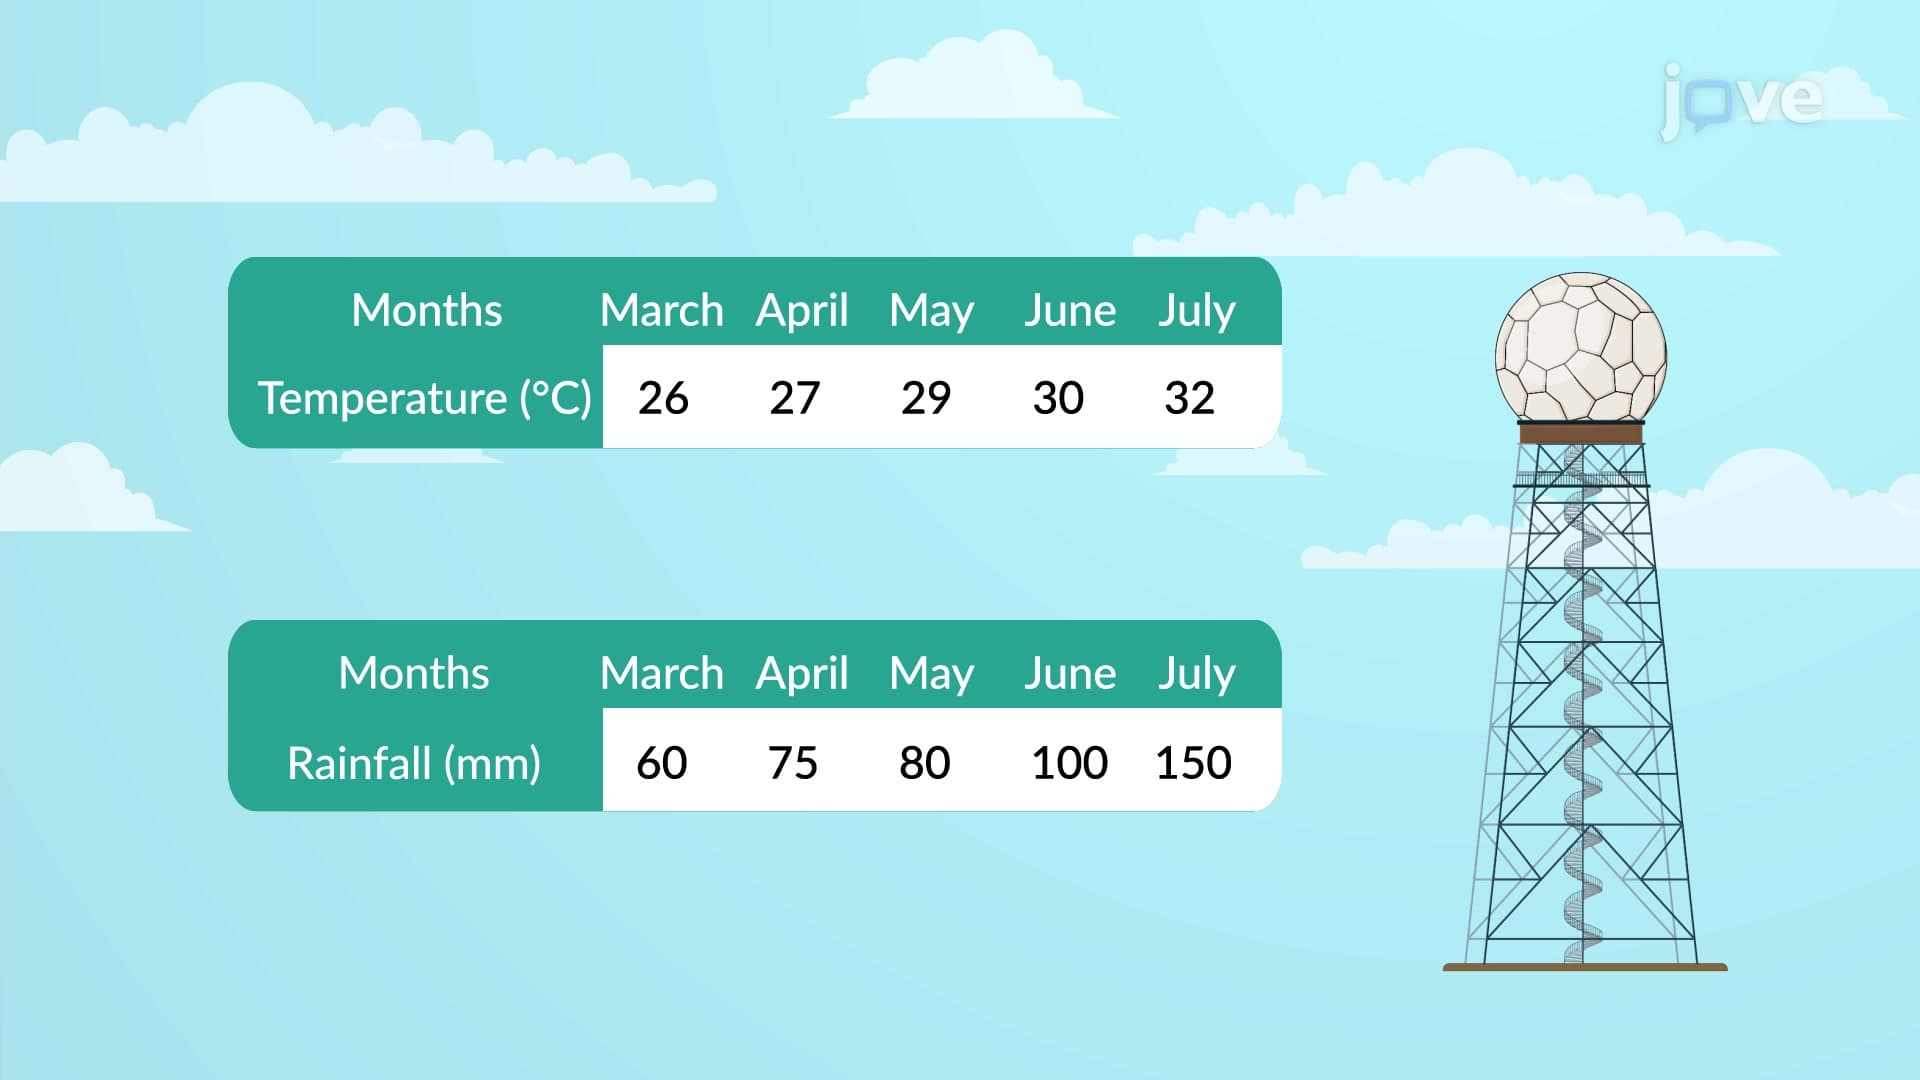
Coefficient of Variation
The coefficient of variation is a practical statistical tool in finance. It allows investors to assess the volatility or...