Related Experiment Video
Updated: Aug 9, 2026


Development of an Individual-Tree Basal Area Increment Model using a Linear Mixed-Effects Approach
Published on: July 3, 2020
Locally asymptotically rank-based procedures for testing autoregressive moving average dependence
1Institut de Statistique, Université Libre de Bruxelles, Campus Plaine C.P. 210, B-1050 Brussels, Belgium.

Abstract:
The problem of testing a given autoregressive moving average (ARMA) model (in which the density of the generating white noise is unspecified) against other ARMA models is considered. A distribution-free asymptotically most powerful test, based on a generalized linear serial rank statistic, is provided against contiguous ARMA alternatives with specified coefficients. In the case in which the ARMA model in the alternative has unspecified coefficients, the asymptotic sufficiency (in the sense of Hájek) of a finite-dimensional vector of rank statistics is established. This asymptotic sufficiency is used to derive an asymptotically maximin most powerful test, based on a generalized quadratic serial rank statistic. The asymptotically maximin optimal test statistic can be interpreted as a rank-based, weighted version of the classical Box-Pierce portmanteau statistic, to which it reduces, in some particular problems, under gaussian assumptions.
Related Concept Videos
 01:21
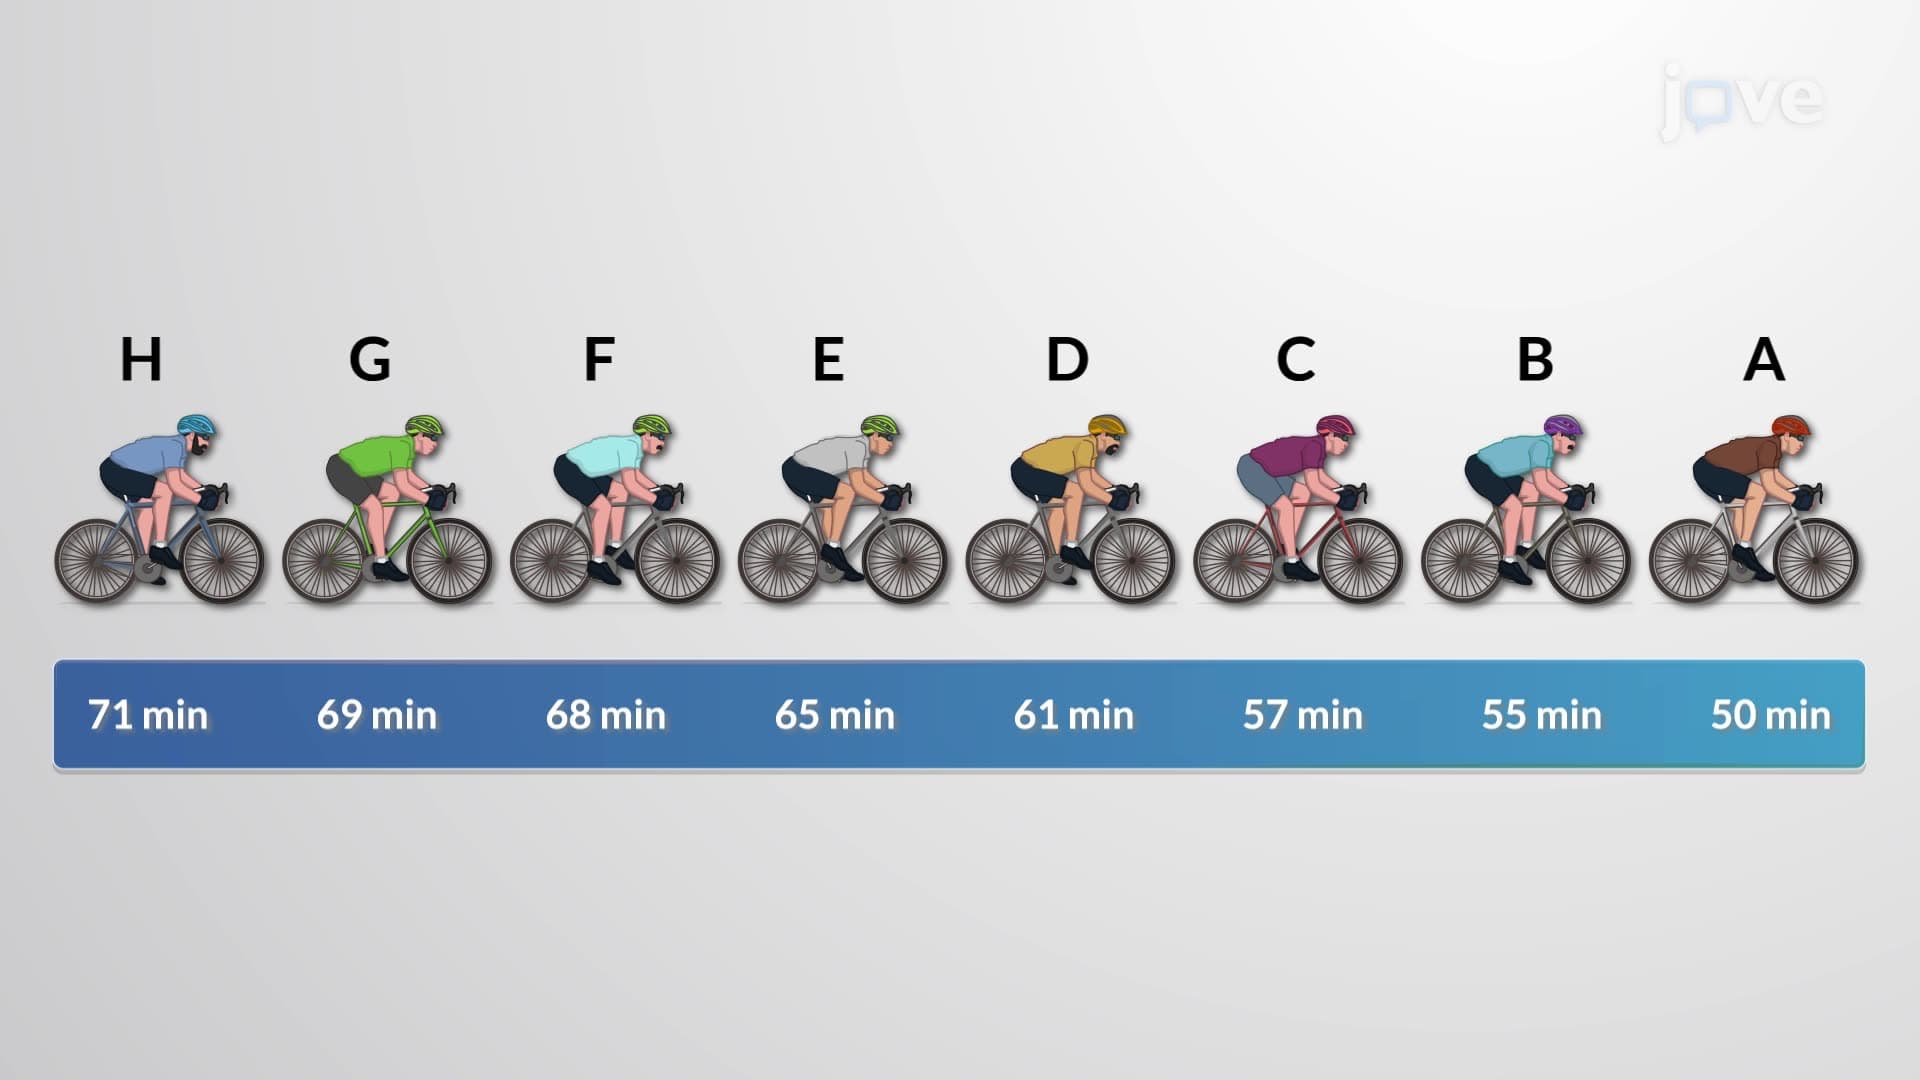
Friedman Two-way Analysis of Variance by Ranks
 01:02
Ranks
 01:21
Wilcoxon Rank-Sum Test
 01:16
The Anderson-Darling Test
 01:16
Kendall's Tau Test
A τ value of +1 indicates that...
 01:17
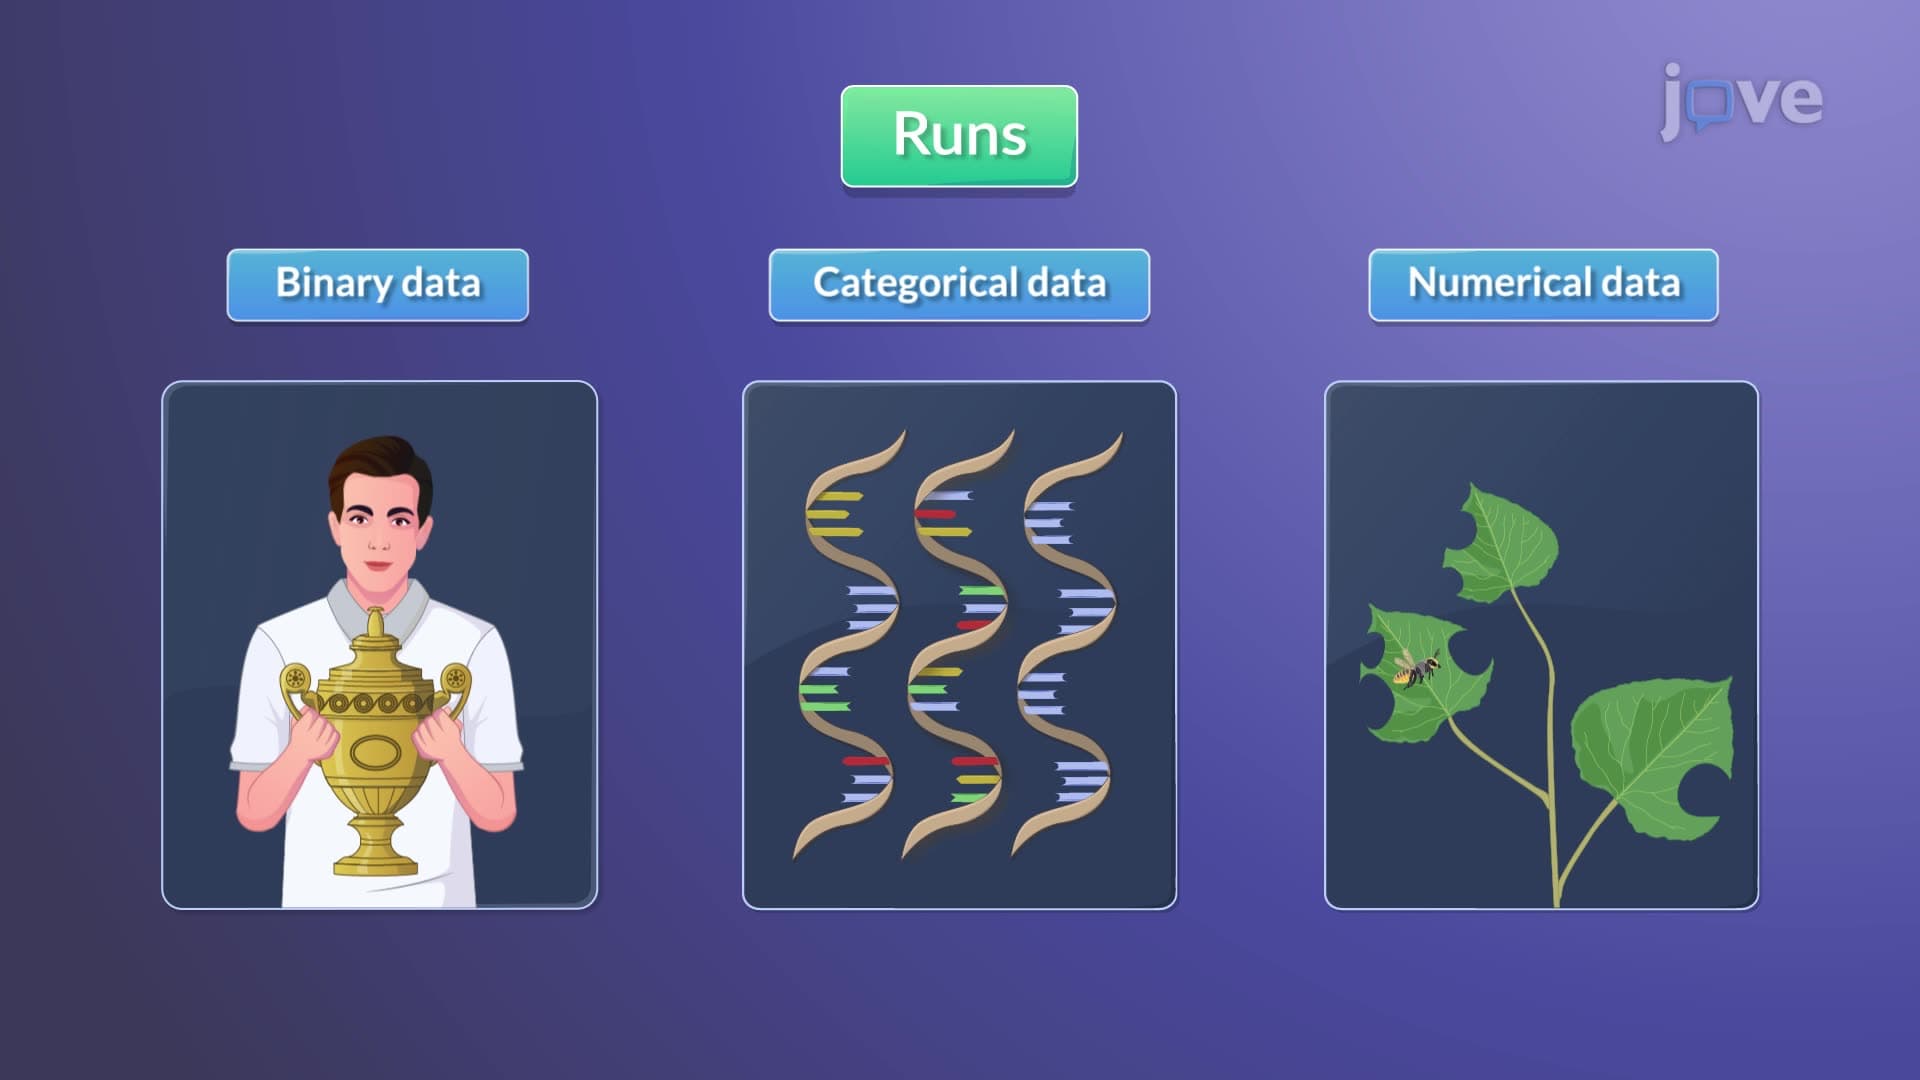
Wald-Wolfowitz Runs Test I
The test works...