Related Experiment Videos
Computational learning techniques for intraday FX trading using popular technical indicators
M H Dempster1, T W Payne, Y Romahi
1Centre for Financial Research, Judge institute of Management, University of Cambridge, Cambridge, UK.

Abstract:
We consider strategies which use a collection of popular technical indicators as input and seek a profitable trading rule defined in terms of them. We consider two popular computational learning approaches, reinforcement learning and genetic programming, and compare them to a pair of simpler methods: the exact solution of an appropriate Markov decision problem, and a simple heuristic. We find that although all methods are able to generate significant in-sample and out-of-sample profits when transaction costs are zero, the genetic algorithm approach is superior for non-zero transaction costs, although none of the methods produce significant profits at realistic transaction costs. We also find that there is a substantial danger of overfitting if in-sample learning is not constrained.
Related Concept Videos
 01:25
First Derivative Test: Problem Solving
 01:20
Deconvolution
Deconvolution involves several mathematical techniques to derive the impulse response. One common approach is polynomial division. In this method, the input and output sequences are treated as coefficients of...
 01:29
Econometric Views (EViews)
 01:30
Derivatives of Inverse Trigonometric Functions
 01:24
Convolution: Math, Graphics, and Discrete Signals
To simplify the convolution integral, it is assumed that both the input signal and impulse response are zero for negative time values. The graphical convolution process...
 01:10
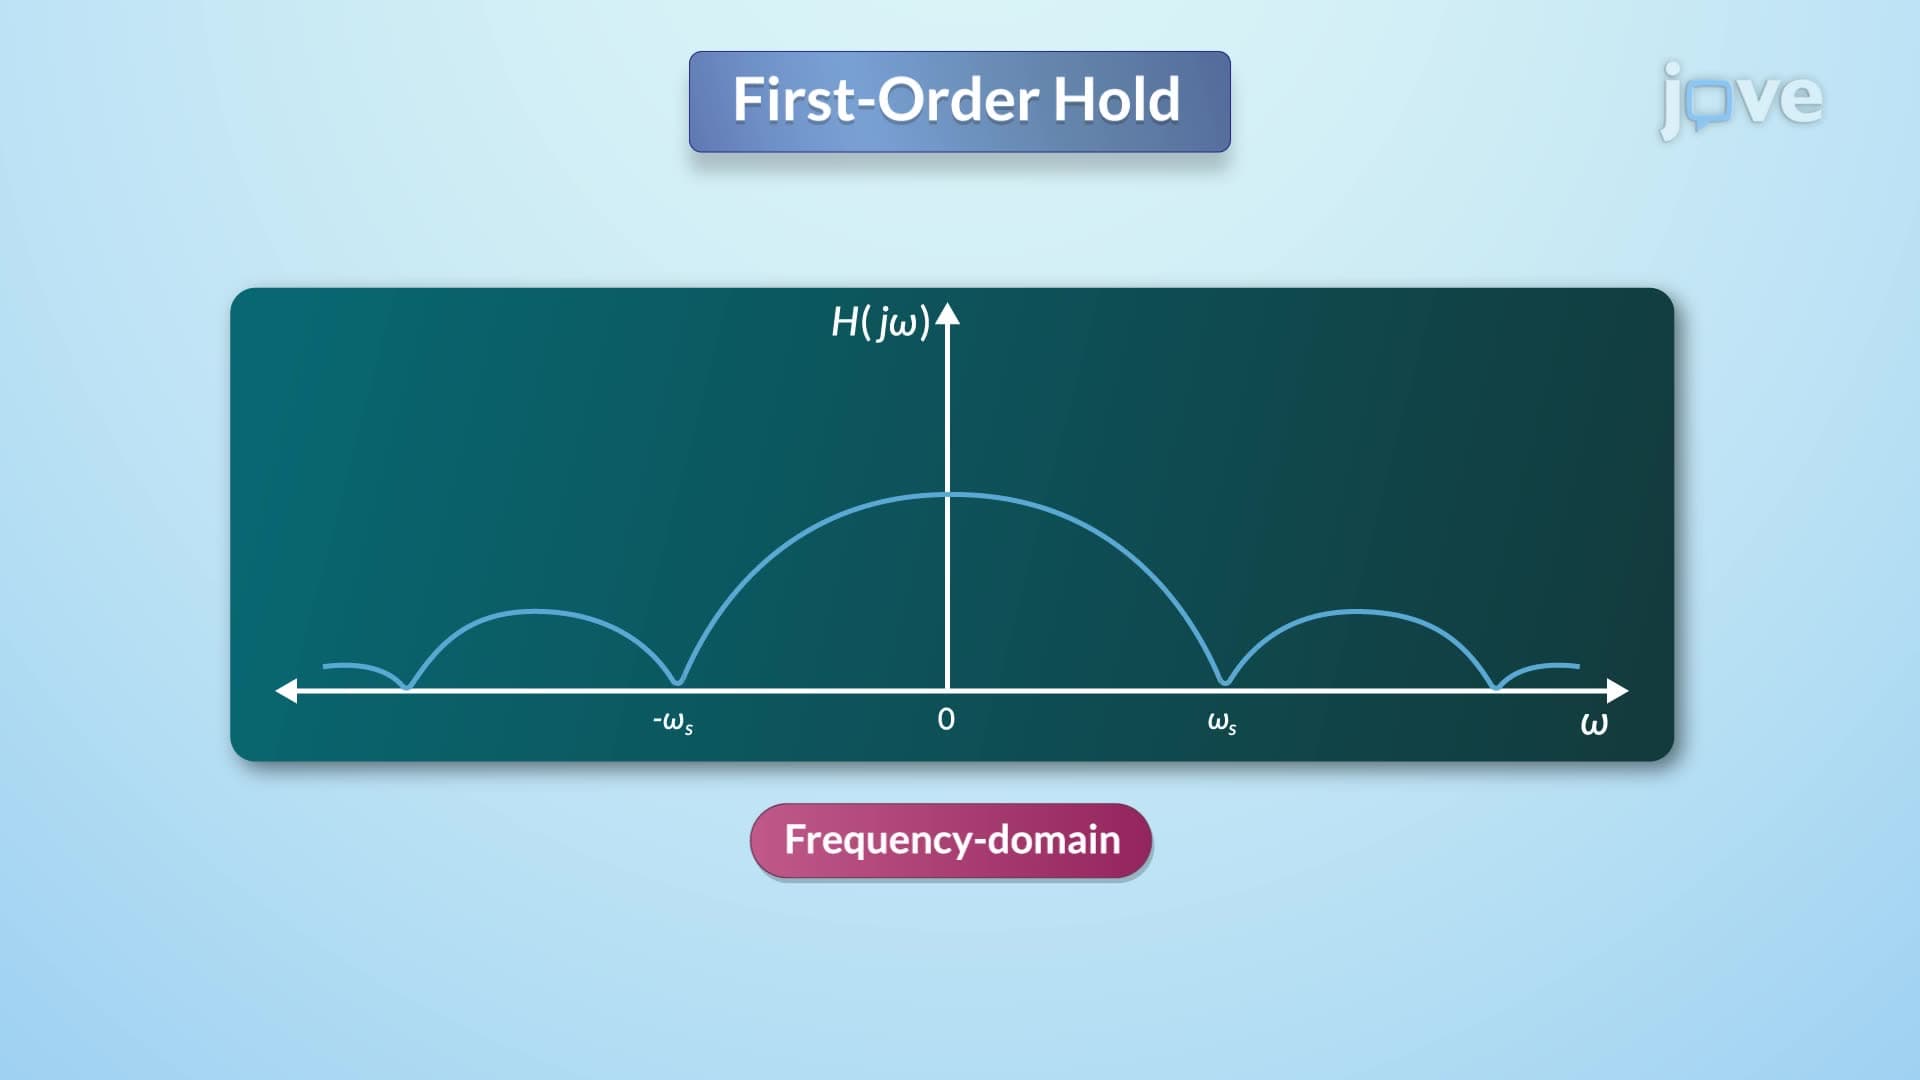
Reconstruction of Signal using Interpolation