Related Experiment Video
Updated: Jun 16, 2026


An R-Based Landscape Validation of a Competing Risk Model
Published on: September 16, 2022
High-dimensional Cox models: the choice of penalty as part of the model building process
Axel Benner1, Manuela Zucknick, Thomas Hielscher
1Division of Biostatistics, German Cancer Research Center, Heidelberg, Germany. benner@dkfz.de

Abstract:
The Cox proportional hazards regression model is the most popular approach to model covariate information for survival times. In this context, the development of high-dimensional models where the number of covariates is much larger than the number of observations (p>>n) is an ongoing challenge. A practicable approach is to use ridge penalized Cox regression in such situations. Beside focussing on finding the best prediction rule, one is often interested in determining a subset of covariates that are the most important ones for prognosis. This could be a gene set in the biostatistical analysis of microarray data. Covariate selection can then, for example, be done by L(1)-penalized Cox regression using the lasso (Tibshirani (1997). Statistics in Medicine 16, 385-395). Several approaches beyond the lasso, that incorporate covariate selection, have been developed in recent years. This includes modifications of the lasso as well as nonconvex variants such as smoothly clipped absolute deviation (SCAD) (Fan and Li (2001). Journal of the American Statistical Association 96, 1348-1360; Fan and Li (2002). The Annals of Statistics 30, 74-99). The purpose of this article is to implement them practically into the model building process when analyzing high-dimensional data with the Cox proportional hazards model. To evaluate penalized regression models beyond the lasso, we included SCAD variants and the adaptive lasso (Zou (2006). Journal of the American Statistical Association 101, 1418-1429). We compare them with "standard" applications such as ridge regression, the lasso, and the elastic net. Predictive accuracy, features of variable selection, and estimation bias will be studied to assess the practical use of these methods. We observed that the performance of SCAD and adaptive lasso is highly dependent on nontrivial preselection procedures. A practical solution to this problem does not yet exist. Since there is high risk of missing relevant covariates when using SCAD or adaptive lasso applied after an inappropriate initial selection step, we recommend to stay with lasso or the elastic net in actual data applications. But with respect to the promising results for truly sparse models, we see some advantage of SCAD and adaptive lasso, if better preselection procedures would be available. This requires further methodological research.

Related Concept Videos
 01:23
Quadratic Models
 01:29
Mechanistic Models: Compartment Models in Algorithms for Numerical Problem Solving
In individual population analyses, different algorithms are employed, such as Cauchy's method, which uses a...
 01:14
Multicompartment Models: Overview
These models offer a more comprehensive representation of drug behavior in the body than one-compartment models. They accommodate the complexity of drug distribution,...
 01:24
One-Compartment Open Model: Wagner-Nelson and Loo Riegelman Method for ka Estimation
On...
 01:17
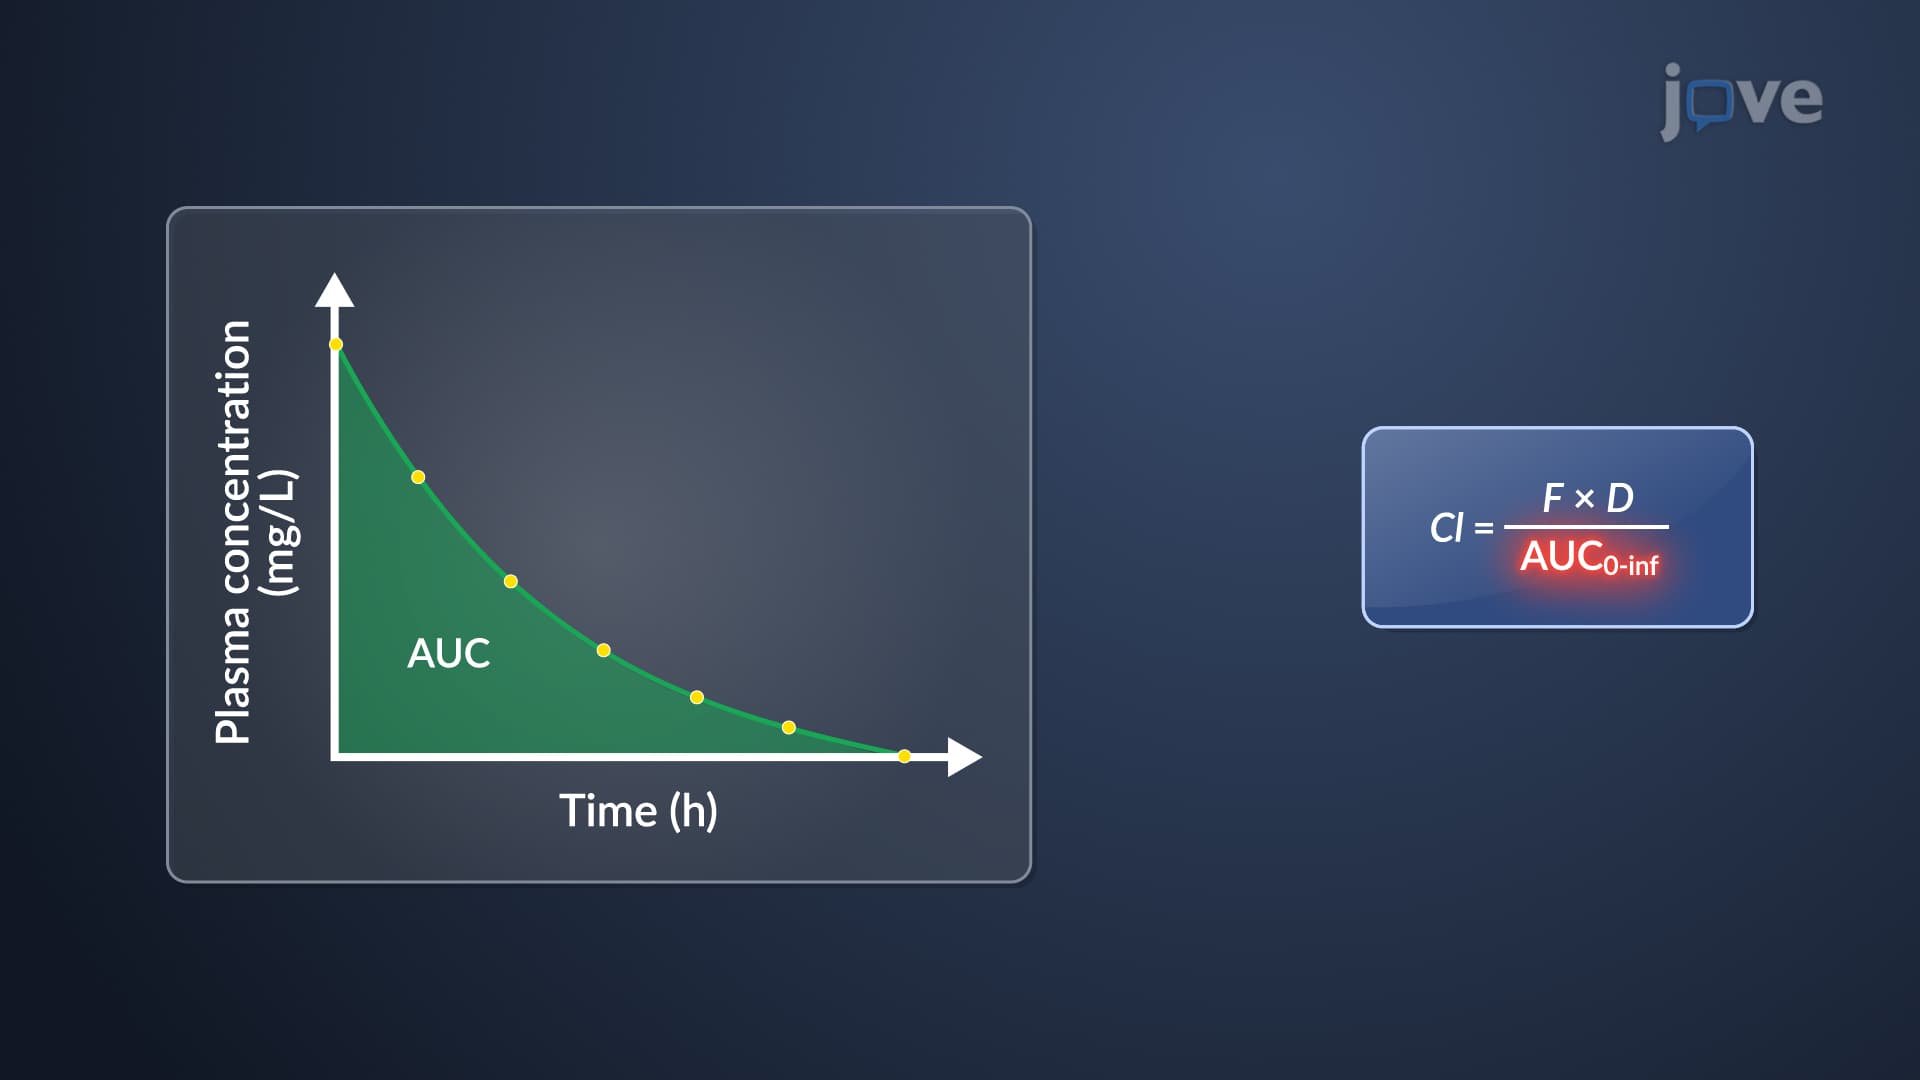
Clearance Models: Noncompartmental Models
The noncompartmental approach capitalizes on extensive sampling data, correlating the volume of distribution to systemic exposure and the administered dosage. This method enables...
 01:06
Model Approaches for Pharmacokinetic Data: Distributed Parameter Models
The distributed parameter models are specifically designed to account for variations and differences in some drug classes. This model is particularly useful for assessing regional concentrations of anticancer or...