Related Experiment Video
Updated: May 24, 2026

The Motivation for Alcohol Reward: Predictors of Progressive-Ratio Intravenous Alcohol Self-Administration in Humans
Published on: April 28, 2022
The impact of a 25-cent-per-drink alcohol tax increase
James I Daley1, Mandy A Stahre, Frank J Chaloupka
1Boston University School of Medicine, Boston Medical Center, Massachusetts, USA.

Background:
Excessive alcohol consumption causes 79,000 deaths annually in the U.S., shortening the lives of those who die from it by approximately 30 years. Although alcohol taxation is an effective measure to reduce excessive consumption and related harm, some argue that increasing alcohol taxes places an unfair economic burden on "responsible" drinkers and socially disadvantaged people.
Purpose:
To examine the impact of a hypothetic tax increase based on alcohol consumption and sociodemographic characteristics of current drinkers, individually and in aggregate.
Methods:
Data from the 2008 Behavioral Risk Factor Surveillance System survey were analyzed from 2010 to 2011 to determine the net financial impact of a hypothetic 25-cent-per-drink tax increase on current drinkers in the U.S. Higher-risk drinkers were defined as those whose past-30-day consumption included binge drinking, heavy drinking, drinking in excess of the U.S. Dietary Guidelines, and alcohol-impaired driving.
Results:
Of U.S. adults who consumed alcohol in the past 30 days, 50.4% (or approximately 25% of the total U.S. population) were classified as higher-risk drinkers. The tax increase would result in a 9.2% reduction in alcohol consumption, including an 11.4% reduction in heavy drinking. Compared with lower-risk drinkers, higher-risk drinkers would pay 4.7 times more in net increased annual per capita taxes, and 82.7% of the net increased annual aggregate taxes. Lower-risk drinkers would pay less than $30 in net increased taxes annually. In aggregate, groups who paid the most in net tax increases included those who were white, male, aged 21-50 years, earning ≥$50,000 per year, employed, and had a college degree.
Conclusions:
A 25-cent-per-drink alcohol tax increase would reduce excessive drinking, and higher-risk drinkers would pay the substantial majority of the net tax increase.
More Related Videos
 08:45
Modeling Alcohol Consumption in Rodents Using Two-Bottle Choice Home Cage Drinking and Microstructural Analysis
Published on: November 8, 2024
 08:05
A Prediction Error-driven Retrieval Procedure for Destabilizing and Rewriting Maladaptive Reward Memories in Hazardous Drinkers
Published on: January 5, 2018
Related Concept Videos
 01:16
Hypothesis Test for Test of Independence
H0: The two variables (factors)...
 01:25
Microbes in Beverage Production
 02:31
Protection of Alcohols
Protection
It defines a protecting group as the masking agent to make the more reactive species inert to a given set of conditions. This concept is depicted via the illustration of liquid flow through different outlets in an assembly of pipes. The analogy helps to understand the role...
 02:32
Physical Properties of Alcohols and Phenols
Alcohols possess a higher boiling point than aliphatic hydrocarbons of similar...
 02:23
Alcohols from Carbonyl Compounds: Reduction
Catalytic hydrogenation is similar to the reduction of an alkene or alkyne by adding H2 across the pi bond in the presence of transition metal catalysts like Raney Ni, Pd–C, Pt, or Ru. Aldehydes and ketones can be reduced by this method, often under mild to moderate heat (25–100°C) and...
 01:03
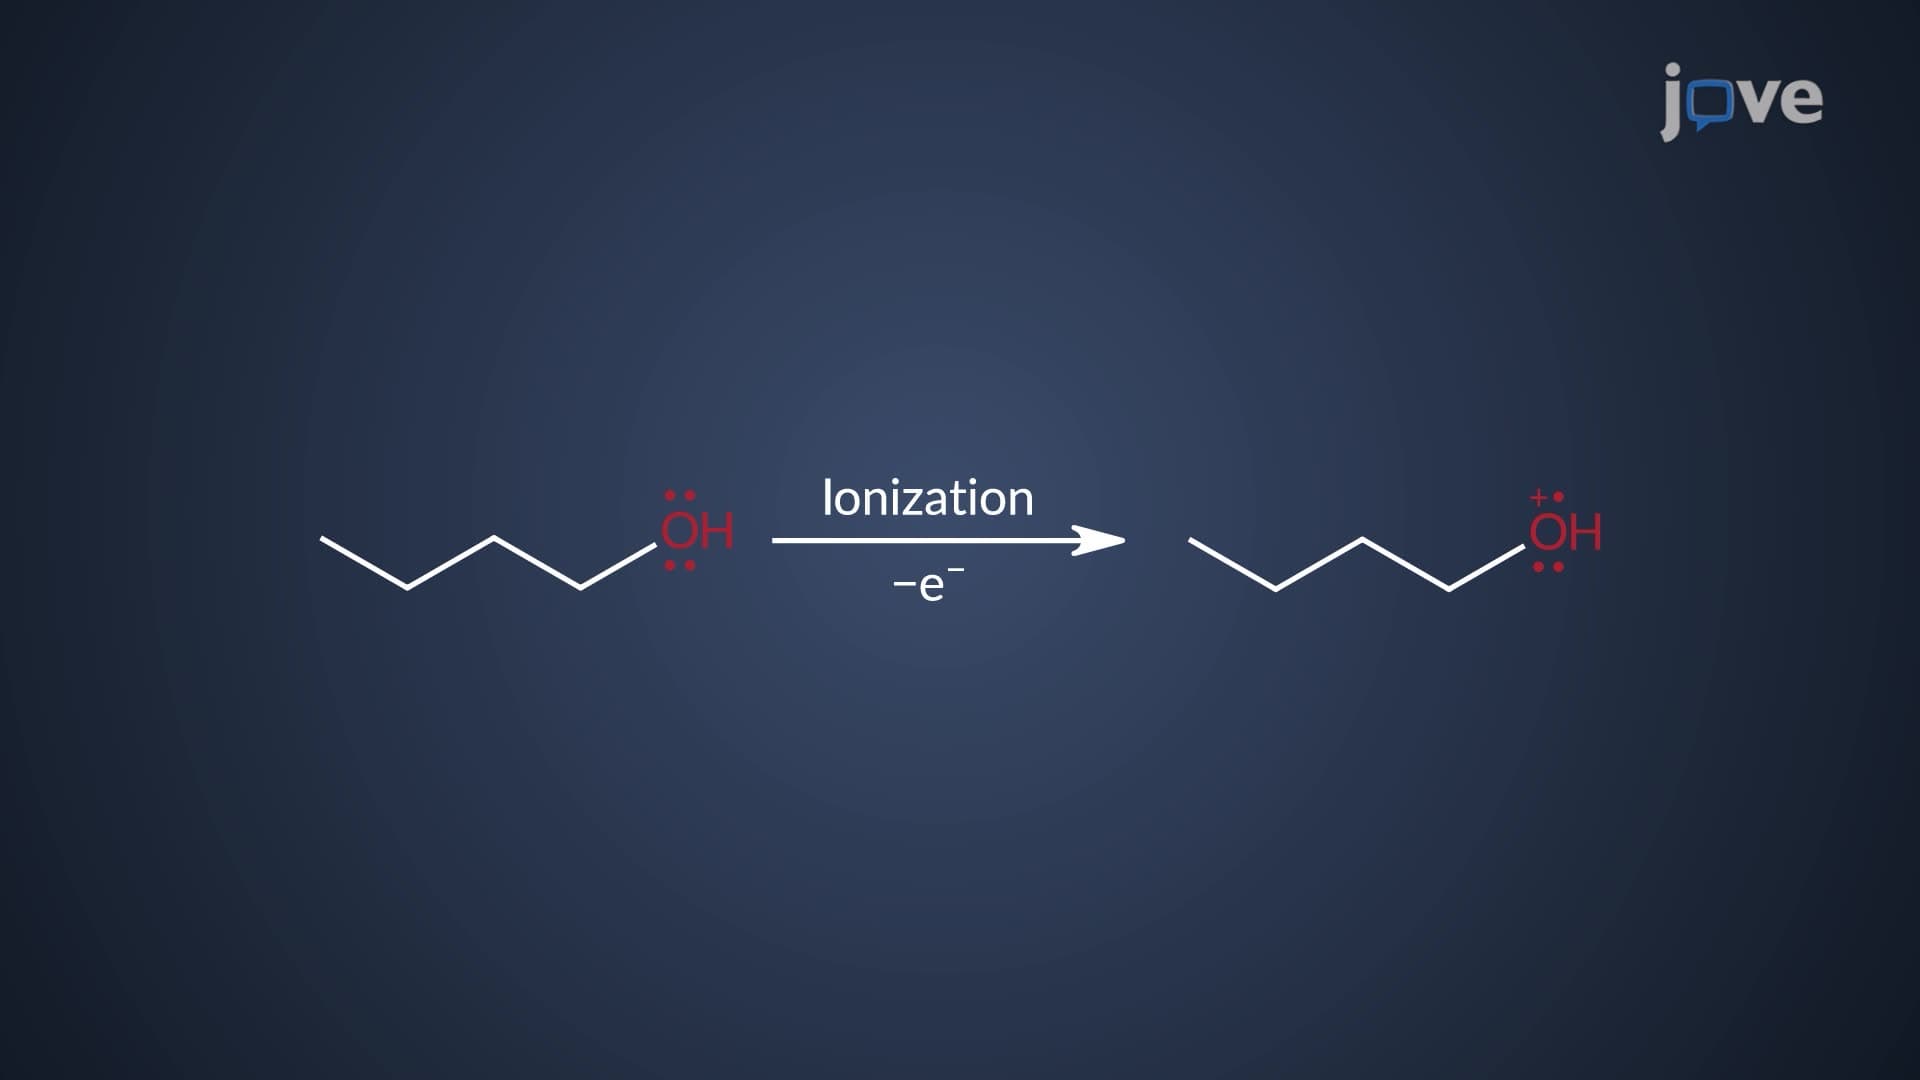
Mass Spectrometry: Alcohol Fragmentation