Related Experiment Video
Updated: May 22, 2026

An R-Based Landscape Validation of a Competing Risk Model
Published on: September 16, 2022
Quantile uncertainty and value-at-risk model risk
Carol Alexander1, José María Sarabia
1ICMA Centre, Henley Business School at the University of Reading, Reading RG6 6BA, UK. c.alexander@icmacentre.rdg.ac.uk

Abstract:
This article develops a methodology for quantifying model risk in quantile risk estimates. The application of quantile estimates to risk assessment has become common practice in many disciplines, including hydrology, climate change, statistical process control, insurance and actuarial science, and the uncertainty surrounding these estimates has long been recognized. Our work is particularly important in finance, where quantile estimates (called Value-at-Risk) have been the cornerstone of banking risk management since the mid 1980s. A recent amendment to the Basel II Accord recommends additional market risk capital to cover all sources of "model risk" in the estimation of these quantiles. We provide a novel and elegant framework whereby quantile estimates are adjusted for model risk, relative to a benchmark which represents the state of knowledge of the authority that is responsible for model risk. A simulation experiment in which the degree of model risk is controlled illustrates how to quantify Value-at-Risk model risk and compute the required regulatory capital add-on for banks. An empirical example based on real data shows how the methodology can be put into practice, using only two time series (daily Value-at-Risk and daily profit and loss) from a large bank. We conclude with a discussion of potential applications to nonfinancial risks.
Related Concept Videos
 00:54
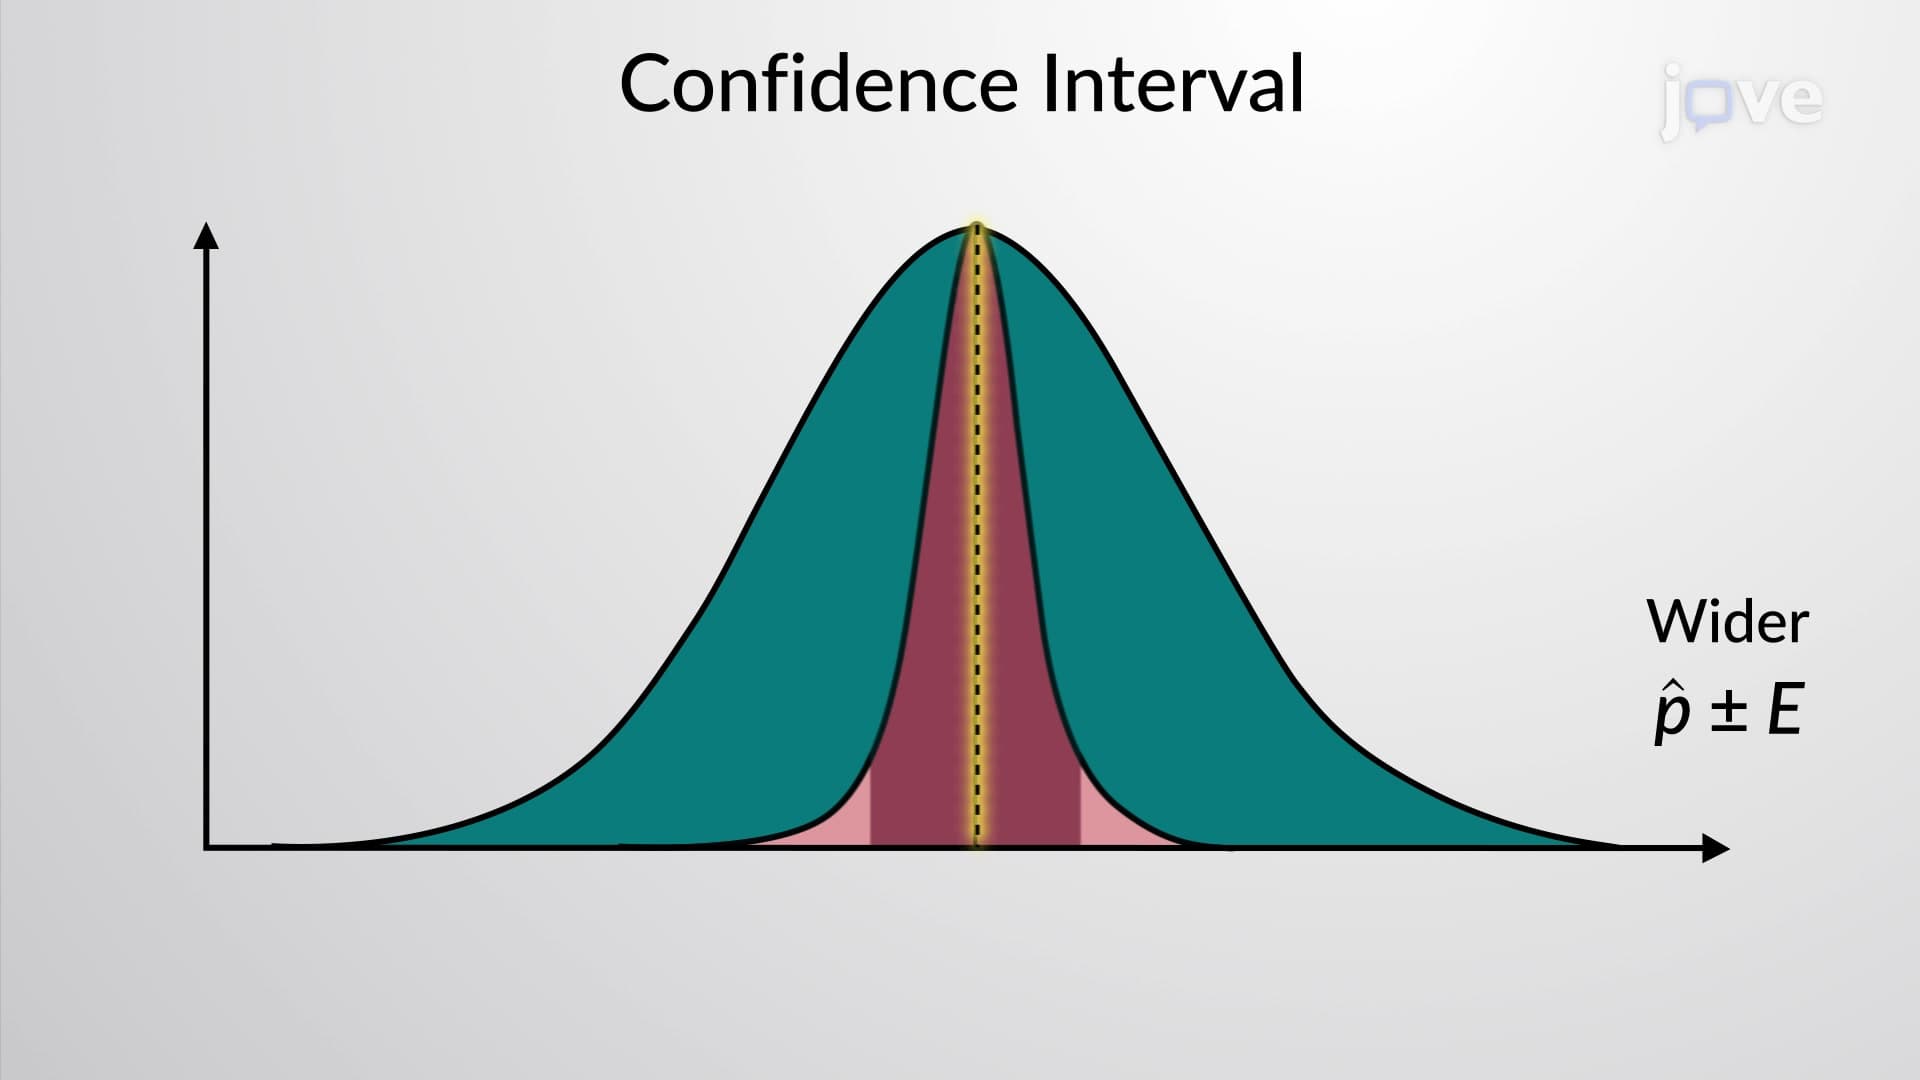
Uncertainty: Confidence Intervals
 01:31
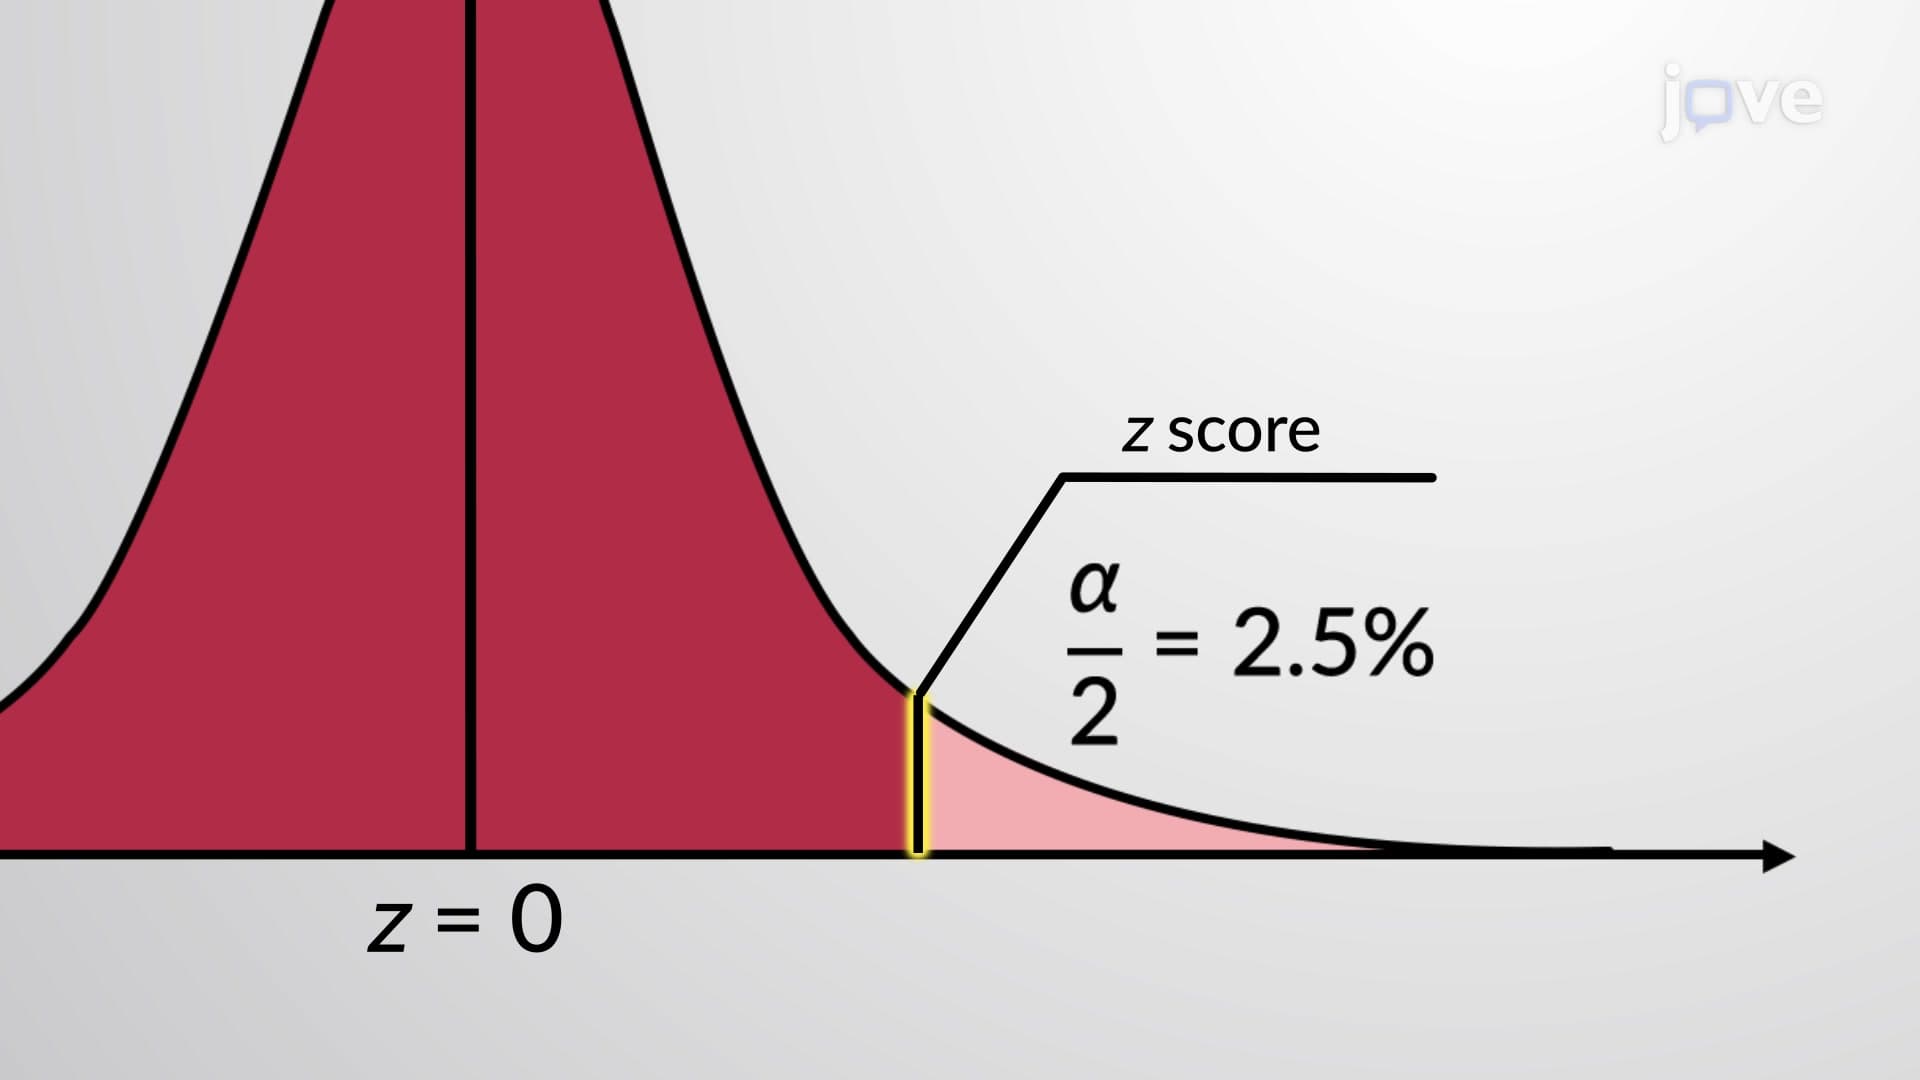
Critical Values
 00:59
Uncertainty: Overview
 01:15
Quartile
1; 1; 2; 2; 4; 6; 6.8; 7.2; 8; 8.3; 9; 10; 10; 11.5
The median or second quartile is seven. The lower half of the...
 01:15
Variance
 01:21
Confidence Intervals
A confidence...