Related Experiment Video
Updated: May 11, 2026
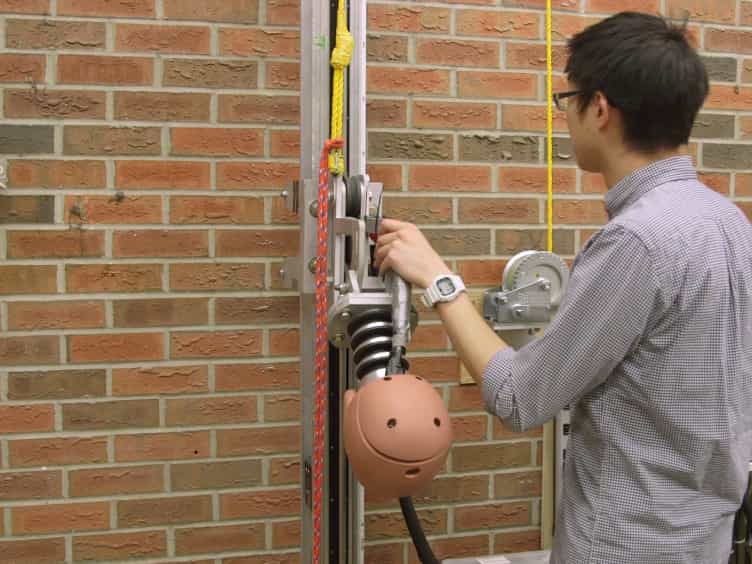

A Test Bed to Examine Helmet Fit and Retention and Biomechanical Measures of Head and Neck Injury in Simulated Impact
Published on: September 21, 2017
Managing moral hazard in motor vehicle accident insurance claims
Shanil Ebrahim1, Jason W Busse, Gordon H Guyatt
1Department of Clinical Epidemiology and Biostatistics, McMaster University, HHC 2C, 1280 Main Street West, Hamilton, ON L8S 4K1, Canada. shanil.ebrahim@utoronto.ca

Abstract:
Motor vehicle accident (MVA) insurance in Canada is based primarily on two different compensation systems: (i) no-fault, in which policyholders are unable to seek recovery for losses caused by other parties (unless they have specified dollar or verbal thresholds) and (ii) tort, in which policyholders may seek general damages. As insurance companies pay for MVA-related health care costs, excess use of health care services may occur as a result of consumers' (accident victims) and/or producers' (health care providers) behavior - often referred to as the moral hazard of insurance. In the United States, moral hazard is greater for low dollar threshold no-fault insurance compared with tort systems. In Canada, high dollar threshold or pure no-fault versus tort systems are associated with faster patient recovery and reduced MVA claims. These findings suggest that high threshold no-fault or pure no-fault compensation systems may be associated with improved outcomes for patients and reduced moral hazard.

Related Concept Videos
 01:22
Ethics and Bioethics
 01:29
Impression Management Techniques III: Aligning Actions
 01:30
Ethical Dilemmas II
 01:27
Ethical Issues
Ethical Concerns in Healthcare:
 01:14
Torts I
Intentional...
 01:27
Nursing Ethical Principles II
Consider the following scenario, which illustrates how these principles are applied in the care of Mr. John, a fifty-year-old teacher diagnosed with metastatic liver cancer.
Initially, Mr. John's cancer...