Related Experiment Video
Updated: May 8, 2026
Rapid Repetition Rate Fluctuation Measurement of Soliton Crystals in a Microresonator
Published on: December 15, 2021
Reverse resonance in stock prices of financial system with periodic information
Jiang-Cheng Li1, Dong-Cheng Mei
1Department of Physics, Yunnan University, Kunming, 650091, People's Republic of China.

Abstract:
We investigate the stochastic resonance of the stock prices in a finance system with the Heston model. The extrinsic and intrinsic periodic information are introduced into the stochastic differential equations of the Heston model for stock price by focusing on the signal power amplification (SPA). We find that for both cases of extrinsic and intrinsic periodic information a phenomenon of reverse resonance emerges in the behaviors of SPA as a function of the system and external driving parameters. Moreover, in both cases, a phenomenon of double reverse resonance is observed in the behavior of SPA versus the amplitude of volatility fluctuations, by increasing the cross correlation between the noise sources in the Heston model.
Related Concept Videos
 01:14
Sound Waves: Resonance
 01:19
Concept of Resonance and its Characteristics
 01:23
Parallel Resonance
 01:12
Double Resonance Techniques: Overview
Spin decoupling is usually achieved by...
 01:26
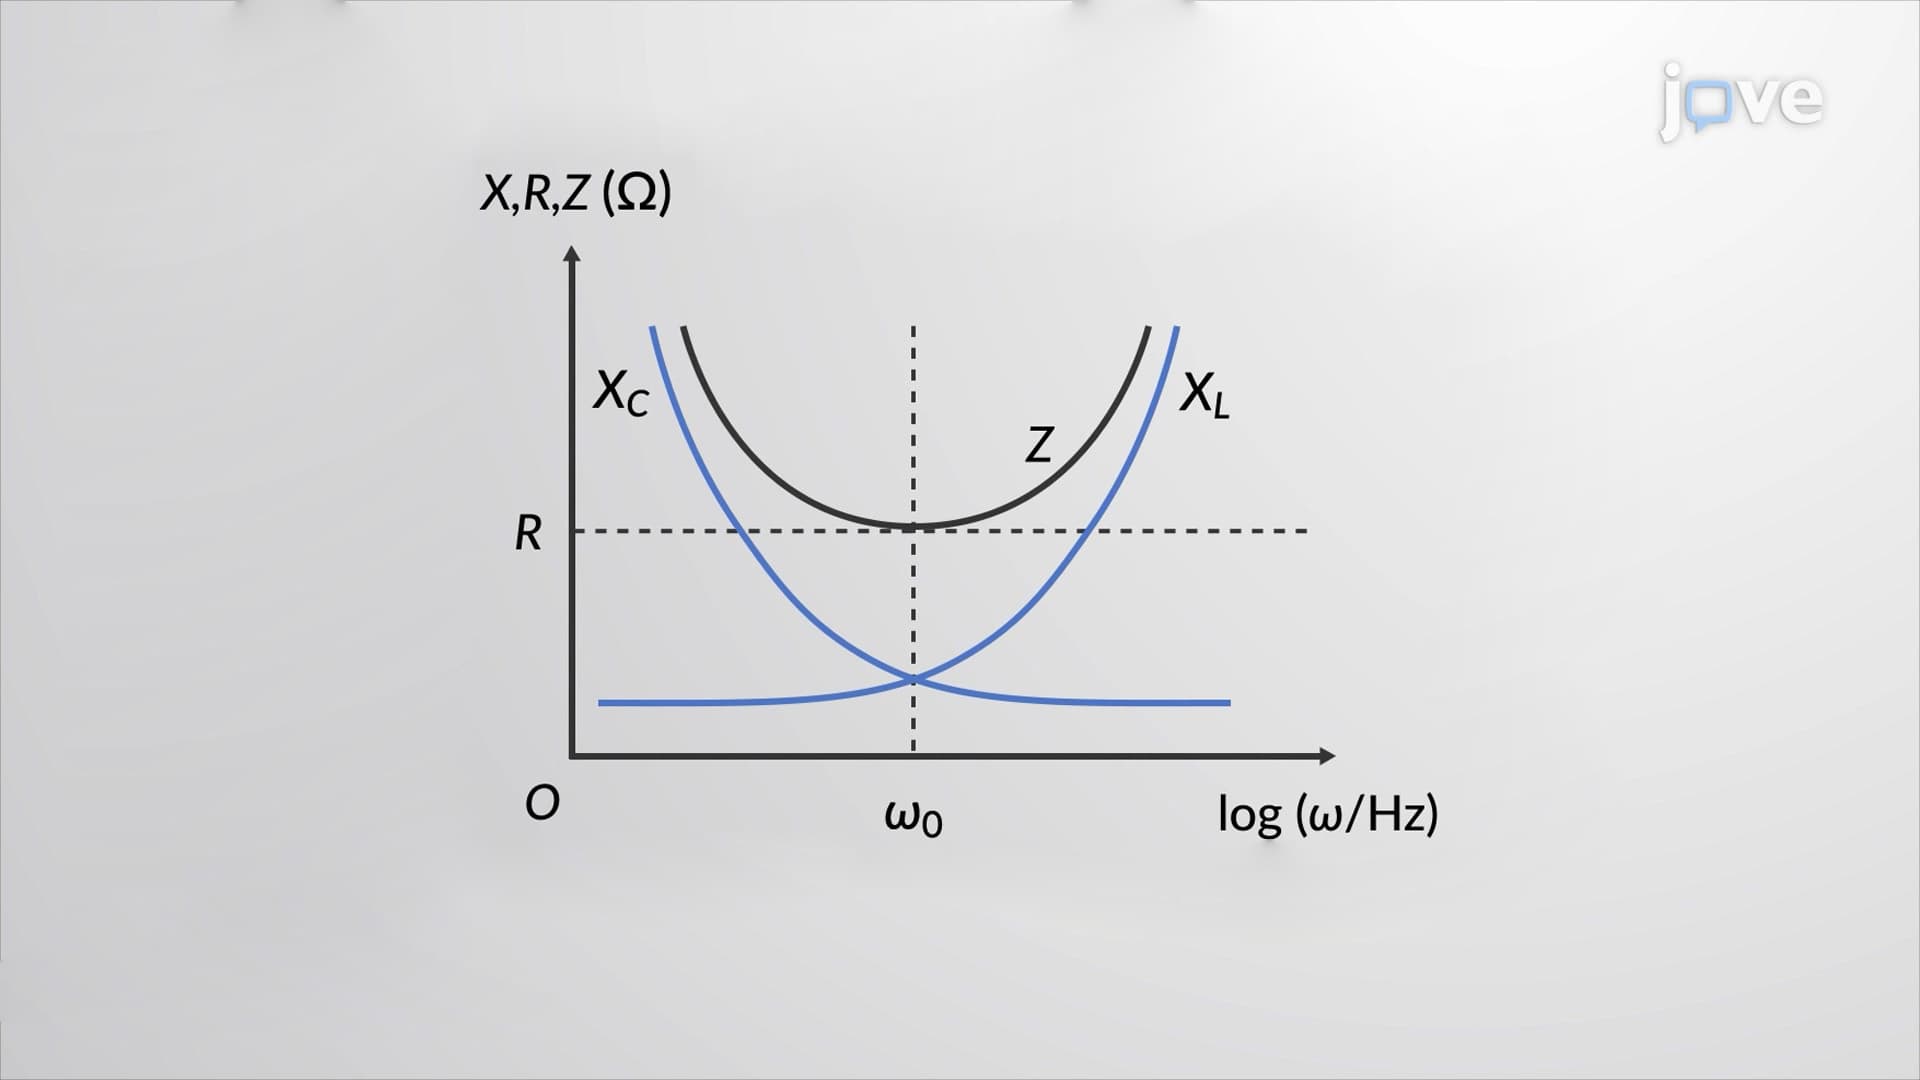
Resonance in an AC Circuit
 01:17
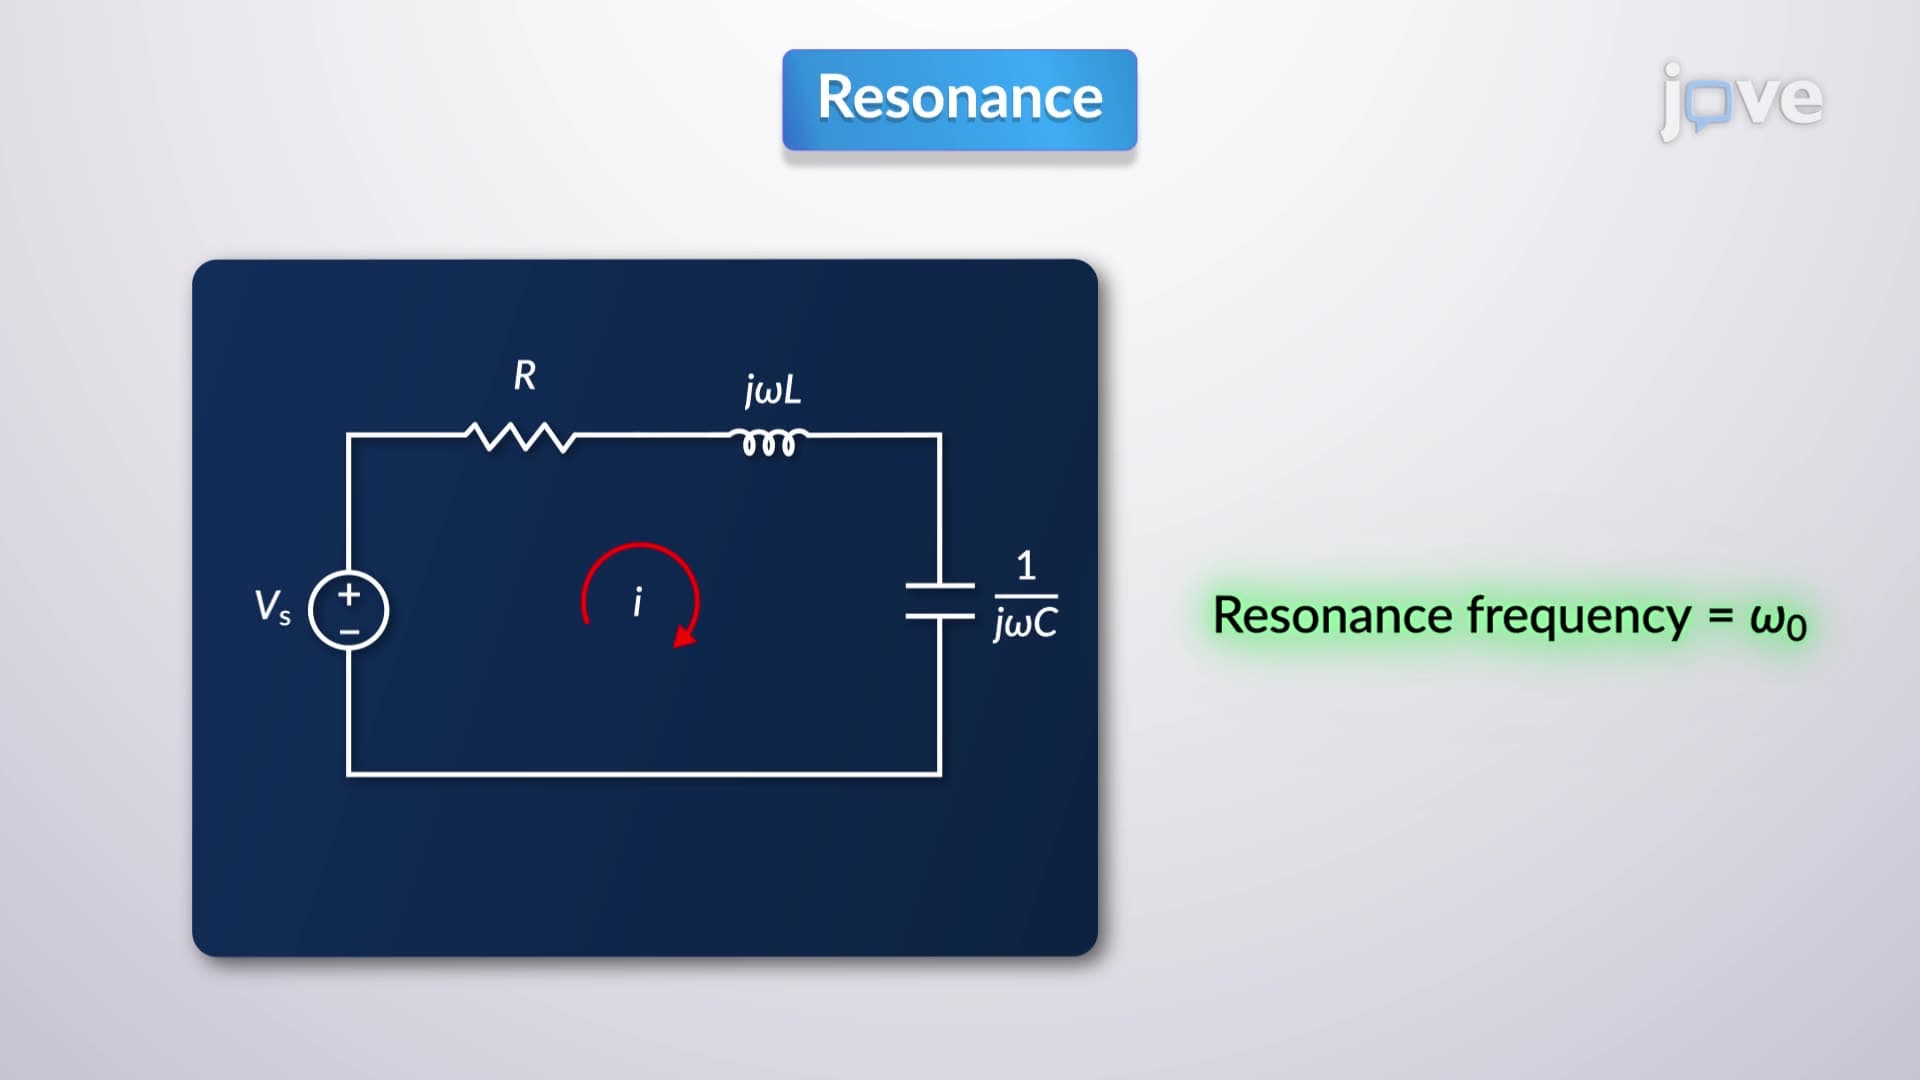
Series Resonance