Related Experiment Video
Updated: Apr 29, 2026


An R-Based Landscape Validation of a Competing Risk Model
Published on: September 16, 2022
A random matrix approach to credit risk
Michael C Münnix1, Rudi Schäfer1, Thomas Guhr1
1Faculty of Physics, University of Duisburg-Essen, Essen, Germany.

Abstract:
We estimate generic statistical properties of a structural credit risk model by considering an ensemble of correlation matrices. This ensemble is set up by Random Matrix Theory. We demonstrate analytically that the presence of correlations severely limits the effect of diversification in a credit portfolio if the correlations are not identically zero. The existence of correlations alters the tails of the loss distribution considerably, even if their average is zero. Under the assumption of randomly fluctuating correlations, a lower bound for the estimation of the loss distribution is provided.
Related Concept Videos
 01:20
Actuarial Approach
Consider the example of a high-risk surgical procedure with significant early-stage mortality. A two-year clinical study is conducted,...
 01:17
Wald-Wolfowitz Runs Test I
The test works...
 01:09
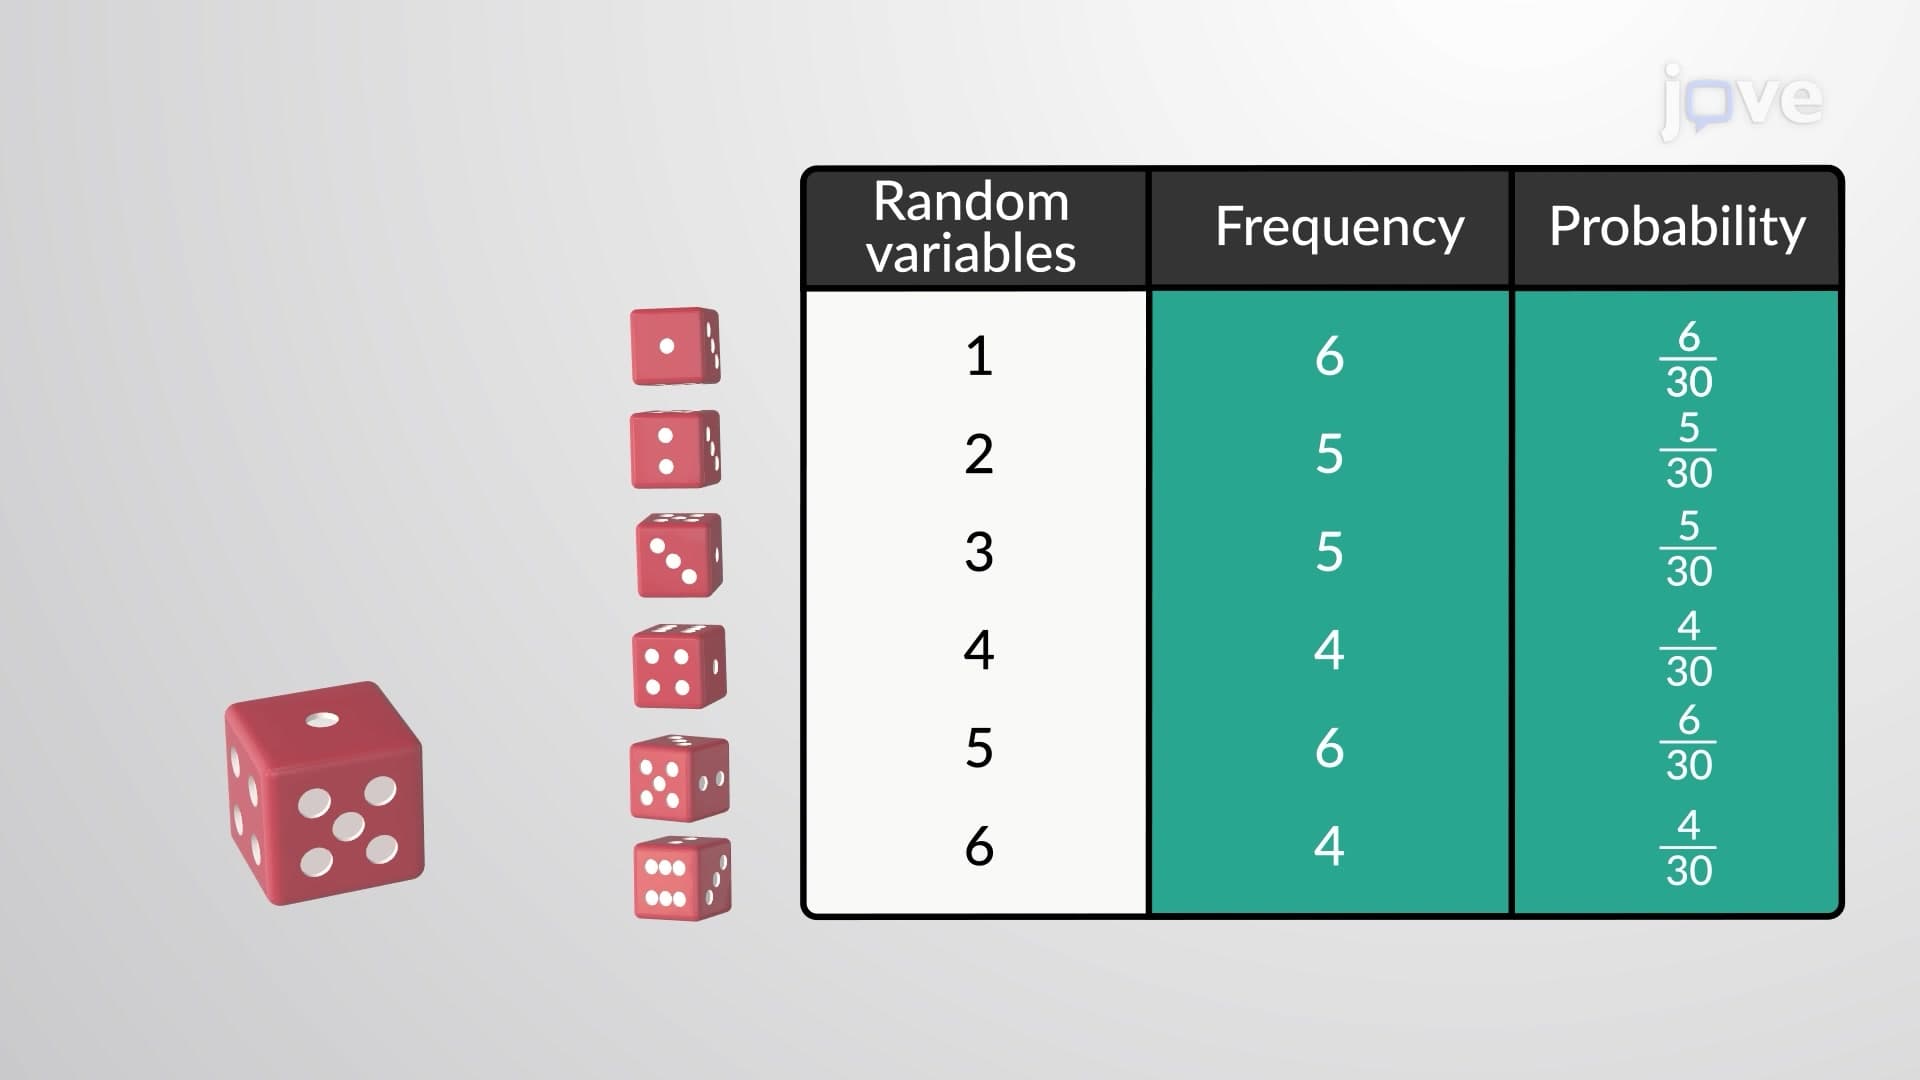
Random Variables
Uppercase letters such as X or Y denote a random variable. Lowercase letters like x or y denote the value of a random variable. If X is a random variable, then X is written in words, and x is given as a number.
For example, let X = the...
 01:17
Wald-Wolfowitz Runs Test II
For binary data, runs are identified using symbols such as + and −, or equivalently, 1s and...
 01:22
Bias
In statistics, a sampling bias is created when a sample is collected from a population, and some members of the population are not as likely to be chosen as others (remember, each member...
 01:13
Randomized Experiments
Simple randomization
Simple...