Related Experiment Video
Updated: Apr 25, 2026
Identification of Disease-related Spatial Covariance Patterns using Neuroimaging Data
Published on: June 26, 2013
Convergence of Sample Eigenvalues, Eigenvectors, and Principal Component Scores for Ultra-High Dimensional Data
Seunggeun Lee1, Fei Zou2, Fred A Wright3
1Department of Biostatistics, University of Michigan, 1415 Washington Heights, Ann Arbor, Michigan 48109, U.S.A.

Abstract:
The development of high-throughput biomedical technologies has led to increased interest in the analysis of high-dimensional data where the number of features is much larger than the sample size. In this paper, we investigate principal component analysis under the ultra-high dimensional regime, where both the number of features and the sample size increase as the ratio of the two quantities also increases. We bridge the existing results from the finite and the high-dimension low sample size regimes, embedding the two regimes in a more general framework. We also numerically demonstrate the universal application of the results from the finite regime.
Related Concept Videos
 01:08
Vector Algebra: Method of Components
In many applications, the magnitudes and directions of...
 01:14
Principal Moments of Area
The principal moment of inertia axes are the...
 01:08
Outliers and Influential Points
 01:21
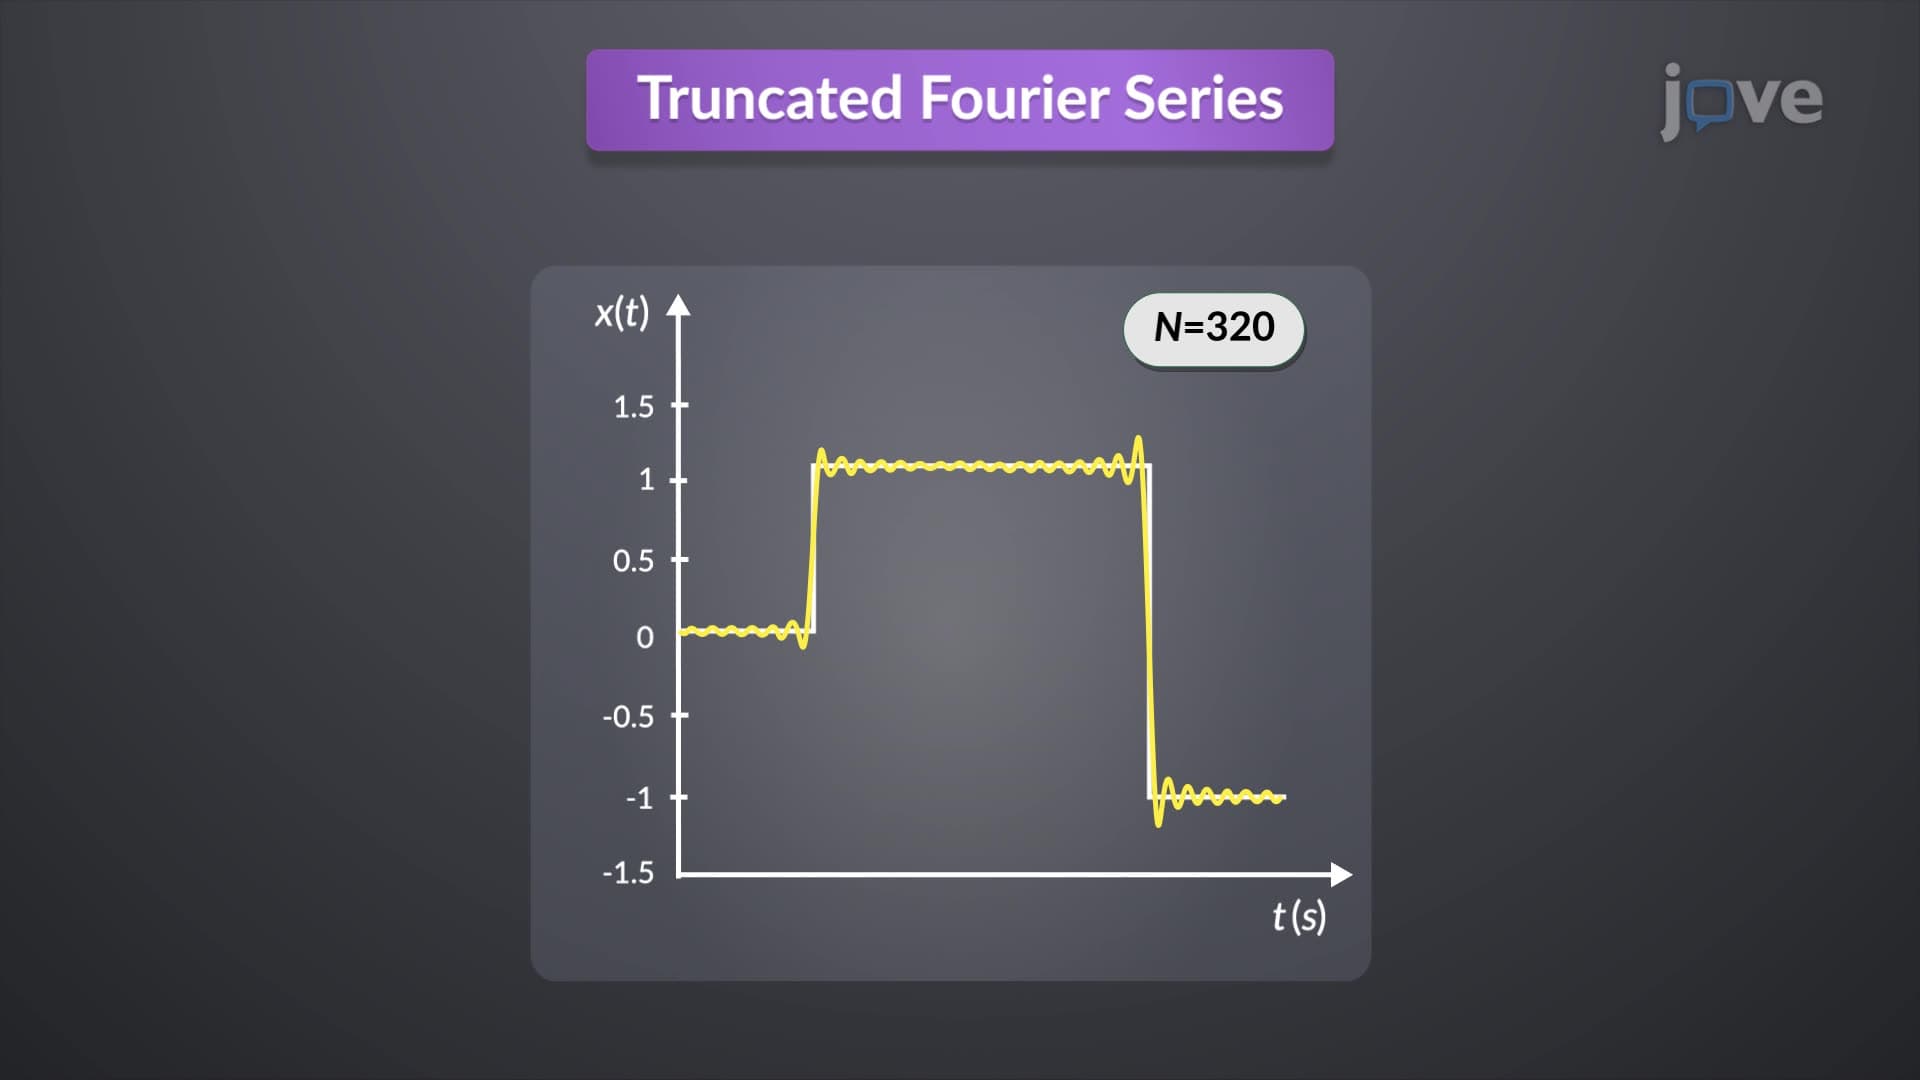
Convergence of Fourier Series
The Gibbs phenomenon refers to the persistent oscillations and overshoots that occur near discontinuities...
 01:15
One-Way ANOVA: Equal Sample Sizes
Different sample means can result in different values for the variance estimate: variance between samples. This is because the variance between samples is calculated as the product of the sample size and the variance between the...
 01:29
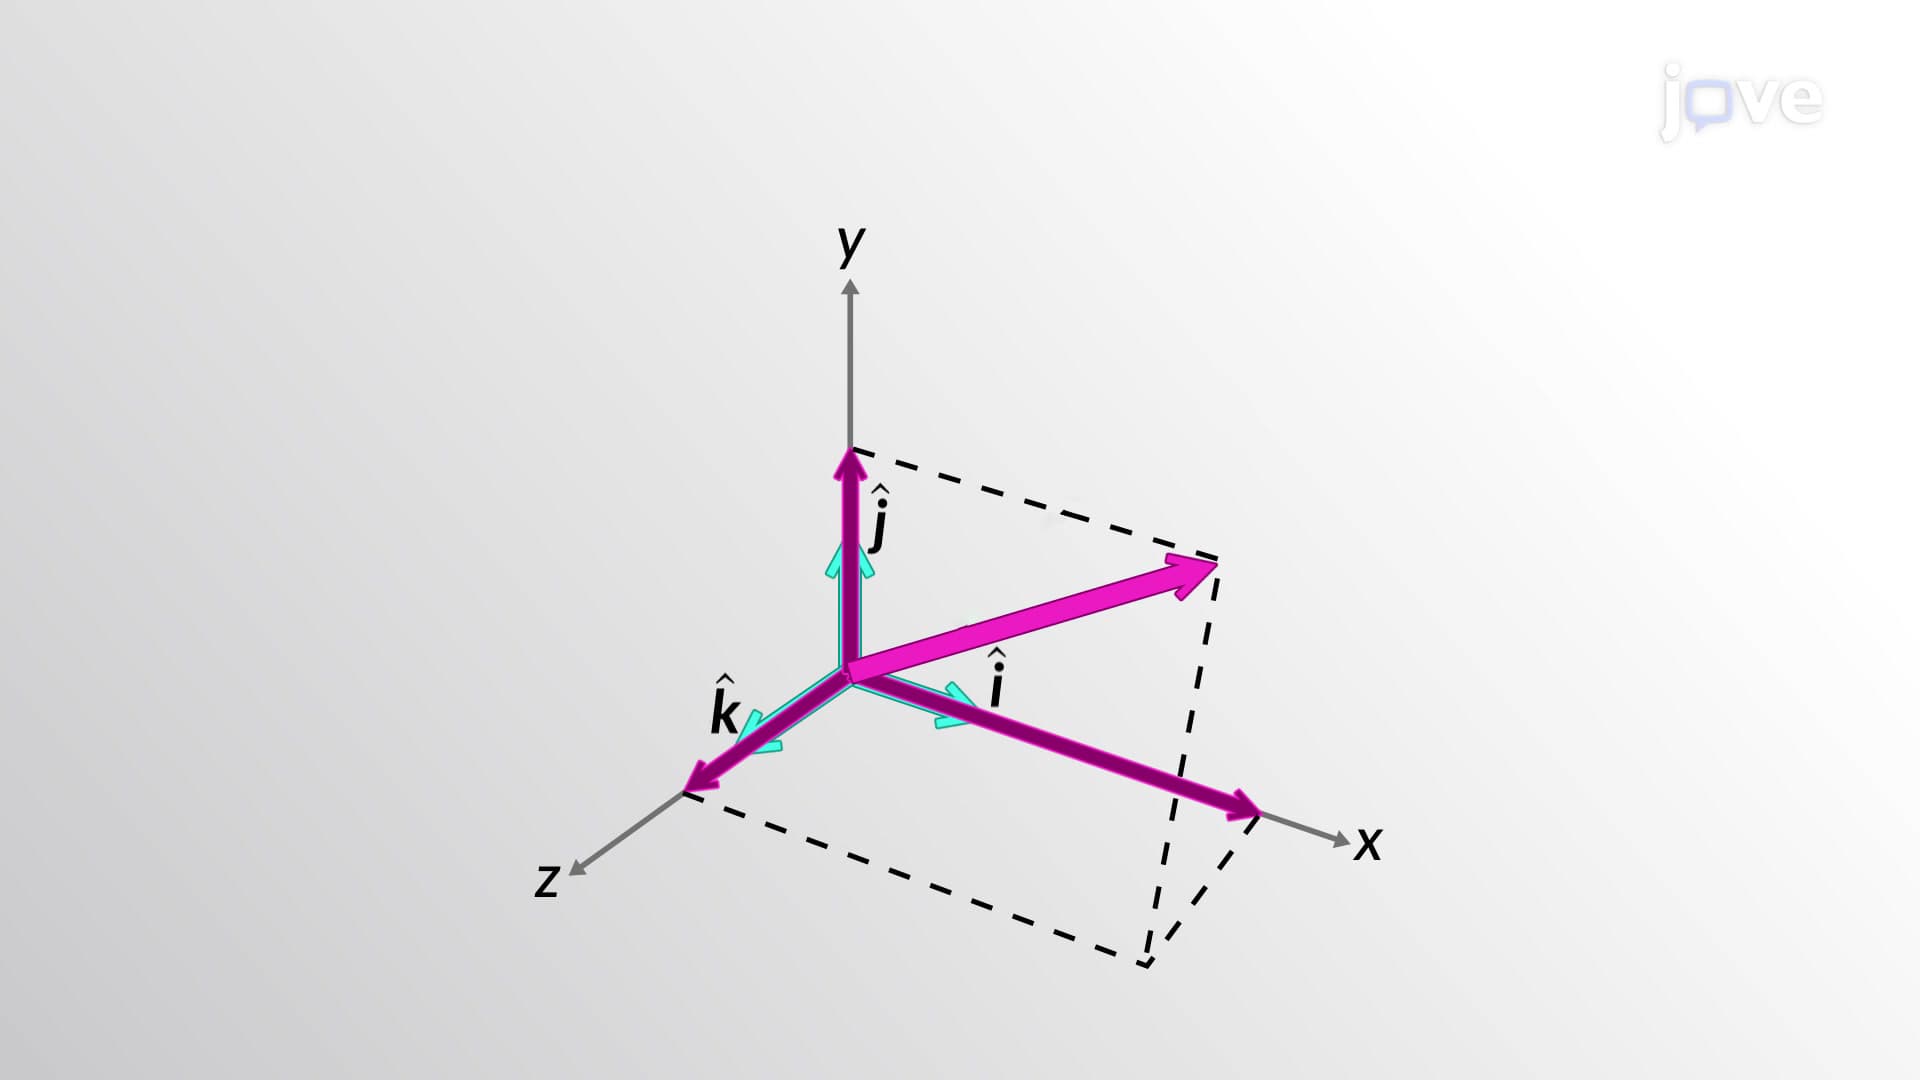
Vector Components in the Cartesian Coordinate System