Related Experiment Video
Updated: Apr 24, 2026
A Method of Trigonometric Modelling of Seasonal Variation Demonstrated with Multiple Sclerosis Relapse Data
Published on: December 9, 2015
Characteristics of the transmission of autoregressive sub-patterns in financial time series
Xiangyun Gao1, Haizhong An2, Wei Fang2
11] School of Humanities and Economic Management, China University of Geosciences, Beijing 100083, China [2] Key Laboratory of Carrying Capacity Assessment for Resource and Environment, Ministry of Land and Resources (Chinese Academy of Land and Resource Economics, China University of Geosciences Beijing), Beijing 100083, China [3] Lab of Resources and Environmental Management, China University of Geosciences, Beijing 100083, China [4] Department of Earth and Environmental Sciences, University of Waterloo, ON N2L 3G1, Canada.

Abstract:
There are many types of autoregressive patterns in financial time series, and they form a transmission process. Here, we define autoregressive patterns quantitatively through an econometrical regression model. We present a computational algorithm that sets the autoregressive patterns as nodes and transmissions between patterns as edges, and then converts the transmission process of autoregressive patterns in a time series into a network. We utilised daily Shanghai (securities) composite index time series to study the transmission characteristics of autoregressive patterns. We found statistically significant evidence that the financial market is not random and that there are similar characteristics between parts and whole time series. A few types of autoregressive sub-patterns and transmission patterns drive the oscillations of the financial market. A clustering effect on fluctuations appears in the transmission process, and certain non-major autoregressive sub-patterns have high media capabilities in the financial time series. Different stock indexes exhibit similar characteristics in the transmission of fluctuation information. This work not only proposes a distinctive perspective for analysing financial time series but also provides important information for investors.
Related Concept Videos
 01:20
Properties of Fourier series I
 01:25
First Derivative Test: Problem Solving
 01:16
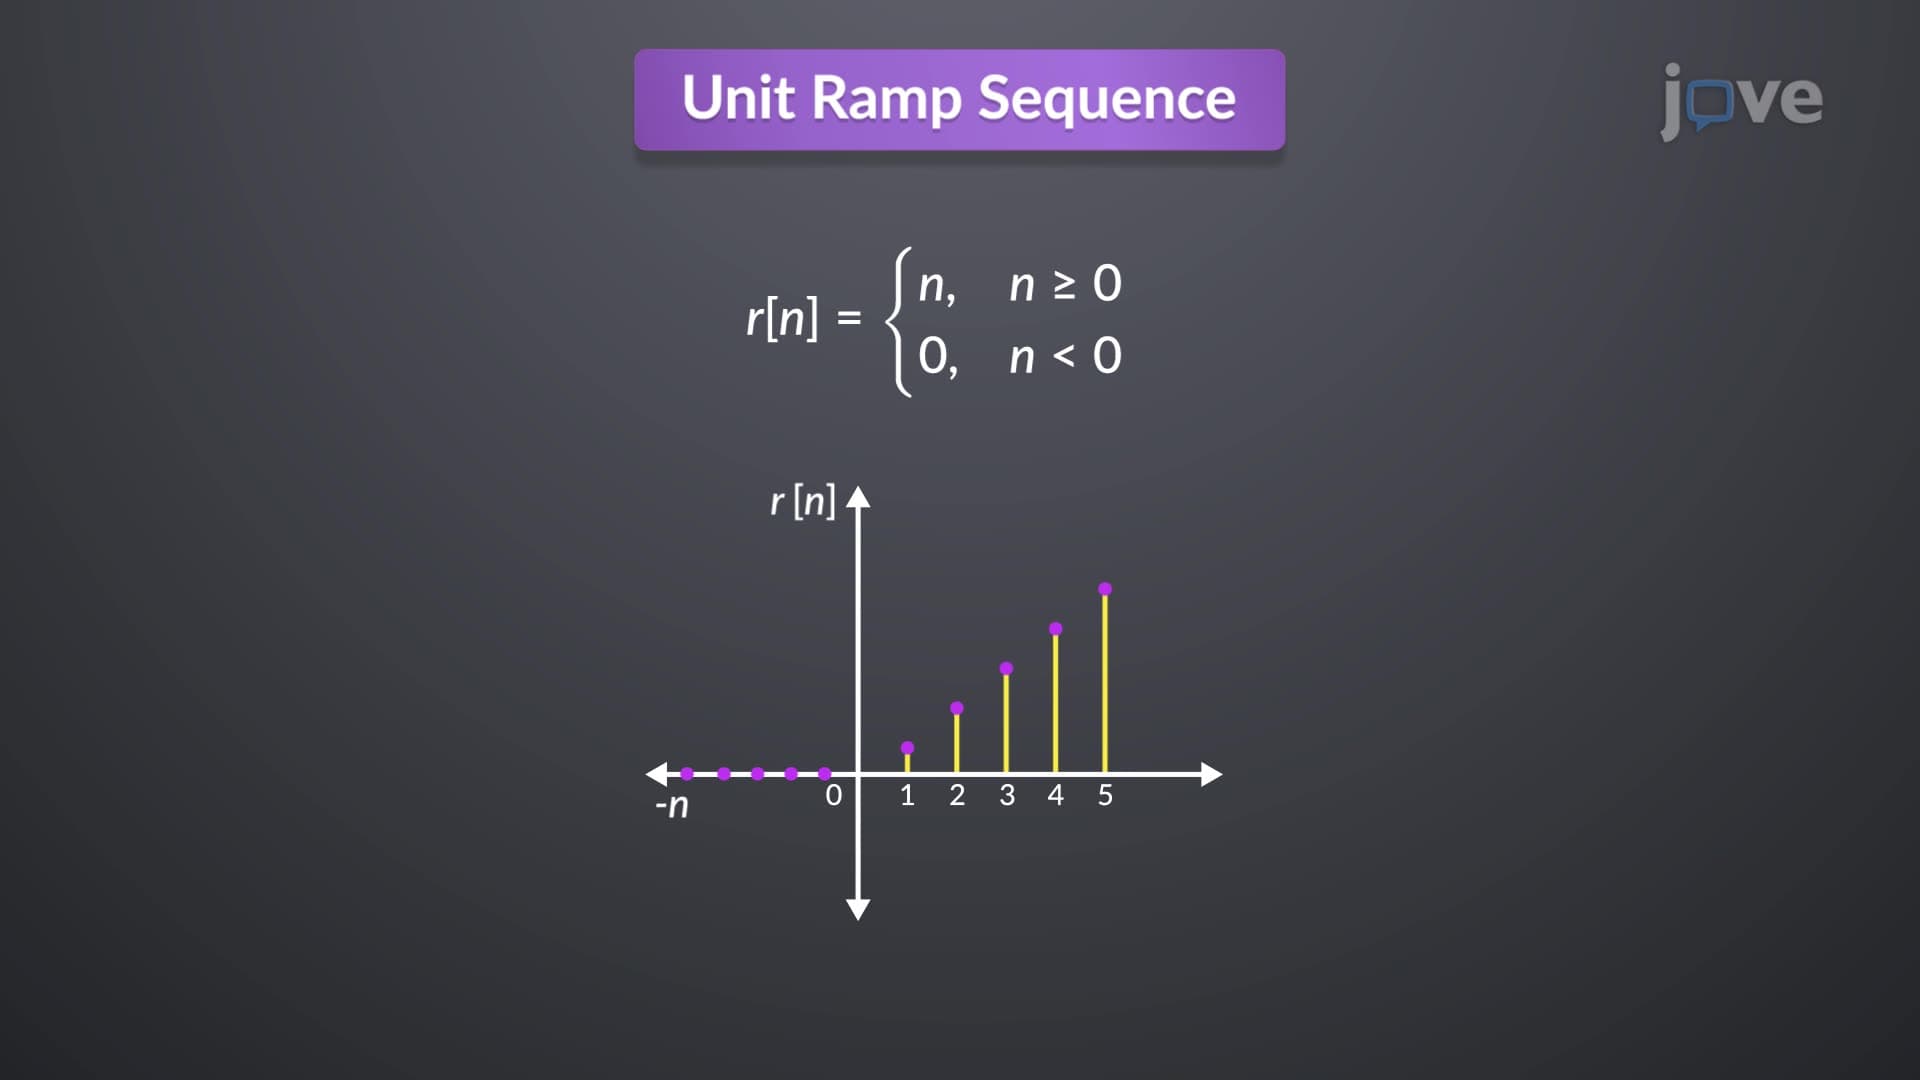
Basic Discrete Time Signals
The unit impulse or sample sequence is mathematically expressed as zero for all n values except at n=0, where it is one. The unit impulse sequence, denoted by δ(n), is the first difference of the unit step sequence, while the unit step sequence u(n) is...
 01:29
Econometric Views (EViews)
 01:23
Linear time-invariant Systems
The input-output behavior of an LTI system can be fully defined by its response to an impulsive excitation at its input. Once this impulse response is known, the system's reaction to any other input can be...
 01:30
Classification of Signals
A continuous-time signal holds a value at every instant in time, representing information seamlessly. In contrast, a discrete-time signal holds values only at specific moments, often denoted as x(n), where...