A methodology for stochastic analysis of share prices as Markov chains with finite states
Felix Okoe Mettle1, Enoch Nii Boi Quaye1, Ravenhill Adjetey Laryea2
1Department of Statistics, University of Ghana, Accra, Ghana.

Abstract:
Price volatilities make stock investments risky, leaving investors in critical position when uncertain decision is made. To improve investor evaluation confidence on exchange markets, while not using time series methodology, we specify equity price change as a stochastic process assumed to possess Markov dependency with respective state transition probabilities matrices following the identified state pace (i.e. decrease, stable or increase). We established that identified states communicate, and that the chains are aperiodic and ergodic thus possessing limiting distributions. We developed a methodology for determining expected mean return time for stock price increases and also establish criteria for improving investment decision based on highest transition probabilities, lowest mean return time and highest limiting distributions. We further developed an R algorithm for running the methodology introduced. The established methodology is applied to selected equities from Ghana Stock Exchange weekly trading data.
Related Concept Videos
 01:27
State Space Representation
Consider an RLC circuit, a...
 01:14
Probability in Statistics
An example of a simple event is a coin toss. The result of a coin toss is either a head or a tail. Here, head and tail are two simple events. These two simple events make up the sample space. Further, the probability of an event occurring falls within the range of 0 to 1. The probability of an...
 01:10
Entropy Change in Reversible Processes
The statement can be further generalized to prove that entropy is a state function. Take a cyclic process between any two points on a p-V diagram.
 00:56
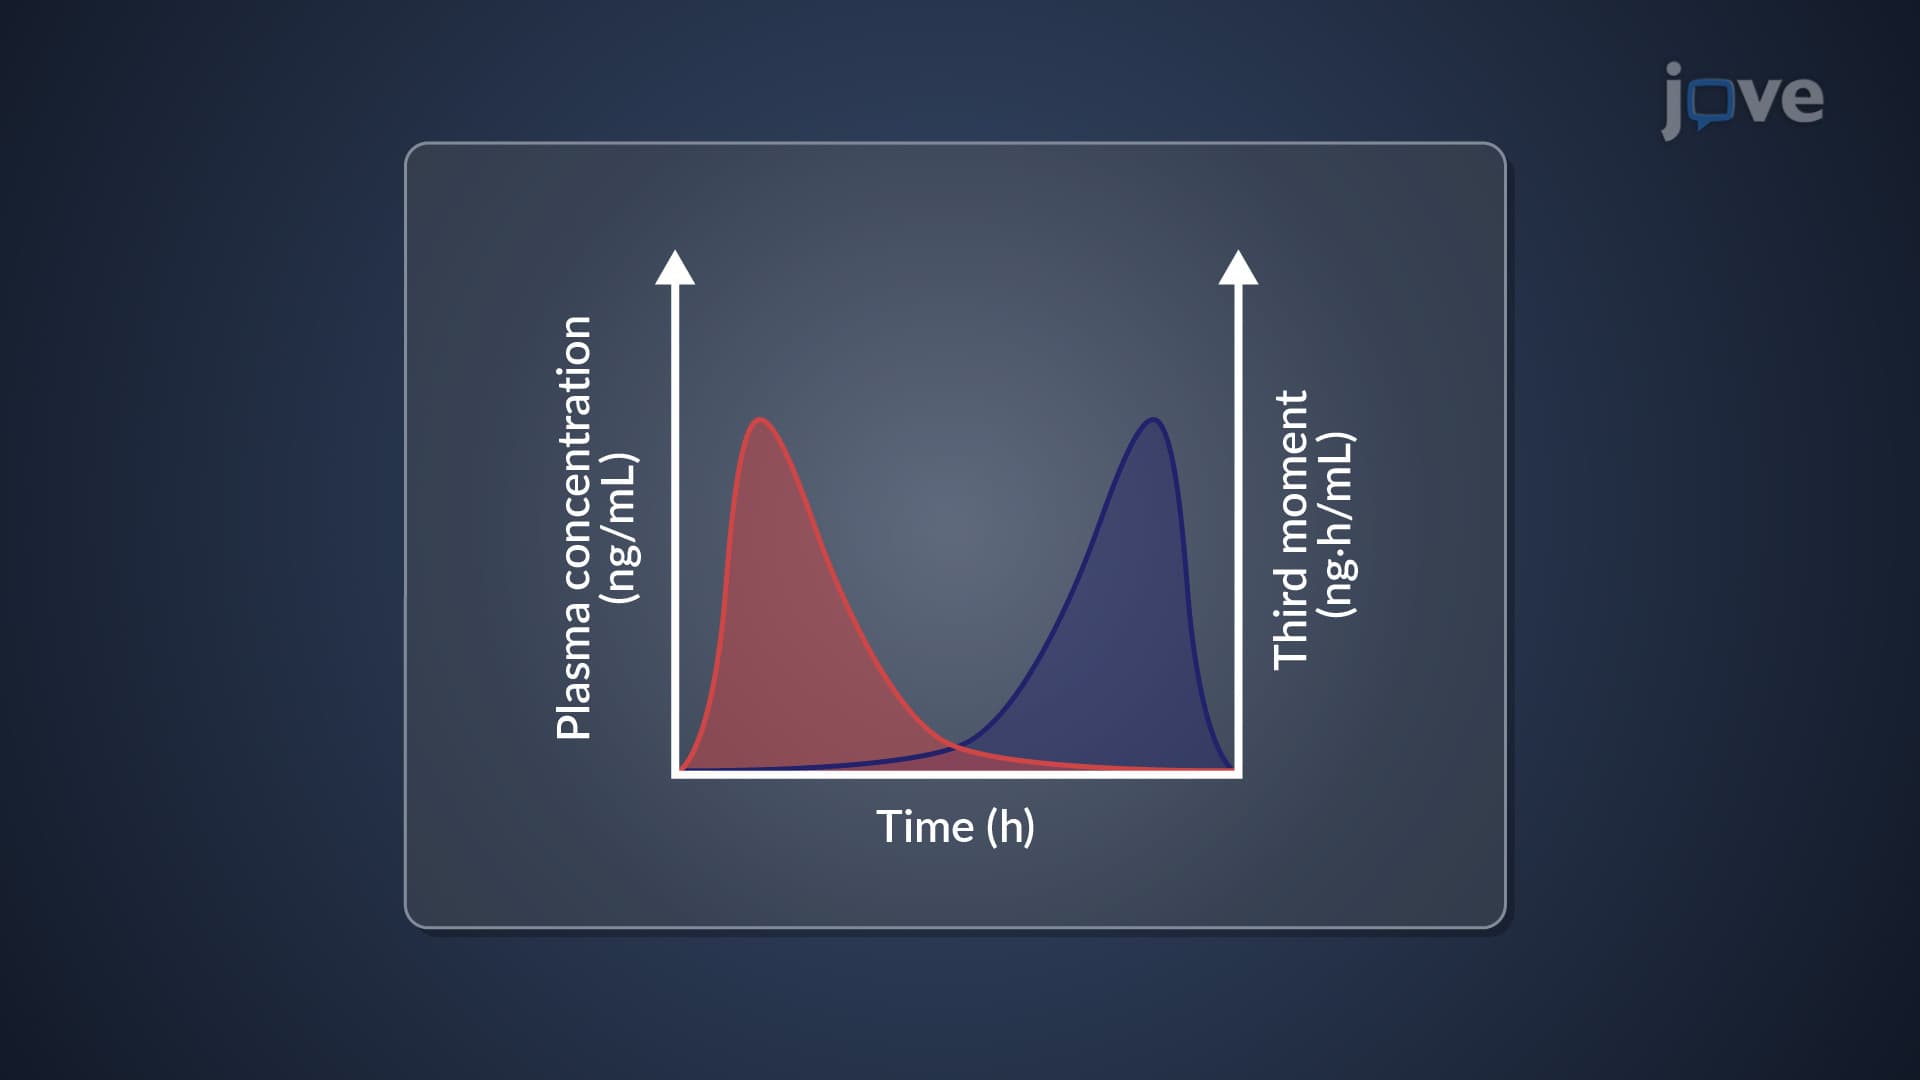
Noncompartmental Analysis: Statistical Moment Theory
 01:24
BIBO stability of continuous and discrete -time systems
To determine the BIBO stability, the convolution integral is utilized when a bounded continuous-time input is applied to a Linear Time-Invariant (LTI) system....
 01:32
Probability Distributions
A discrete probability distribution is a probability distribution of discrete random variables. It can be categorized into binomial probability distribution and Poisson...