Related Experiment Video
Updated: Apr 4, 2026


An R-Based Landscape Validation of a Competing Risk Model
Published on: September 16, 2022
Convexity of Ruin Probability and Optimal Dividend Strategies for a General Lévy Process
Chuancun Yin1, Kam Chuen Yuen2, Ying Shen1
1School of Mathematical Sciences, Qufu Normal University, Shandong 273165, China.

Abstract:
We consider the optimal dividends problem for a company whose cash reserves follow a general Lévy process with certain positive jumps and arbitrary negative jumps. The objective is to find a policy which maximizes the expected discounted dividends until the time of ruin. Under appropriate conditions, we use some recent results in the theory of potential analysis of subordinators to obtain the convexity properties of probability of ruin. We present conditions under which the optimal dividend strategy, among all admissible ones, takes the form of a barrier strategy.
More Related Videos

Related Concept Videos
 01:32
Probability Distributions
A discrete probability distribution is a probability distribution of discrete random variables. It can be categorized into binomial probability distribution and Poisson...
 01:09
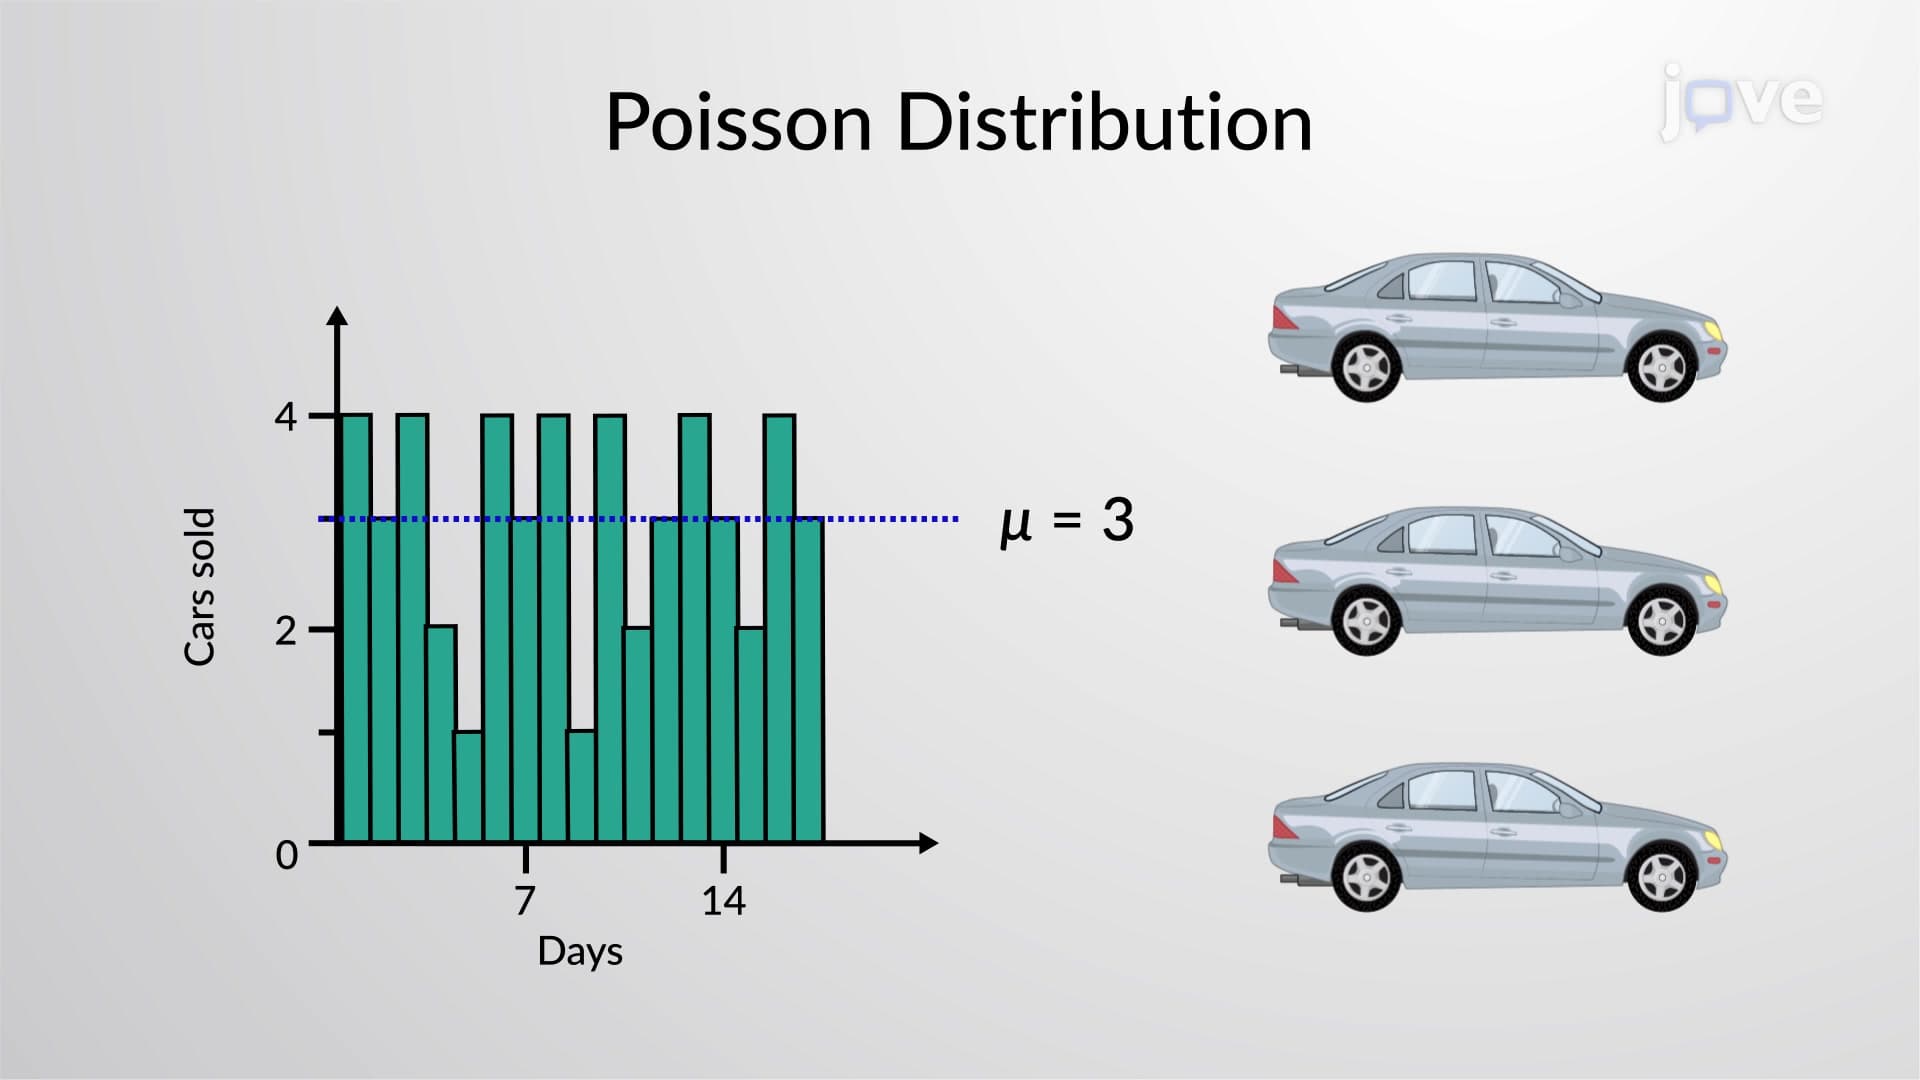
Poisson Probability Distribution
The...
 01:27
Indeterminate Forms and L’Hôpital’s Rule
 01:27
Applications of Integration to Probability Density Functions
 01:25
Poisson's And Laplace's Equation
 01:15
Binomial Probability Distribution
The outcomes of a binomial experiment fit a binomial probability distribution. A statistical experiment can be classified as a binomial experiment if the following conditions are met:
There are a fixed number of trials. Think of trials as repetitions of an experiment. The letter n denotes the number of trials.
There are only two possible outcomes,...