Related Experiment Video
Updated: Mar 29, 2026

An Analog Macroscopic Technique for Studying Molecular Hydrodynamic Processes in Dense Gases and Liquids
Published on: December 4, 2017
Maximum of a Fractional Brownian Motion: Analytic Results from Perturbation Theory
Mathieu Delorme1, Kay Jörg Wiese1
1CNRS-Laboratoire de Physique Théorique de l'Ecole Normale Supérieure, 24 rue Lhomond, 75005 Paris, France.

Abstract:
Fractional Brownian motion is a non-Markovian Gaussian process X_{t}, indexed by the Hurst exponent H. It generalizes standard Brownian motion (corresponding to H=1/2). We study the probability distribution of the maximum m of the process and the time t_{max} at which the maximum is reached. They are encoded in a path integral, which we evaluate perturbatively around a Brownian, setting H=1/2+ϵ. This allows us to derive analytic results beyond the scaling exponents. Extensive numerical simulations for different values of H test these analytical predictions and show excellent agreement, even for large ϵ.
Related Concept Videos
 04:08
The Uncertainty Principle
 01:20
Maxwell-Boltzmann Distribution: Problem Solving
This distribution function f(v) is defined by saying that the expected number N (v1,v2) of particles with speeds between v1 and v2 is given by
 02:32
The de Broglie Wavelength
 01:22
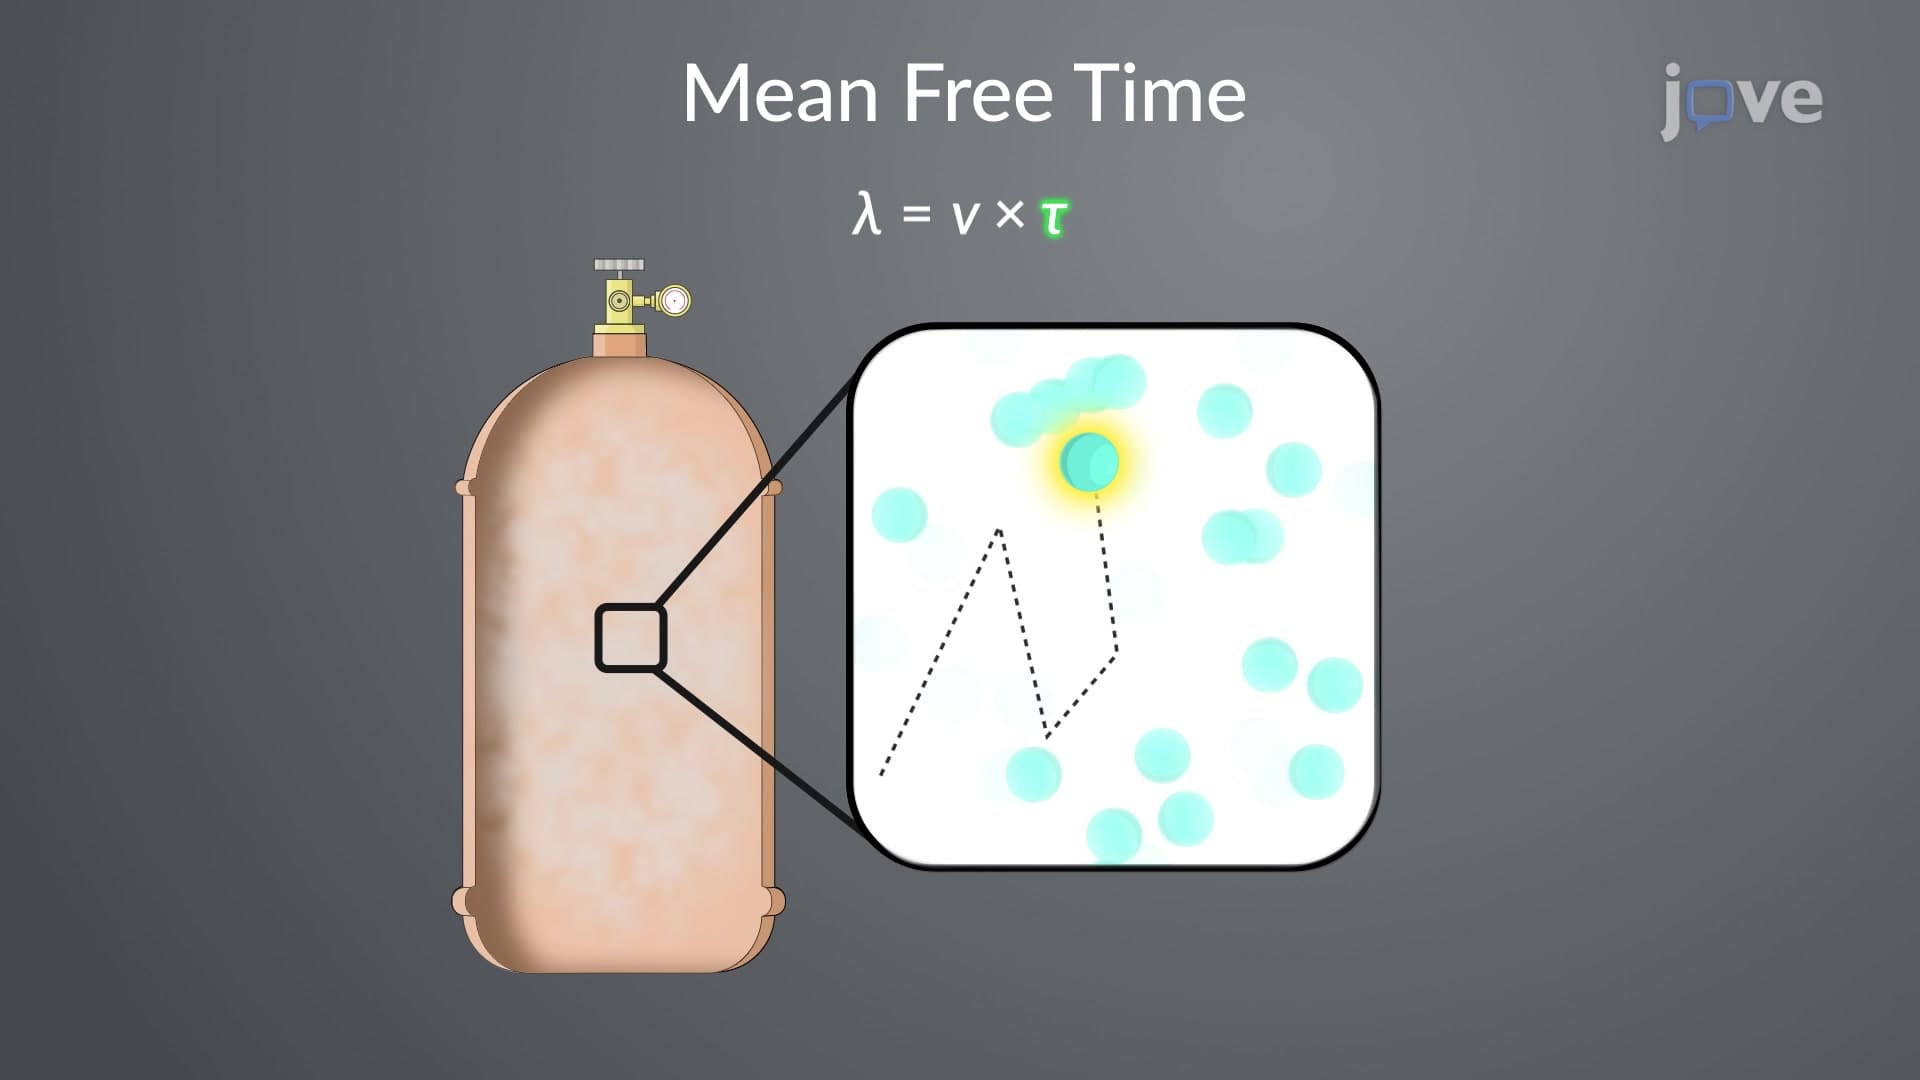
Mean free path and Mean free time
 01:21
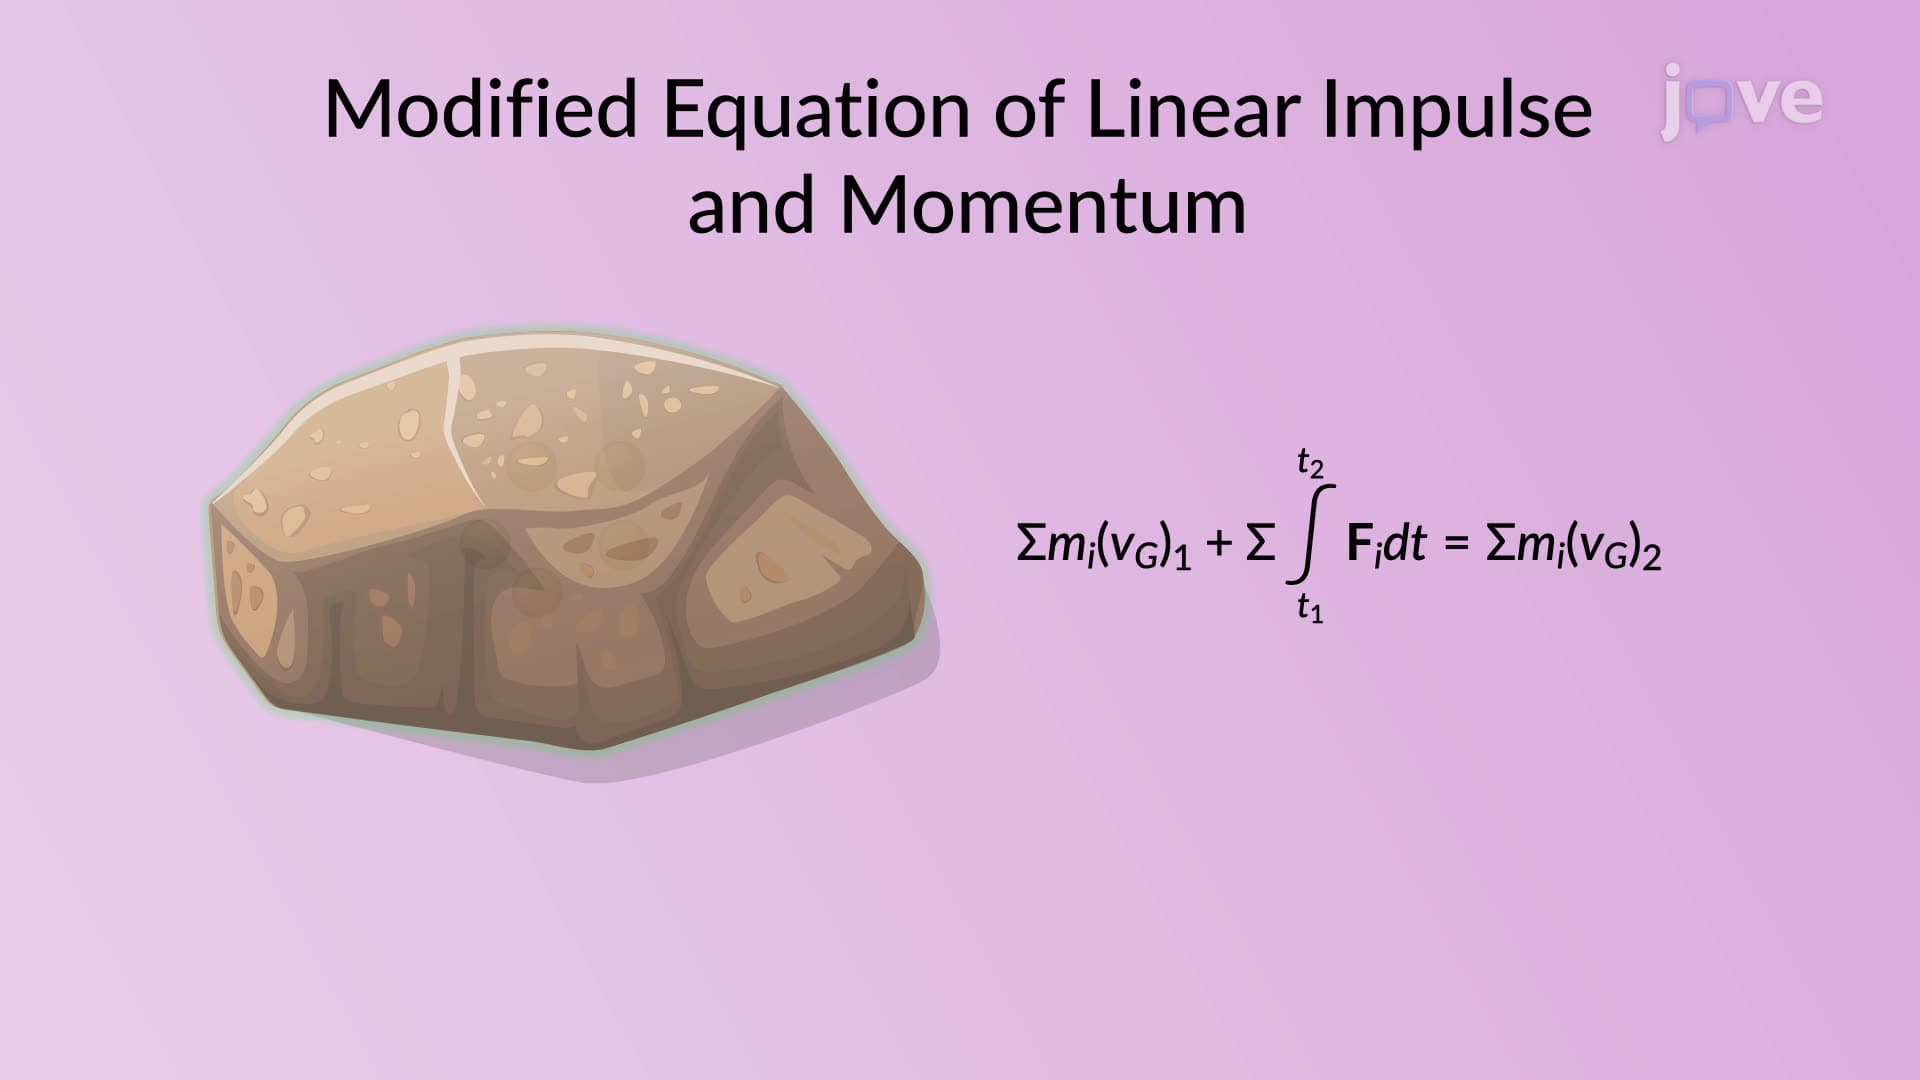
Principle of Linear Impulse and Momentum for a System of Particles
Notably, internal forces between particles, occurring in equal and opposite collinear pairs, cancel out and are not part of the equation of motion. This exclusion simplifies the...
 01:16
Perpendicular-Axis Theorem
Consider a circular disc of mass M and radius R lying along an x-y plane. The origin lies at the center of the disc, and the z-axis is perpendicular to the disc's plane. All three axes coincide at the disc's center. The moment of inertia of this...