Related Experiment Video
Updated: Mar 24, 2026
An R-Based Landscape Validation of a Competing Risk Model
Published on: September 16, 2022
Empirical extensions of the lasso penalty to reduce the false discovery rate in high-dimensional Cox regression
Nils Ternès1,2, Federico Rotolo1,2, Stefan Michiels1,2
1Université Paris-Saclay, Univ. Paris-Sud, UVSQ, CESP, INSERM, F-94805, Villejuif, France.

Abstract:
Correct selection of prognostic biomarkers among multiple candidates is becoming increasingly challenging as the dimensionality of biological data becomes higher. Therefore, minimizing the false discovery rate (FDR) is of primary importance, while a low false negative rate (FNR) is a complementary measure. The lasso is a popular selection method in Cox regression, but its results depend heavily on the penalty parameter λ. Usually, λ is chosen using maximum cross-validated log-likelihood (max-cvl). However, this method has often a very high FDR. We review methods for a more conservative choice of λ. We propose an empirical extension of the cvl by adding a penalization term, which trades off between the goodness-of-fit and the parsimony of the model, leading to the selection of fewer biomarkers and, as we show, to the reduction of the FDR without large increase in FNR. We conducted a simulation study considering null and moderately sparse alternative scenarios and compared our approach with the standard lasso and 10 other competitors: Akaike information criterion (AIC), corrected AIC, Bayesian information criterion (BIC), extended BIC, Hannan and Quinn information criterion (HQIC), risk information criterion (RIC), one-standard-error rule, adaptive lasso, stability selection, and percentile lasso. Our extension achieved the best compromise across all the scenarios between a reduction of the FDR and a limited raise of the FNR, followed by the AIC, the RIC, and the adaptive lasso, which performed well in some settings. We illustrate the methods using gene expression data of 523 breast cancer patients. In conclusion, we propose to apply our extension to the lasso whenever a stringent FDR with a limited FNR is targeted. Copyright © 2016 John Wiley & Sons, Ltd.

Related Concept Videos
 01:19
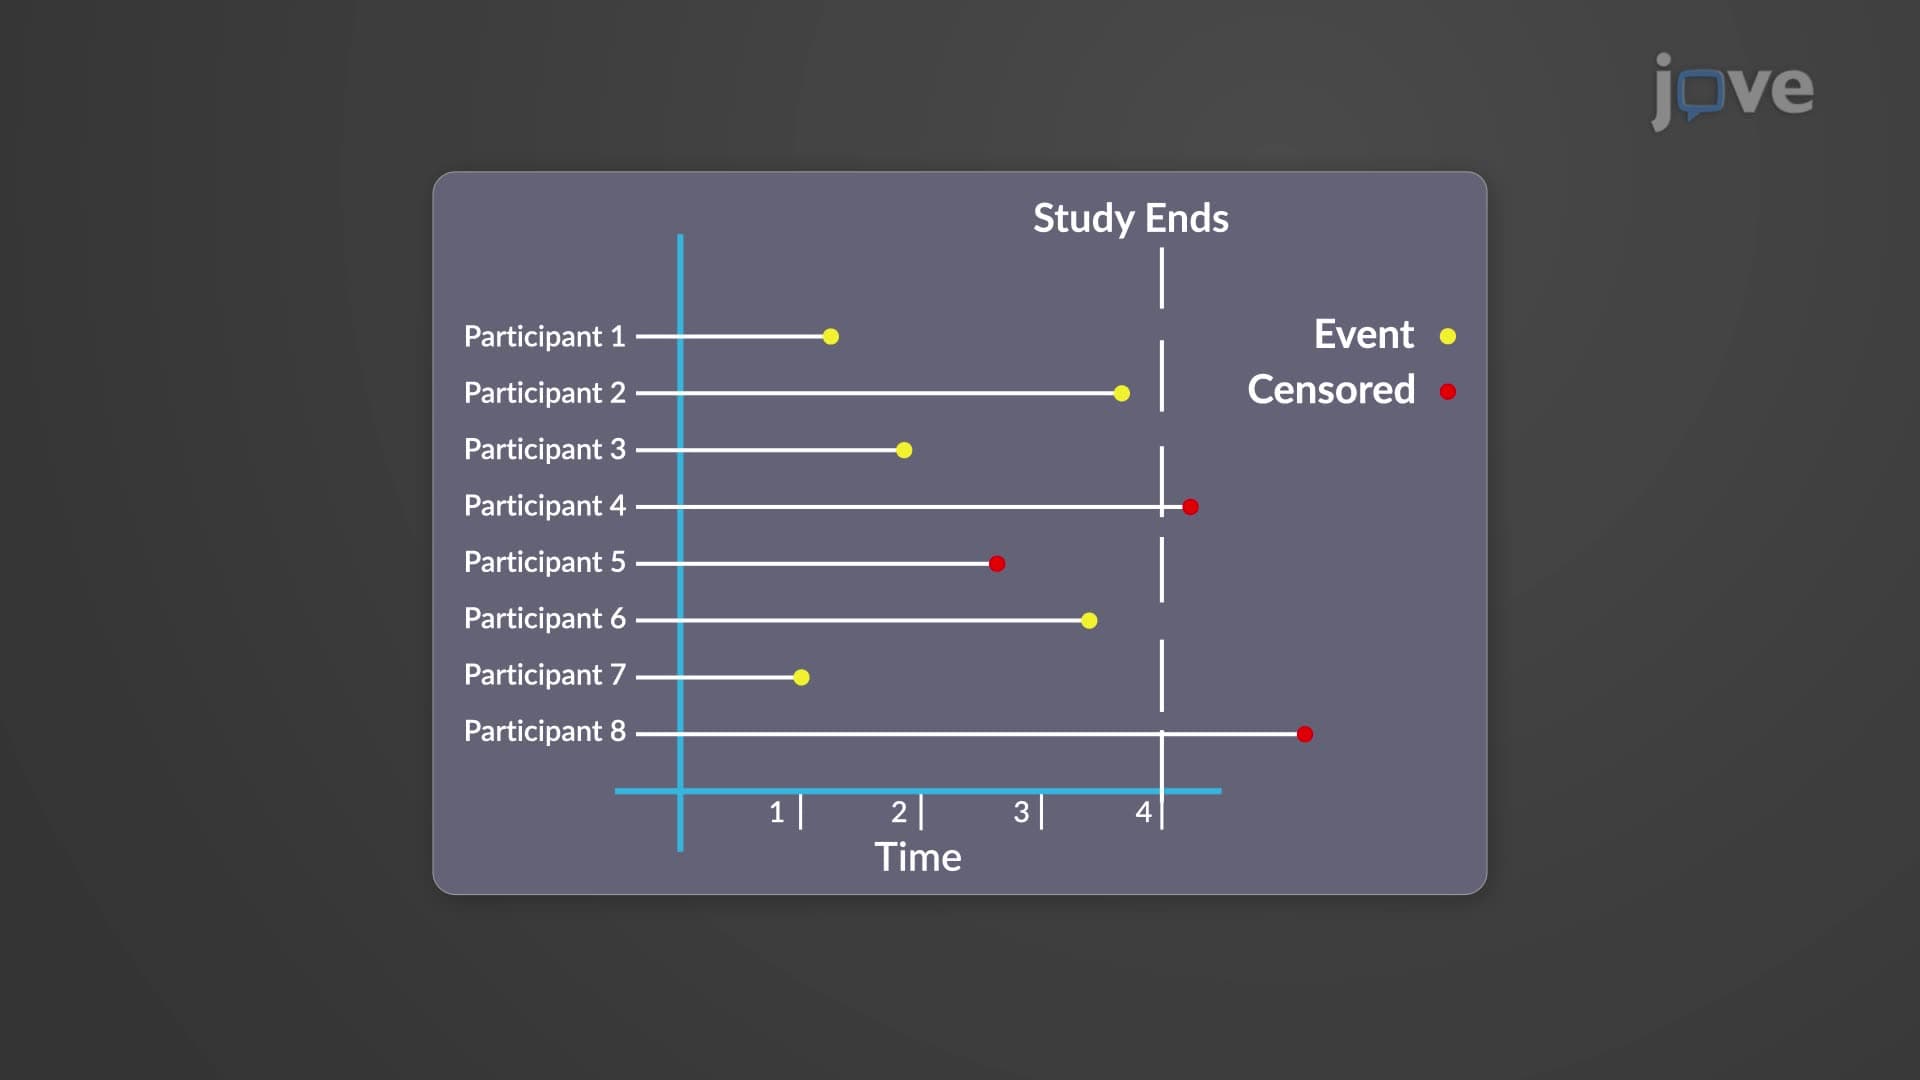
The Mantel-Cox Log-Rank Test
 01:03
Prediction Intervals
However, the point estimate is most likely not the exact value of the population parameter, but close to it. After calculating point estimates, we construct interval estimates, called confidence intervals or prediction intervals. This prediction interval comprises a range of values unlike the point estimate and is a better predictor of the observed sample value, y.
 01:23
Quadratic Models
 01:52
Regression Toward the Mean
 01:25
Multiple Regression
Farmers can use multiple regression to determine the crop yield based on more than one factor, such as water availability, fertilizer, soil properties, etc. Here, the crop yield is the response or dependent variable as it depends on the other independent variables. The analysis requires the construction of a scatter plot...
 01:11
Regression Analysis
In regression analysis, a regression equation is determined based on the line of best fit– a line that best fits the data points plotted in a graph. This line is also called the regression line. The algebraic equation for the regression line is called the regression equation. It is represented as: