Oracle estimation of parametric models under boundary constraints
Related Experiment Video
Updated: Mar 22, 2026
Precision Measurements and Parametric Models of Vertebral Endplates
Published on: September 17, 2019
Kin Yau Wong1, Yair Goldberg2, Jason P Fine1
1Department of Biostatistics, University of North Carolina, Chapel Hill, North Carolina 27599, U.S.A.

Abstract:
In many classical estimation problems, the parameter space has a boundary. In most cases, the standard asymptotic properties of the estimator do not hold when some of the underlying true parameters lie on the boundary. However, without knowledge of the true parameter values, confidence intervals constructed assuming that the parameters lie in the interior are generally over-conservative. A penalized estimation method is proposed in this article to address this issue. An adaptive lasso procedure is employed to shrink the parameters to the boundary, yielding oracle inference which adapt to whether or not the true parameters are on the boundary. When the true parameters are on the boundary, the inference is equivalent to that which would be achieved with a priori knowledge of the boundary, while if the converse is true, the inference is equivalent to that which is obtained in the interior of the parameter space. The method is demonstrated under two practical scenarios, namely the frailty survival model and linear regression with order-restricted parameters. Simulation studies and real data analyses show that the method performs well with realistic sample sizes and exhibits certain advantages over standard methods.

Related Concept Videos
 01:14
Parametric Survival Analysis: Weibull and Exponential Methods
Weibull Distribution
The Weibull distribution is a flexible model used in parametric survival analysis. It can handle both increasing and decreasing hazard rates, depending on its shape parameter...
 01:26
Area Problem
 01:26
Areas Within Irregular Boundaries
 01:05
Estimation of the Physical Quantities
 01:25
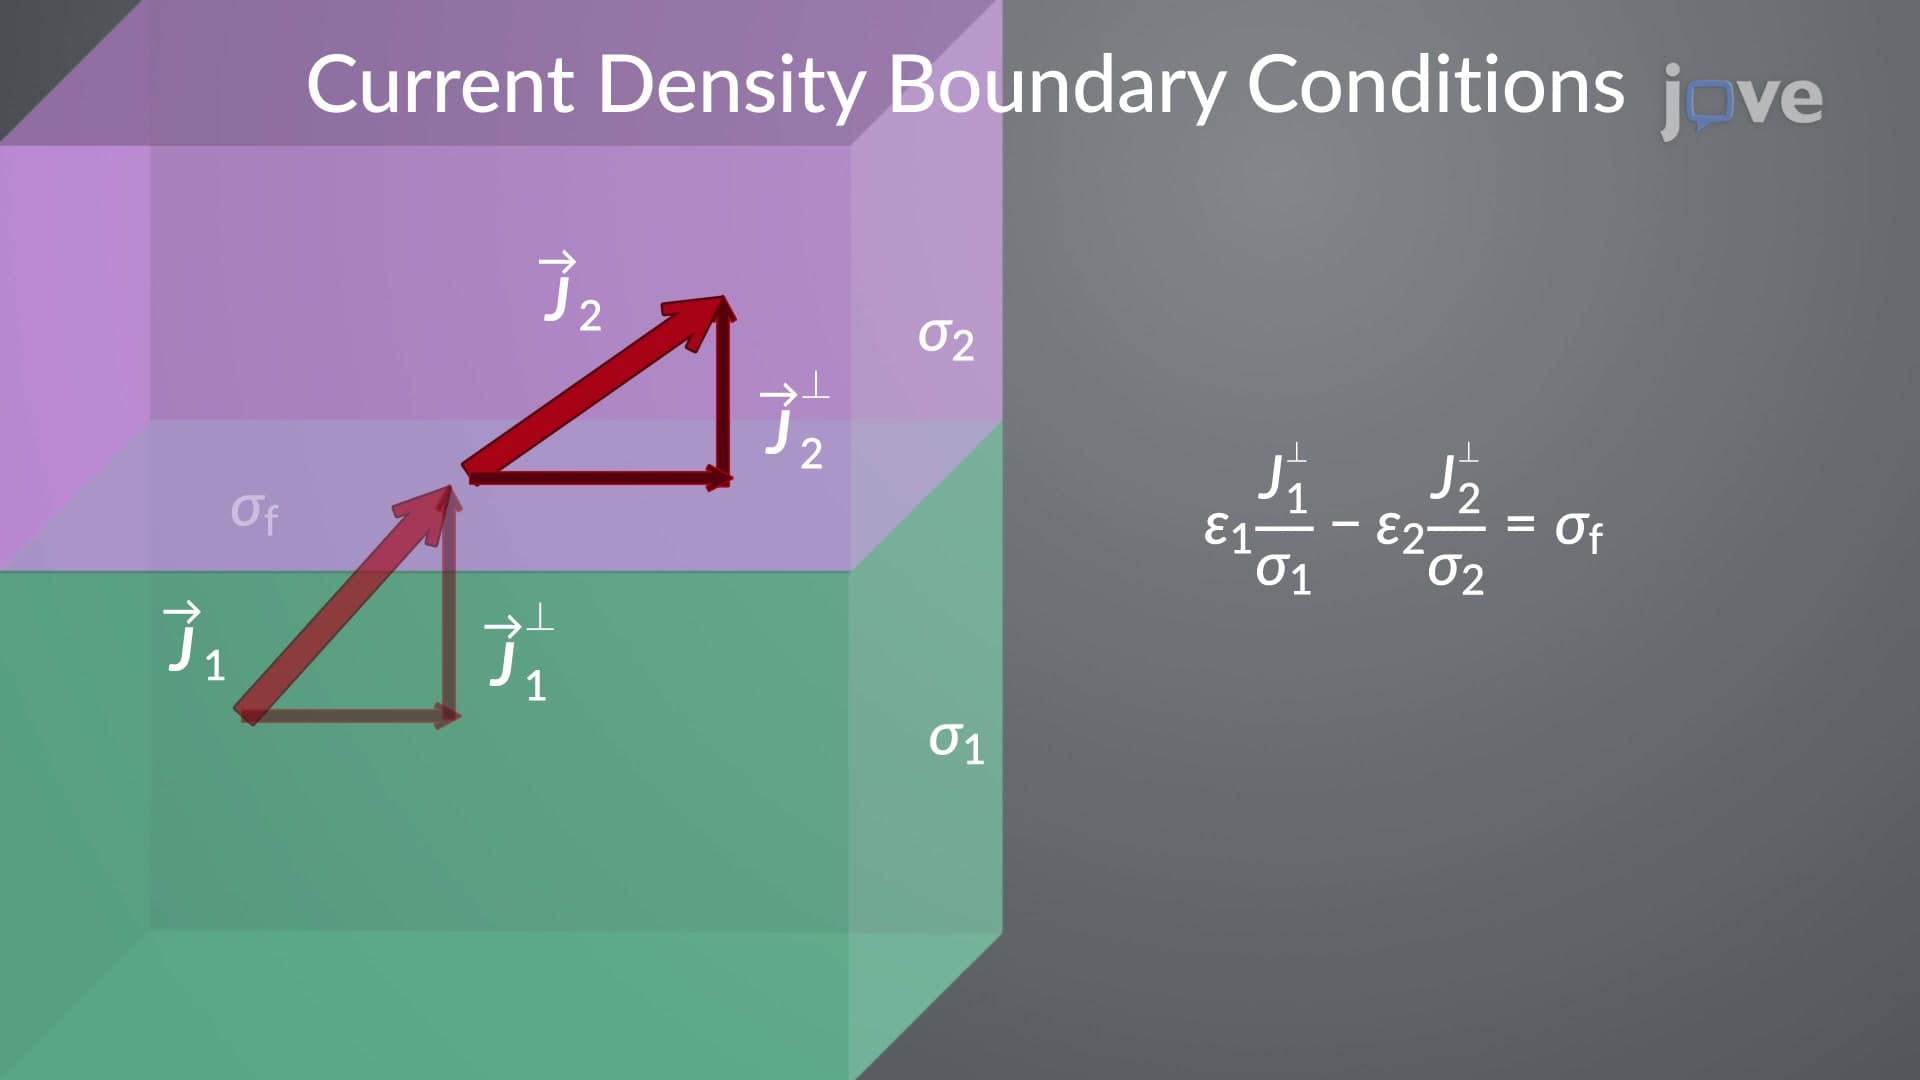
Boundary Conditions for Current Density
 01:03
Prediction Intervals
However, the point estimate is most likely not the exact value of the population parameter, but close to it. After calculating point estimates, we construct interval estimates, called confidence intervals or prediction intervals. This prediction interval comprises a range of values unlike the point estimate and is a better predictor of the observed sample value, y.