Related Experiment Video
Updated: Mar 18, 2026
An R-Based Landscape Validation of a Competing Risk Model
Published on: September 16, 2022
The Asymptotics of Recovery Probability in the Dual Renewal Risk Model with Constant Interest and Debit Force

Abstract:
The asymptotic behavior of the recovery probability for the dual renewal risk model with constant interest and debit force is studied. By means the idea of Markov Skeleton method, we studied the times that the random premium incomes happened and transformed the continuous time model into a discrete time model. By investigating the fluctuations of this discrete time model, we obtained the asymptotic behavior when the random premium income belongs to a kind of heavy-tailed distributions.
Related Concept Videos
 01:14
Parametric Survival Analysis: Weibull and Exponential Methods
Weibull Distribution
The Weibull distribution is a flexible model used in parametric survival analysis. It can handle both increasing and decreasing hazard rates, depending on its shape parameter...
 01:26
Exponential Equations for Modeling Growth
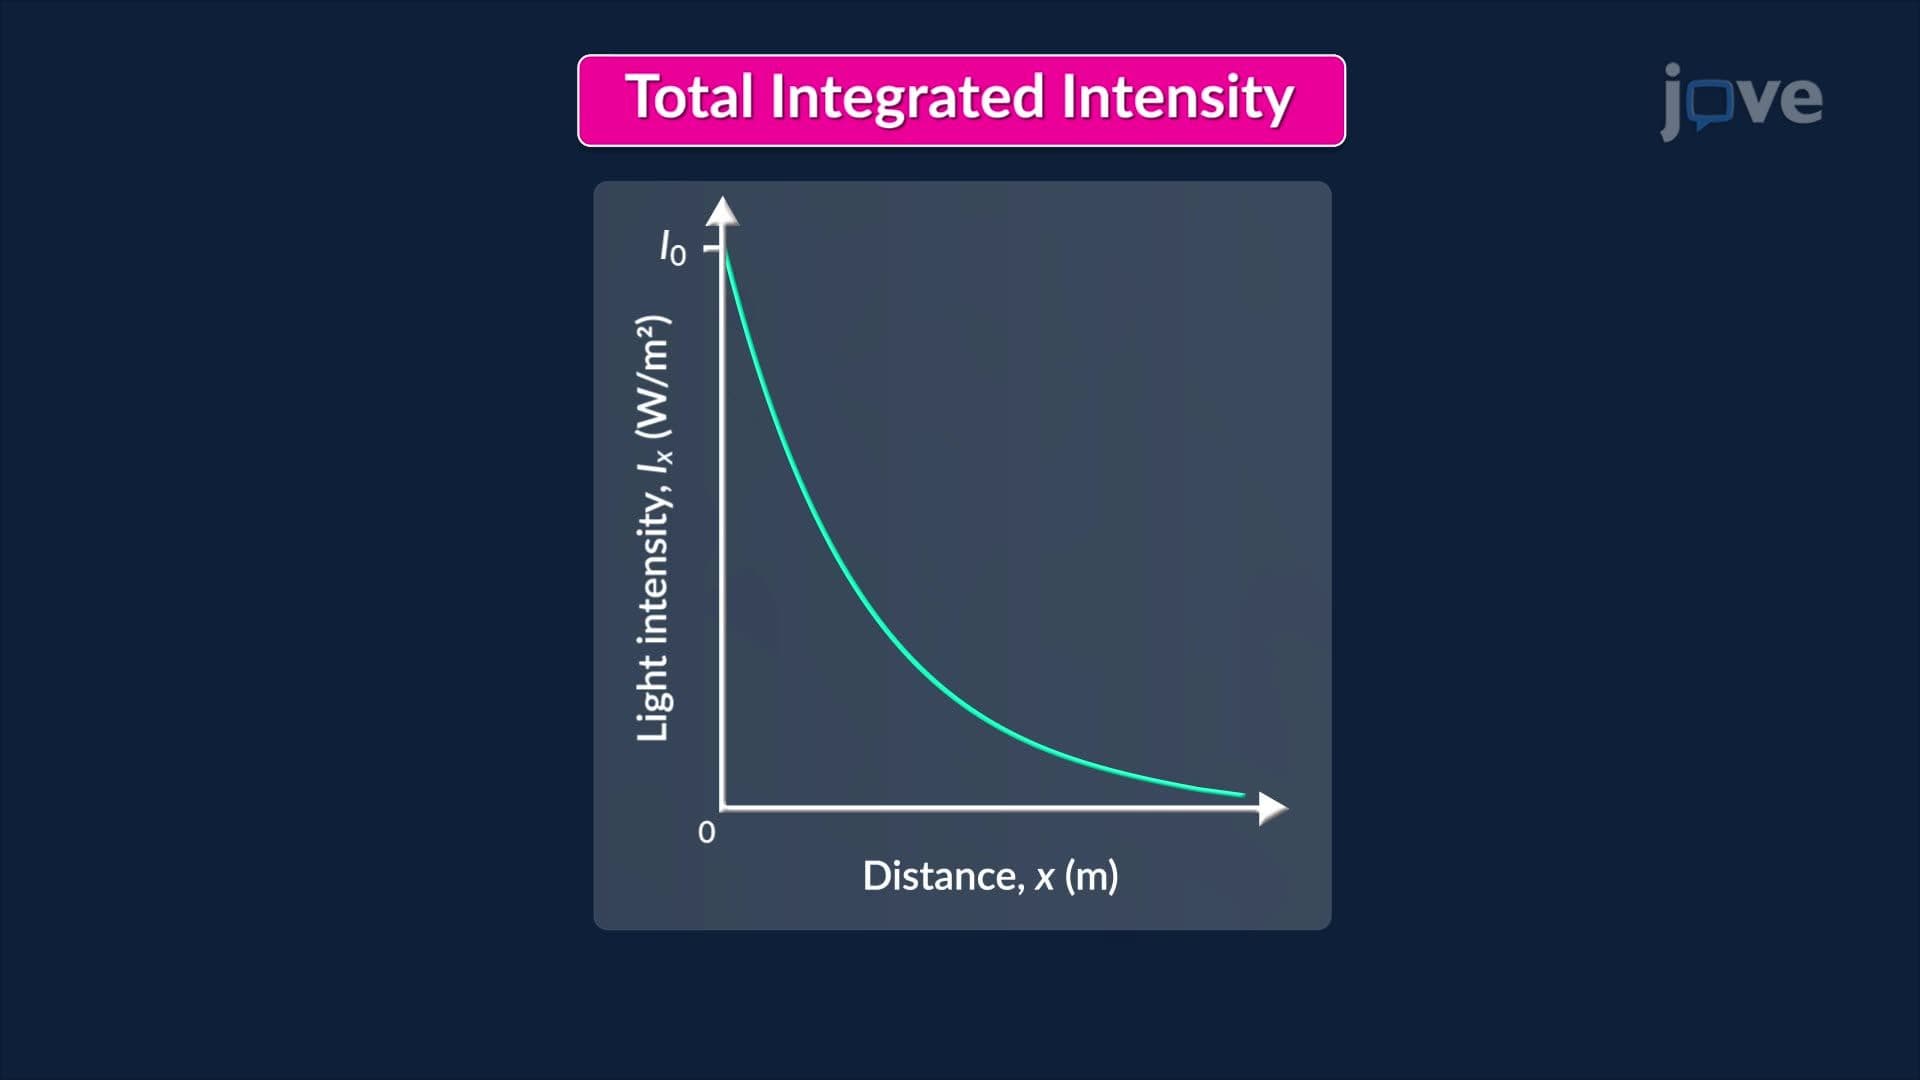 01:29
Improper Integrals: Infinite Intervals
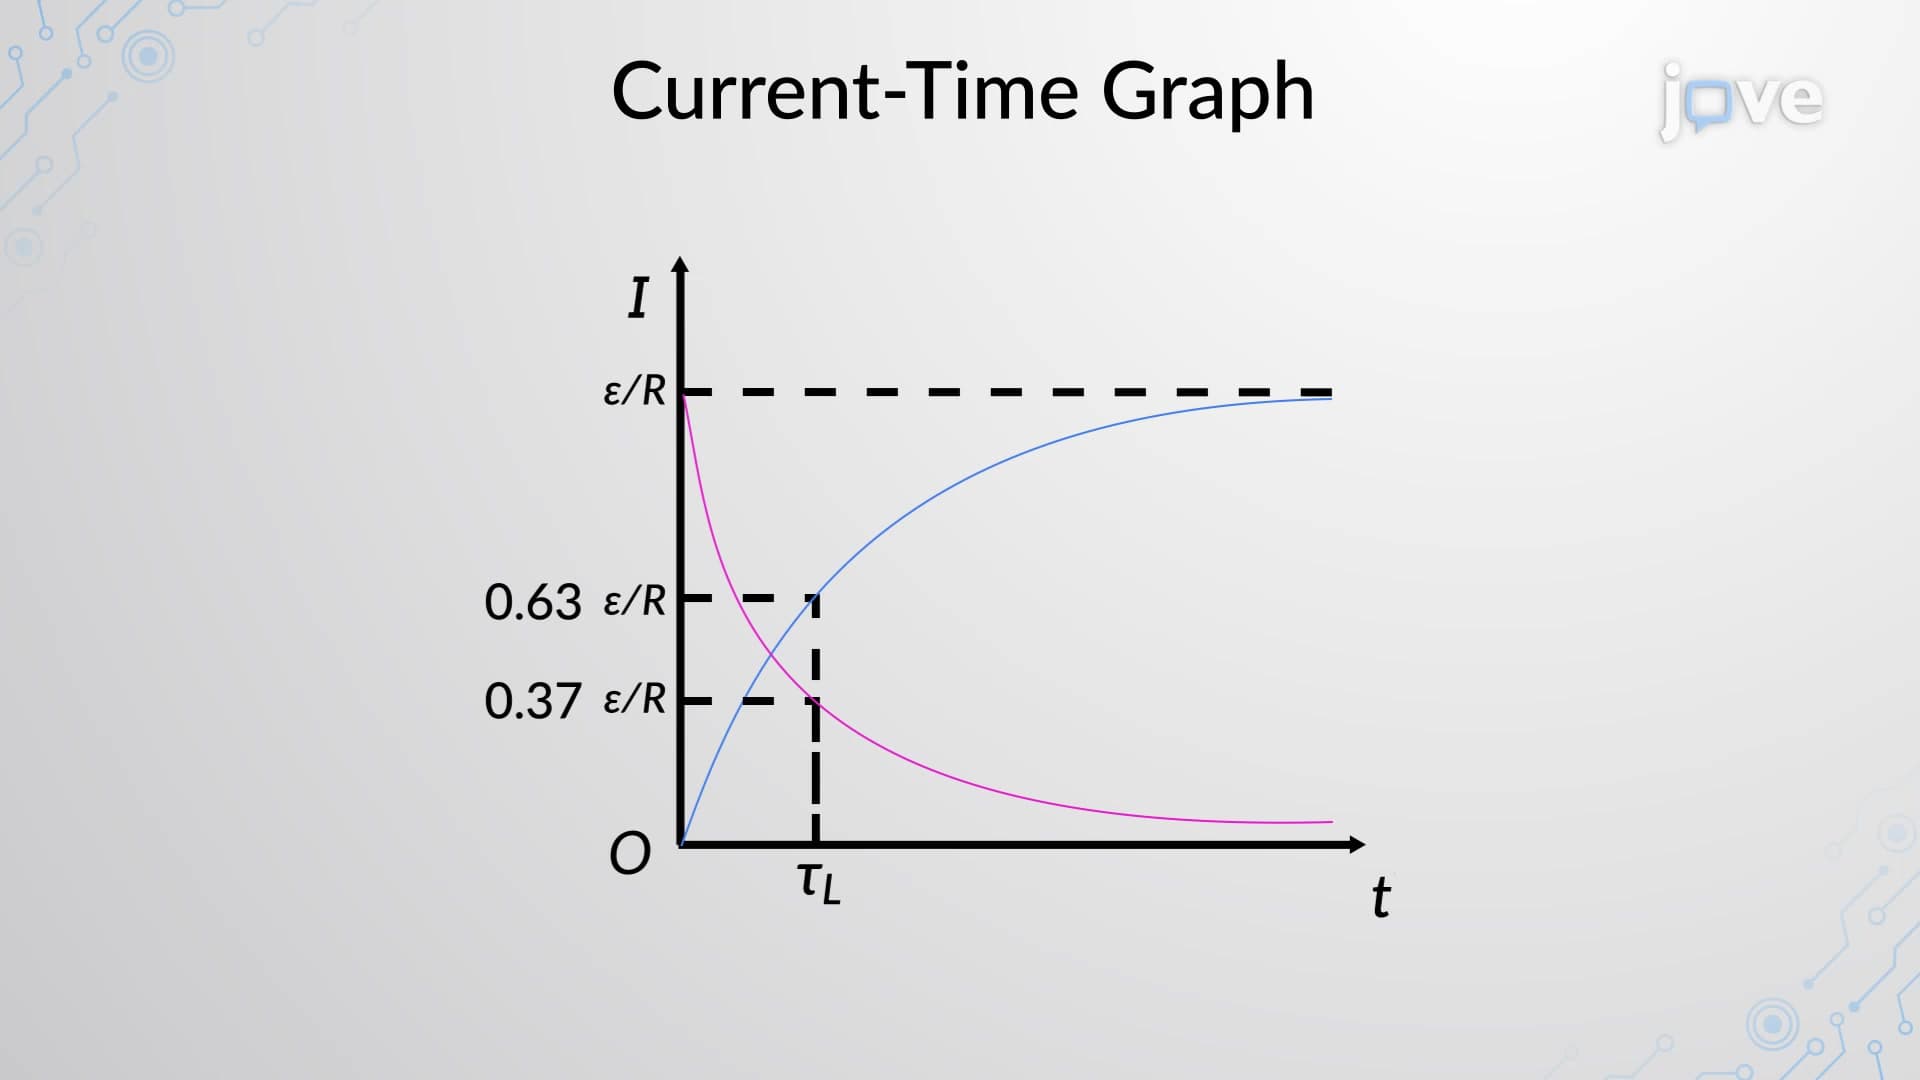 01:30
Current Growth And Decay In RL Circuits
 01:19
Routh-Hurwitz Criterion II
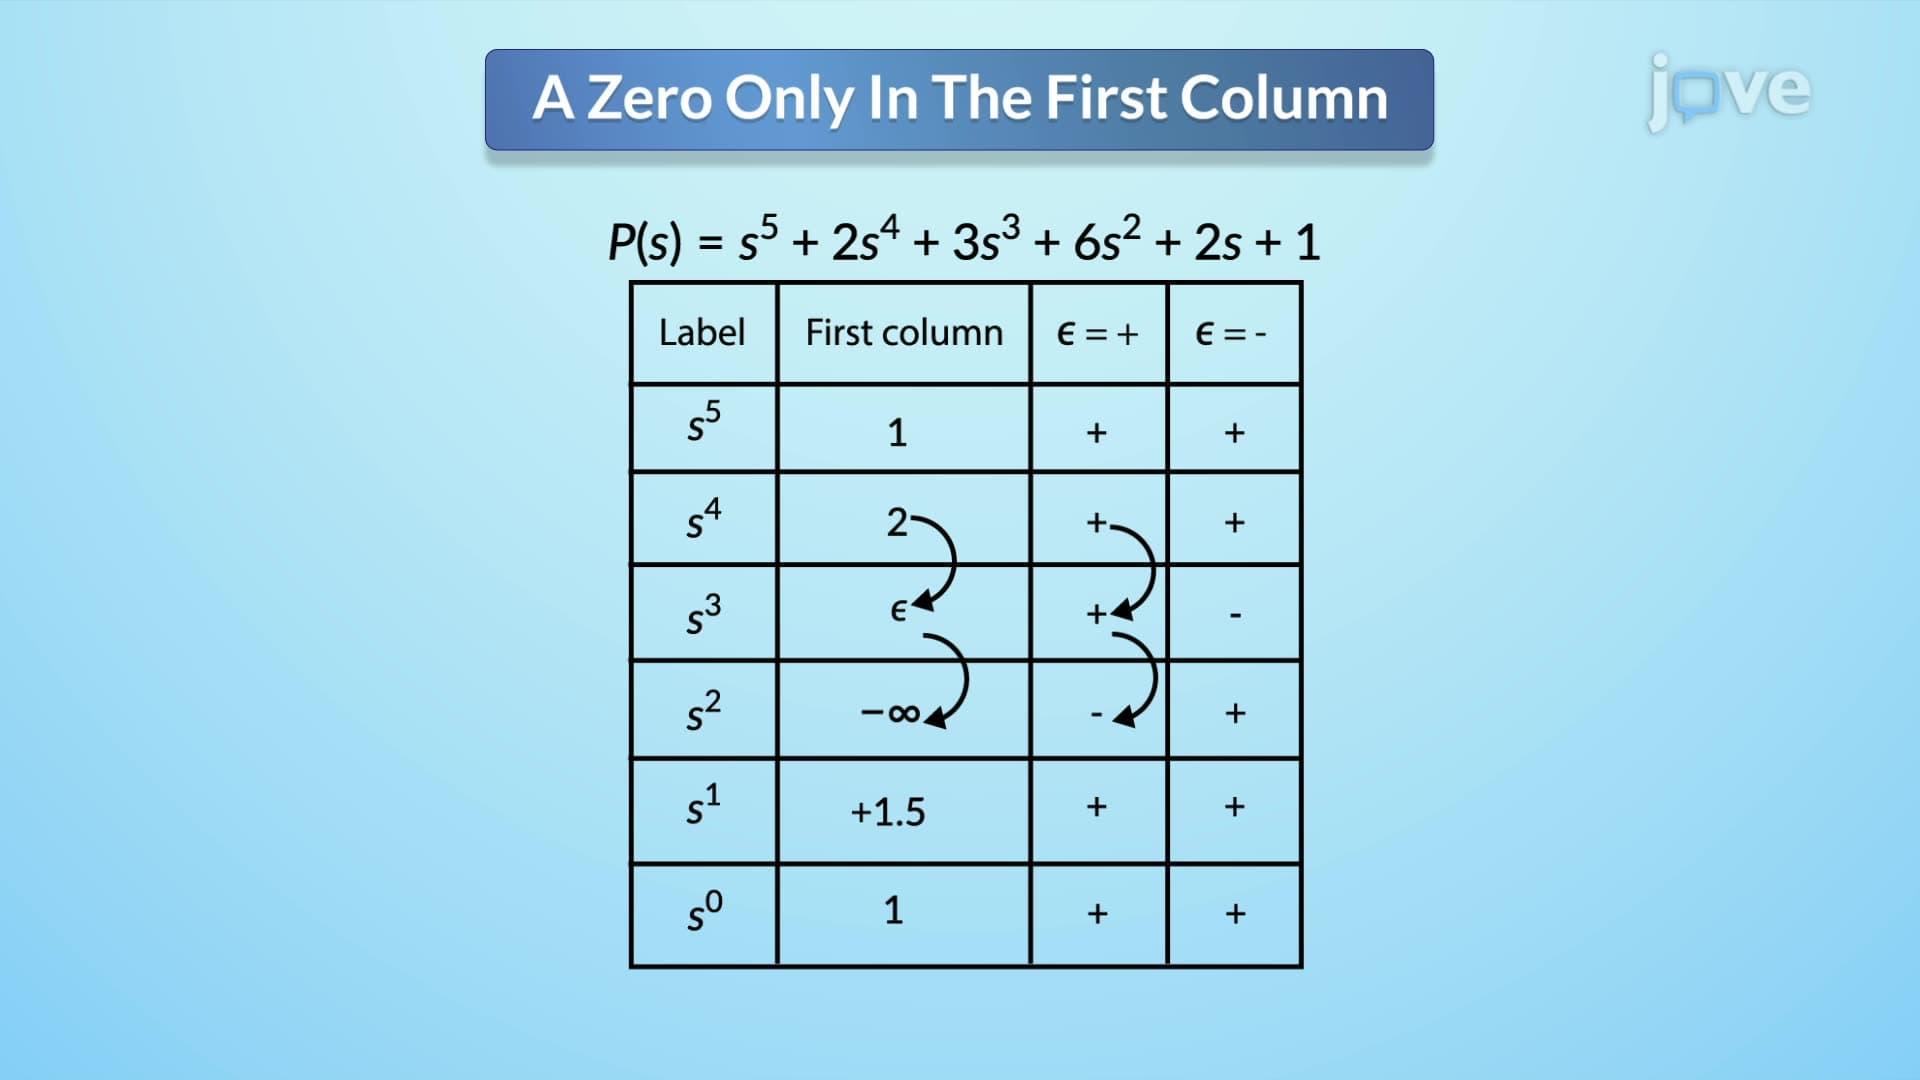
The first scenario occurs when a singular zero appears in the first column of the Routh table. This situation creates a division by zero issues. To resolve this, a small positive or negative number, denoted as epsilon (∈), is substituted for the zero. The stability analysis proceeds by assuming a sign for ∈. If ∈ is positive, any sign change in the first...
 01:25
Modeling with Differential Equations