Related Experiment Videos
Ricci curvature: An economic indicator for market fragility and systemic risk
Romeil S Sandhu1, Tryphon T Georgiou2, Allen R Tannenbaum1
1Departments of Computer Science and Applied Mathematics and Statistics, Stony Brook University, Stony Brook, NY 11794, USA.

Abstract:
Quantifying the systemic risk and fragility of financial systems is of vital importance in analyzing market efficiency, deciding on portfolio allocation, and containing financial contagions. At a high level, financial systems may be represented as weighted graphs that characterize the complex web of interacting agents and information flow (for example, debt, stock returns, and shareholder ownership). Such a representation often turns out to provide keen insights. We show that fragility is a system-level characteristic of "business-as-usual" market behavior and that financial crashes are invariably preceded by system-level changes in robustness. This was done by leveraging previous work, which suggests that Ricci curvature, a key geometric feature of a given network, is negatively correlated to increases in network fragility. To illustrate this insight, we examine daily returns from a set of stocks comprising the Standard and Poor's 500 (S&P 500) over a 15-year span to highlight the fact that corresponding changes in Ricci curvature constitute a financial "crash hallmark." This work lays the foundation of understanding how to design (banking) systems and policy regulations in a manner that can combat financial instabilities exposed during the 2007-2008 crisis.
Related Concept Videos
 01:25
First Derivative Test: Problem Solving
 01:19
Degree of Curvature and Radius of Curvature
 01:15
Relation between Poisson's ratio, Modulus of Elasticity and Modulus of Rigidity
 01:12
Elasticity
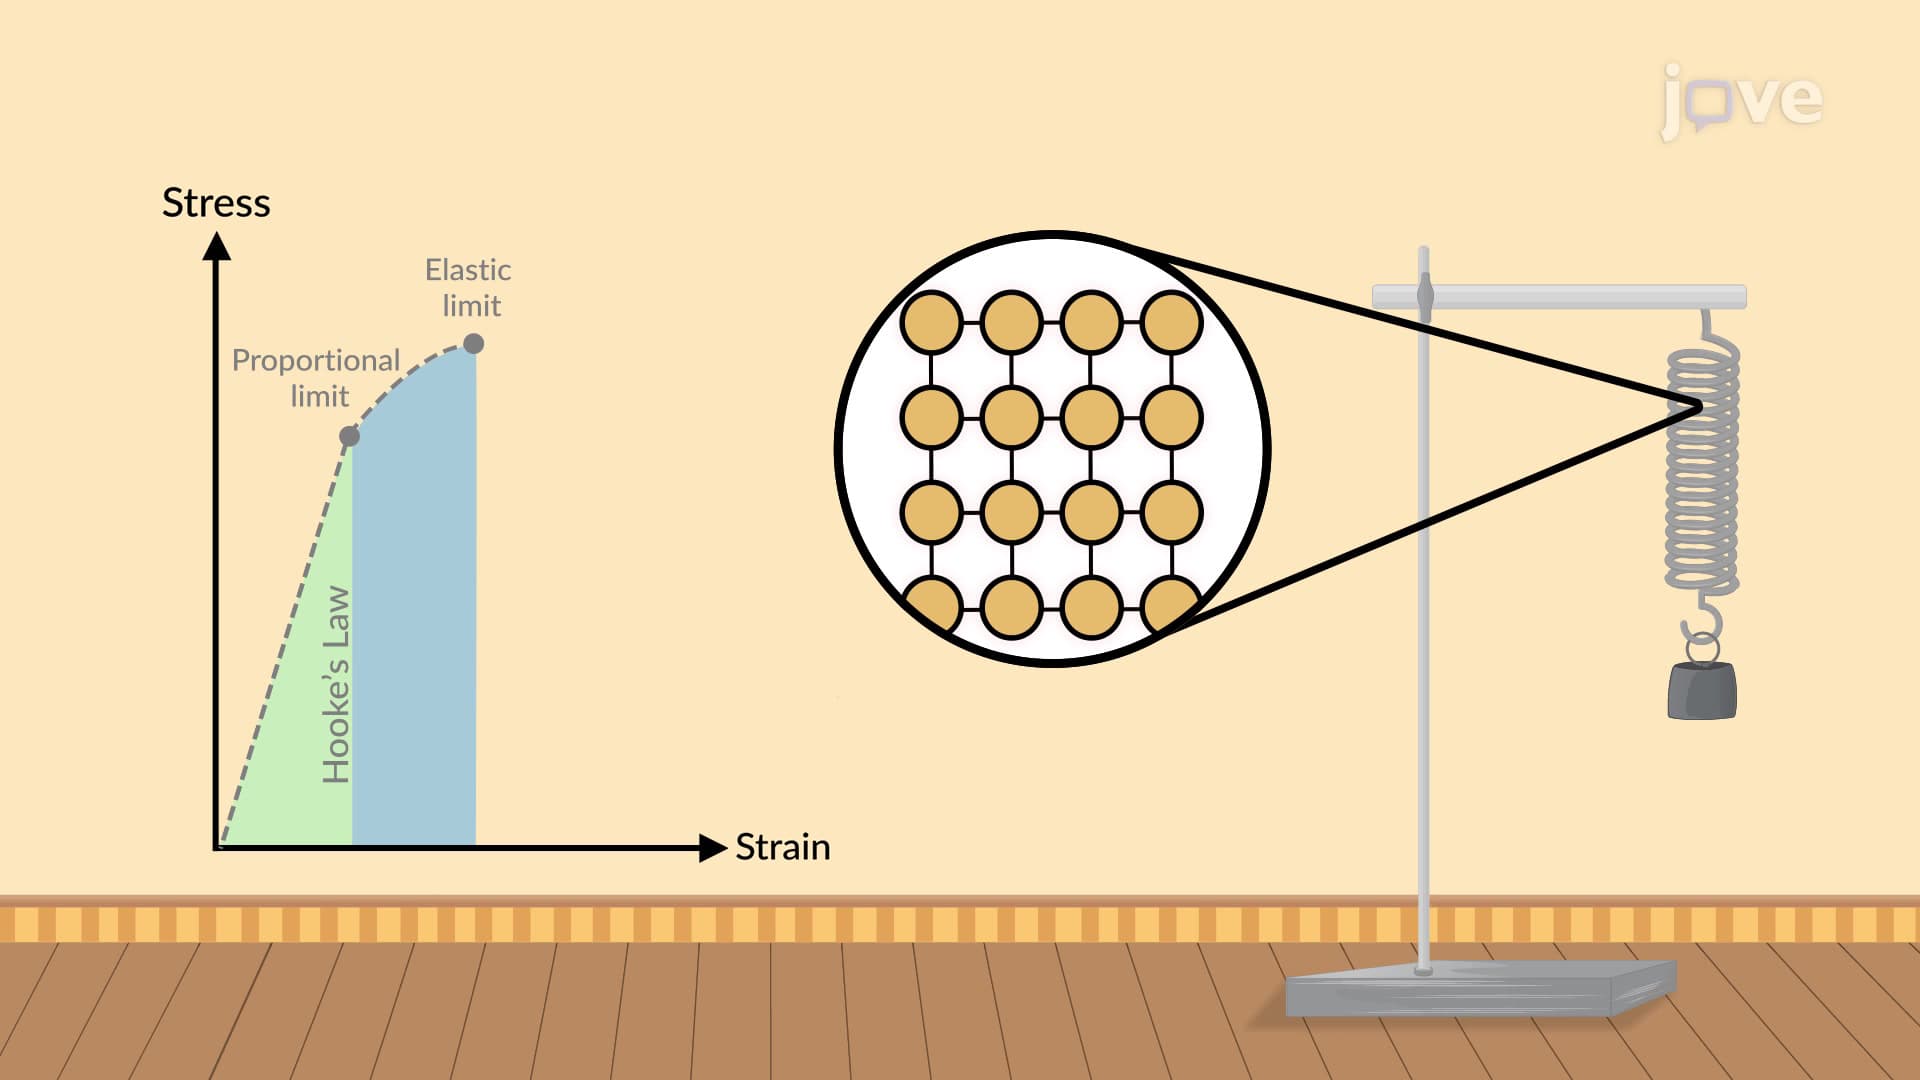
The elasticity of an object can be described by a stress-strain curve, which represents the relationship between stress...
 01:28
Global Regulatory Systems
 01:26
Equity Theory