Related Experiment Video
Updated: Mar 16, 2026

Measuring the Subjective Value of Risky and Ambiguous Options using Experimental Economics and Functional MRI Methods
Published on: September 19, 2012
The valuation of currency options by fractional Brownian motion
Foad Shokrollahi1, Adem Kılıçman2
1Department of Mathematics and Statistics, University of Vaasa, 65101 Vaasa, Finland.

Abstract:
This research aims to investigate a model for pricing of currency options in which value governed by the fractional Brownian motion model (FBM). The fractional partial differential equation and some Greeks are also obtained. In addition, some properties of our pricing formula and simulation studies are presented, which demonstrate that the FBM model is easy to use.
Related Concept Videos
 01:25
First Derivative Test: Problem Solving
 01:26
Application of Antiderivatives: Linear Motion
 01:27
Applications of Integration to Probability Density Functions
 01:15
Derivatives
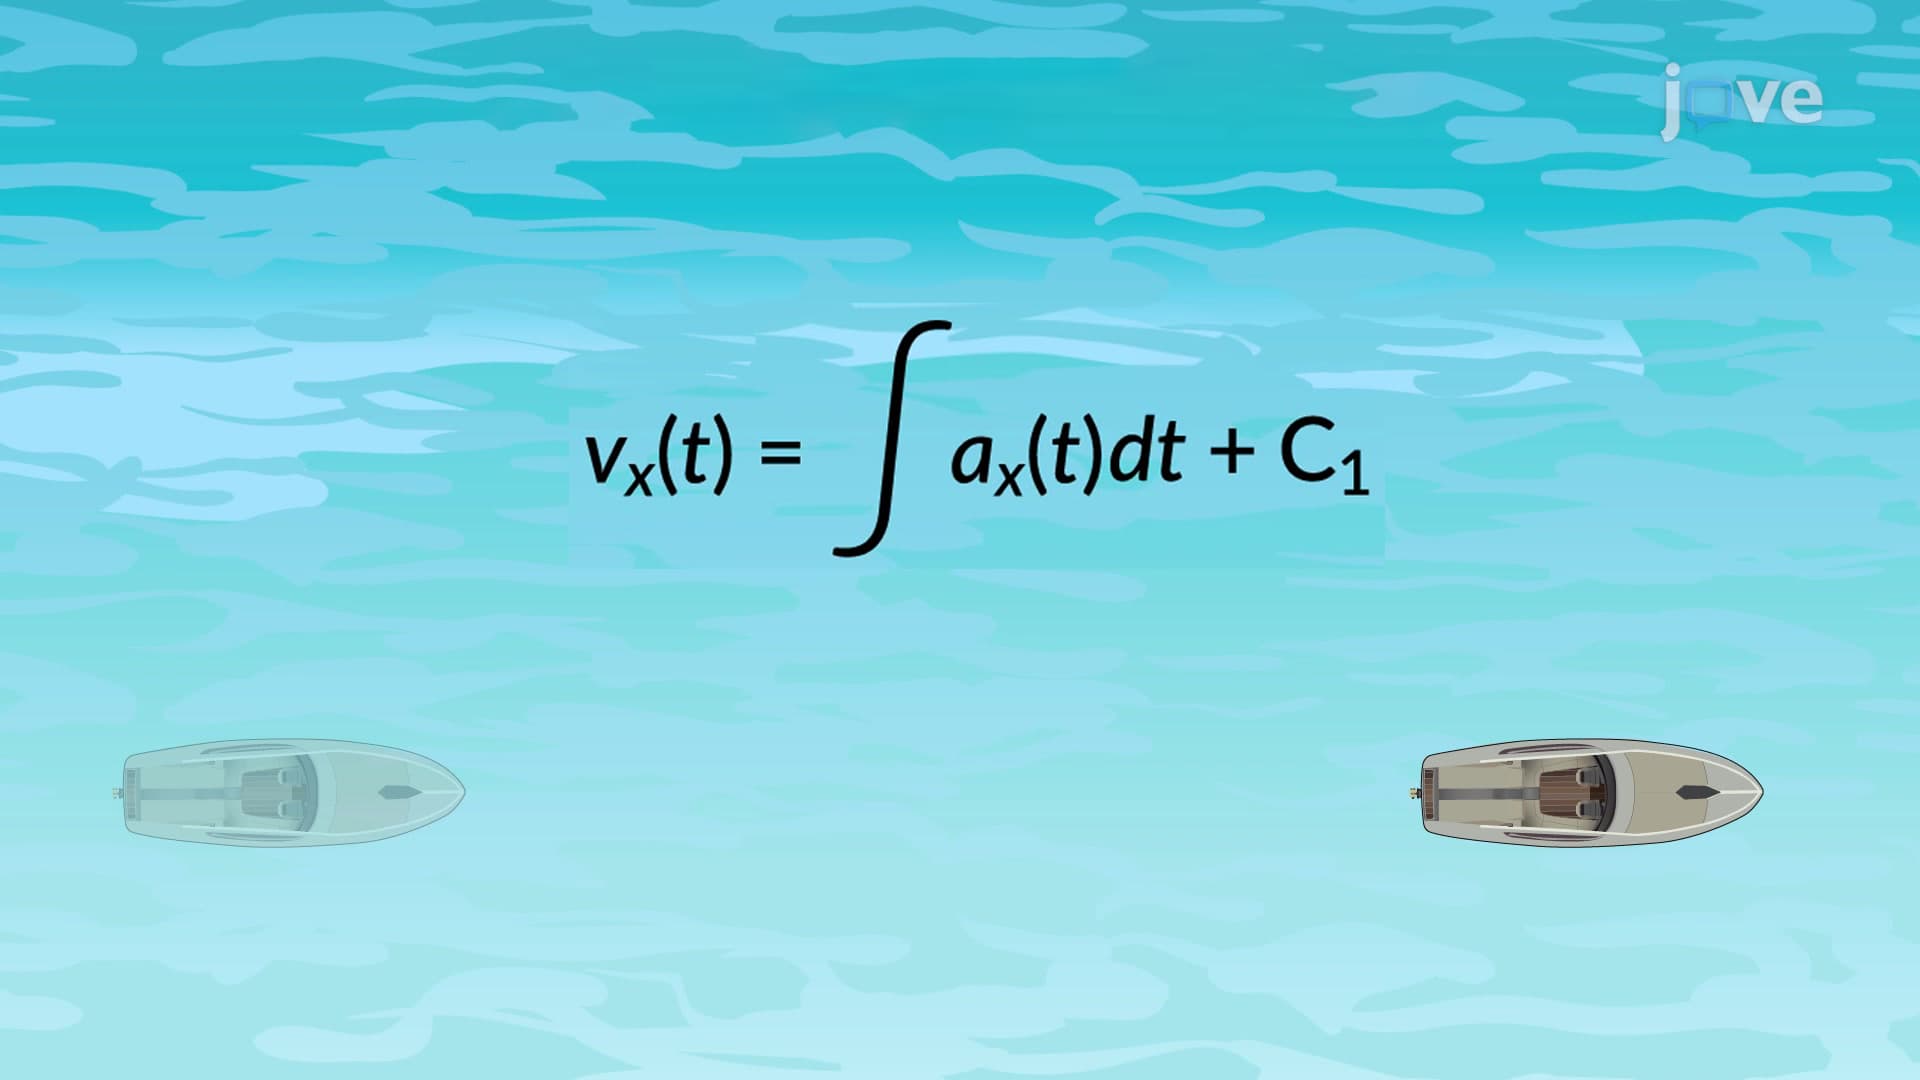 01:13
Velocity and Position by Integral Method
Consider an example to calculate the velocity and position from the acceleration function. A motorboat is traveling at a constant velocity of 5.0 m/s when it starts to decelerate to arrive at the dock. Its acceleration is...
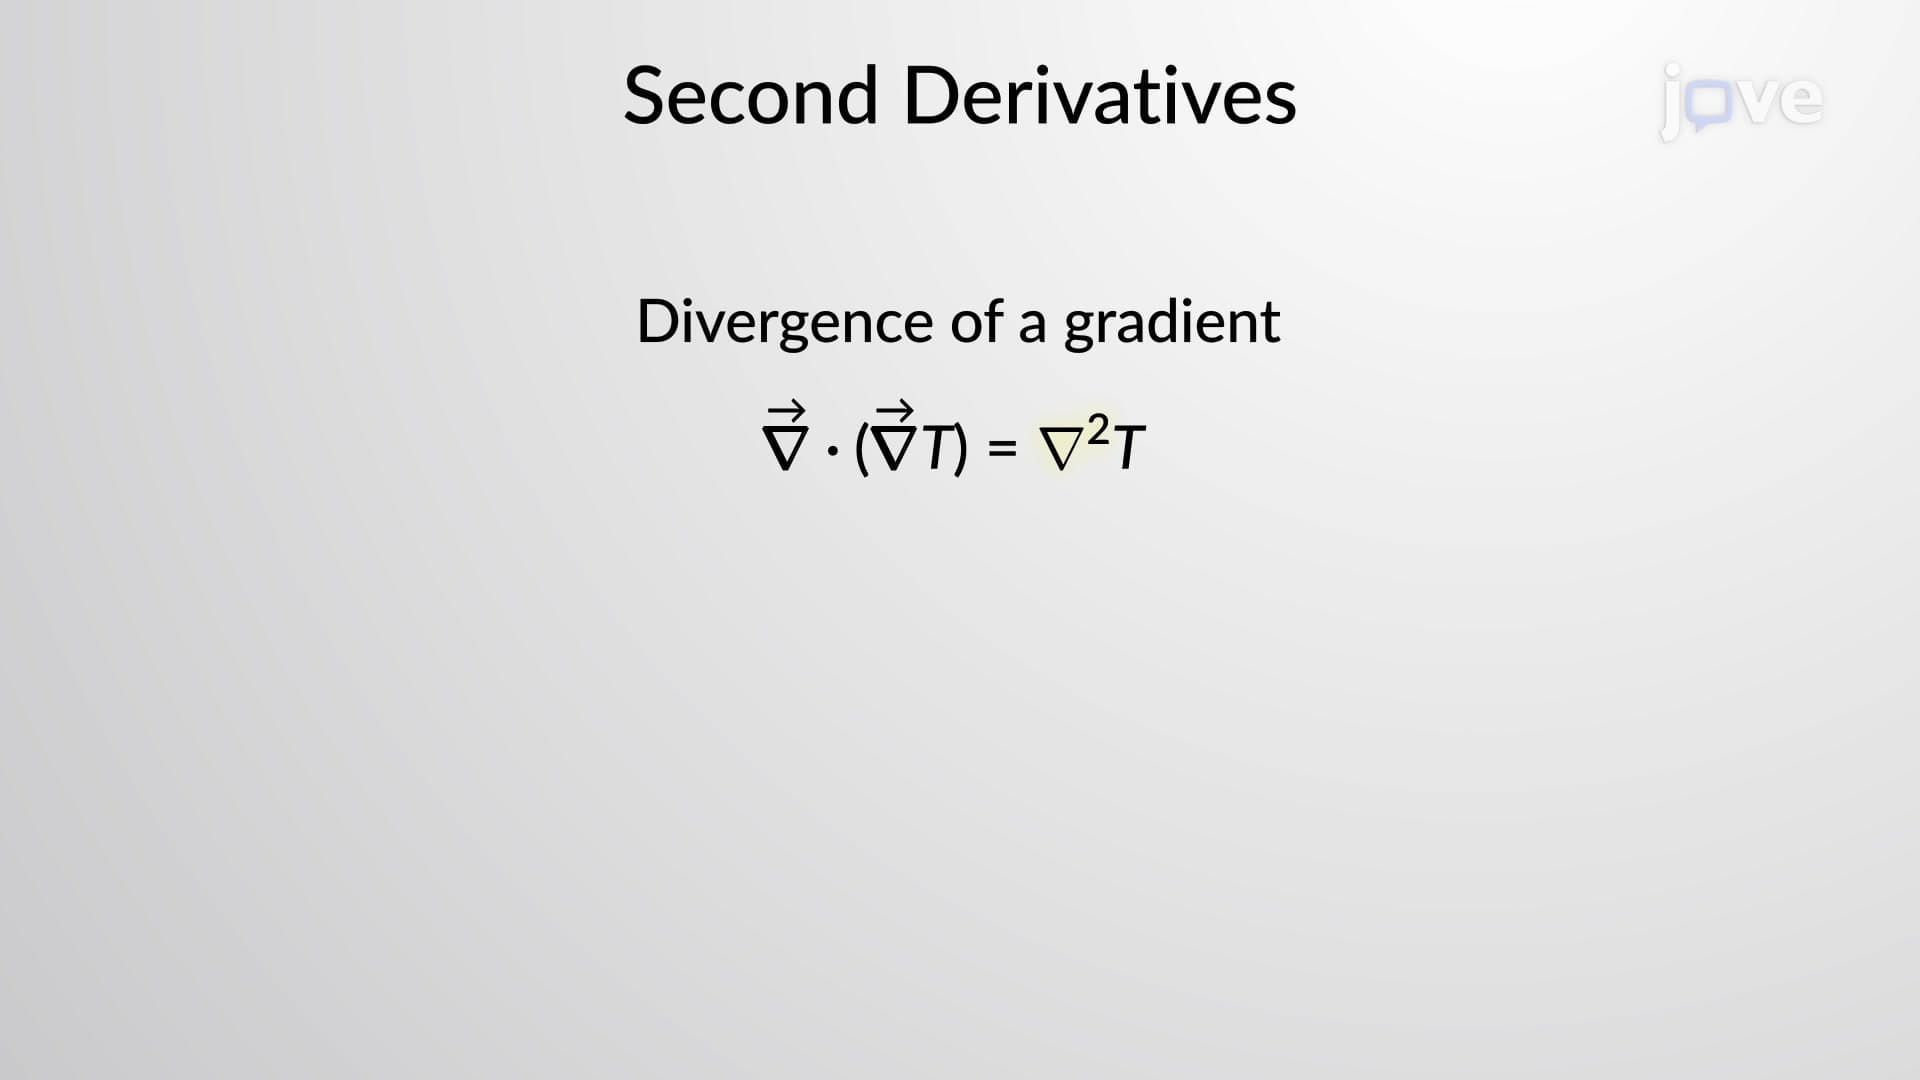 01:22
Second Derivatives and Laplace Operator
Consider a scalar function. The curl of its...