Related Experiment Video
Updated: Mar 12, 2026
Applying an eMASS Customization Program as a Research Tool to Evaluate Consumer Benefits
Published on: September 27, 2019
Universality of market superstatistics
Mateusz Denys1, Tomasz Gubiec1, Ryszard Kutner1
1Faculty of Physics, University of Warsaw, Pasteur 5, PL-02093 Warsaw, Poland.

Abstract:
We use a key concept of the continuous-time random walk formalism, i.e., continuous and fluctuating interevent times in which mutual dependence is taken into account, to model market fluctuation data when traders experience excessive (or superthreshold) losses or excessive (or superthreshold) profits. We analytically derive a class of "superstatistics" that accurately model empirical market activity data supplied by Bogachev, Ludescher, Tsallis, and Bunde that exhibit transition thresholds. We measure the interevent times between excessive losses and excessive profits and use the mean interevent discrete (or step) time as a control variable to derive a universal description of empirical data collapse. Our dominant superstatistic value is a power-law corrected by the lower incomplete gamma function, which asymptotically tends toward robustness but initially gives an exponential. We find that the scaling shape exponent that drives our superstatistics subordinates itself and a "superscaling" configuration emerges. Thanks to the Weibull copula function, our approach reproduces the empirically proven dependence between successive interevent times. We also use the approach to calculate a dynamic risk function and hence the dynamic VaR, which is significant in financial risk analysis. Our results indicate that there is a functional (but not literal) balance between excessive profits and excessive losses that can be described using the same body of superstatistics but different calibration values and driving parameters. We also extend our original approach to cover empirical seismic activity data (e.g., given by Corral), the interevent times of which range from minutes to years. Superpositioned superstatistics is another class of superstatistics that protects power-law behavior both for short- and long-time behaviors. These behaviors describe well the collapse of seismic activity data and capture so-called volatility clustering phenomena.
More Related Videos
 06:39
Electroencephalographic, Heart Rate, and Galvanic Skin Response Assessment for an Advertising Perception Study: Application to Antismoking Public Service Announcements
Published on: August 28, 2017
 09:17
Using a Virtual Store As a Research Tool to Investigate Consumer In-store Behavior
Published on: July 24, 2017
Related Concept Videos
 01:10
Statgraphics
 01:11
Statistical Analysis: Overview
One of the most commonly used statistical quantifiers is the mean, which is the ratio between the sum of the numerical values of all results and the...
 01:29
Applications of Integration to Find Consumer Surplus
 01:23
Test for Homogeneity
 01:29
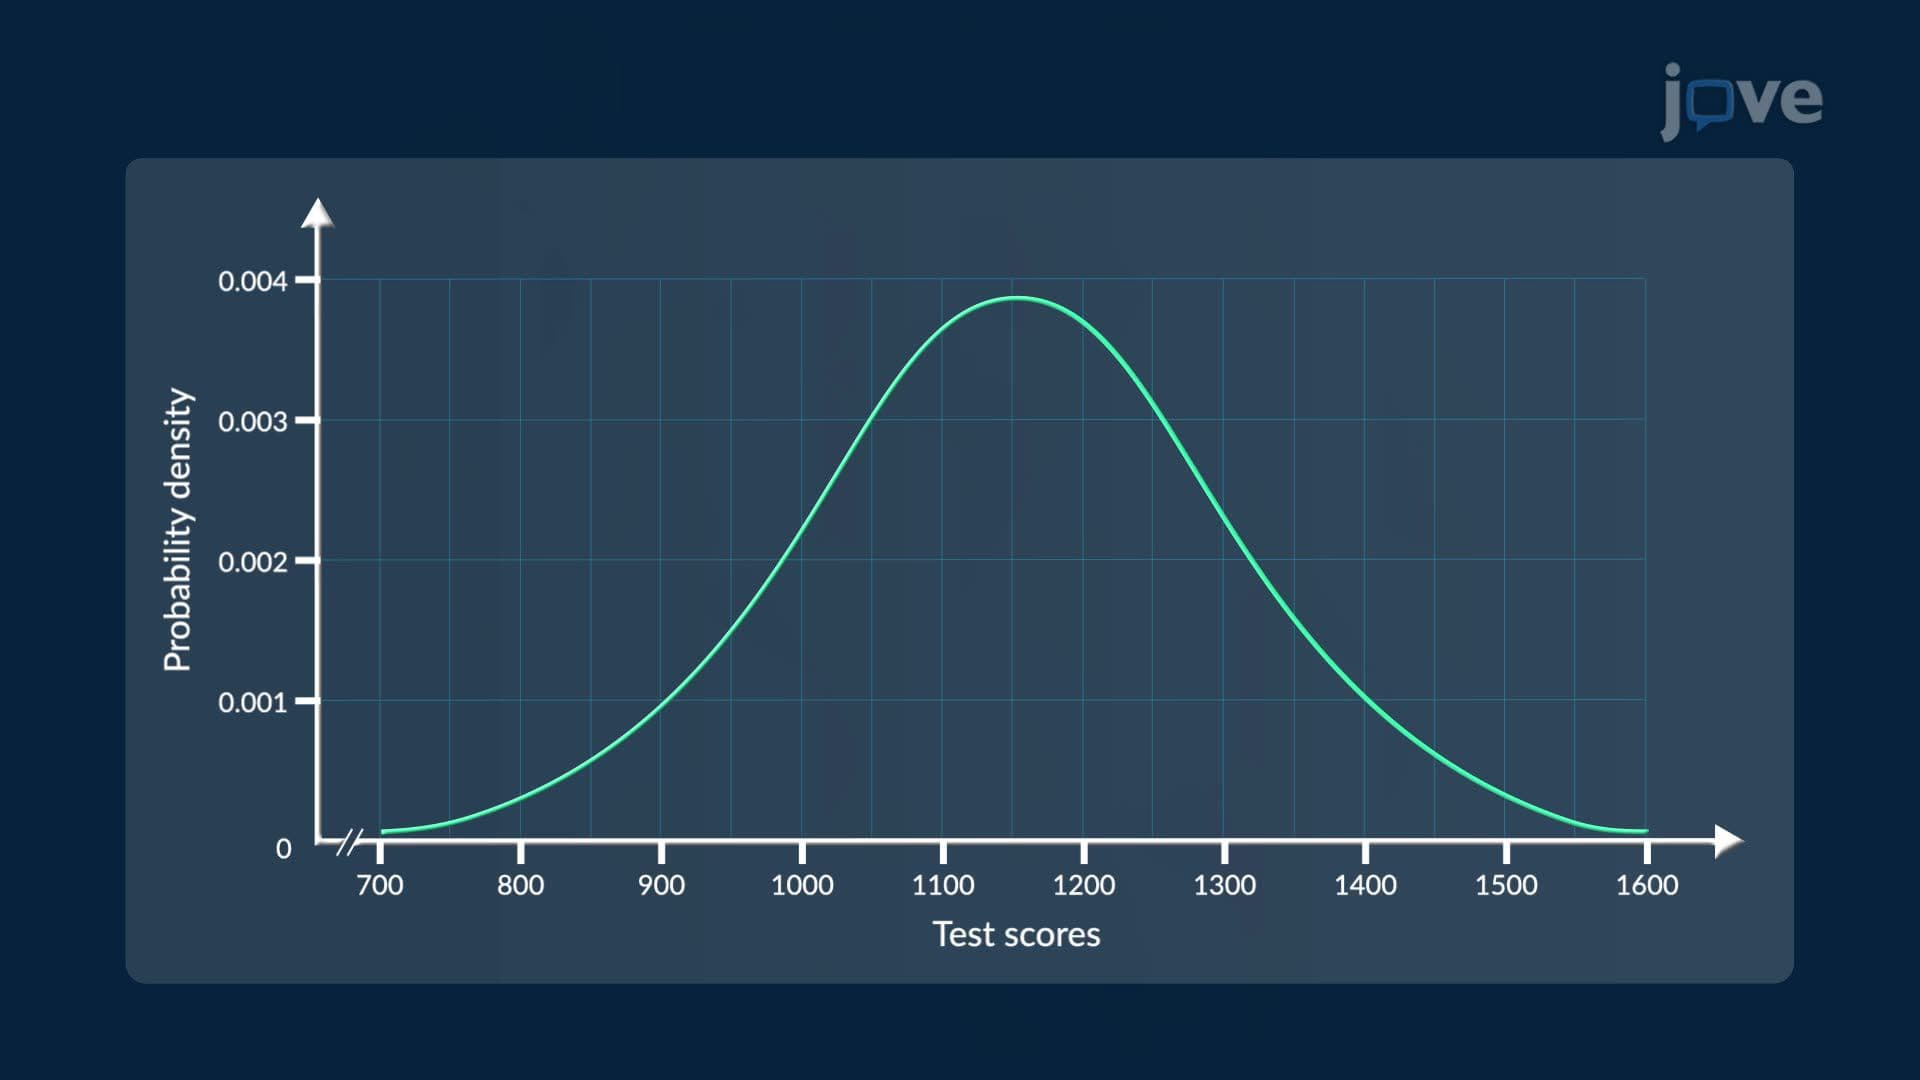
Introduction to Normal Distributions
 01:17
Introduction to Statistics
In statistics, the collection of individuals or objects under study is called population. The idea of sampling is to select a portion of the larger population...