Related Experiment Video
Updated: Mar 11, 2026

Development of an Individual-Tree Basal Area Increment Model using a Linear Mixed-Effects Approach
Published on: July 3, 2020
Heterogeneous autoregressive model with structural break using nearest neighbor truncation volatility estimators for
Wen Cheong Chin1, Min Cherng Lee2, Grace Lee Ching Yap3
1Faculty of Management, SIG Quantitative Economics and Finance, Multimedia University, 63100 Cyberjaya, Selangor Malaysia.

Abstract:
High frequency financial data modelling has become one of the important research areas in the field of financial econometrics. However, the possible structural break in volatile financial time series often trigger inconsistency issue in volatility estimation. In this study, we propose a structural break heavy-tailed heterogeneous autoregressive (HAR) volatility econometric model with the enhancement of jump-robust estimators. The breakpoints in the volatility are captured by dummy variables after the detection by Bai-Perron sequential multi breakpoints procedure. In order to further deal with possible abrupt jump in the volatility, the jump-robust volatility estimators are composed by using the nearest neighbor truncation approach, namely the minimum and median realized volatility. Under the structural break improvements in both the models and volatility estimators, the empirical findings show that the modified HAR model provides the best performing in-sample and out-of-sample forecast evaluations as compared with the standard HAR models. Accurate volatility forecasts have direct influential to the application of risk management and investment portfolio analysis.
Related Concept Videos
 01:24
One-Compartment Open Model: Wagner-Nelson and Loo Riegelman Method for ka Estimation
On...
 01:25
First Derivative Test: Problem Solving
 01:10
Standard Deviation
 00:56
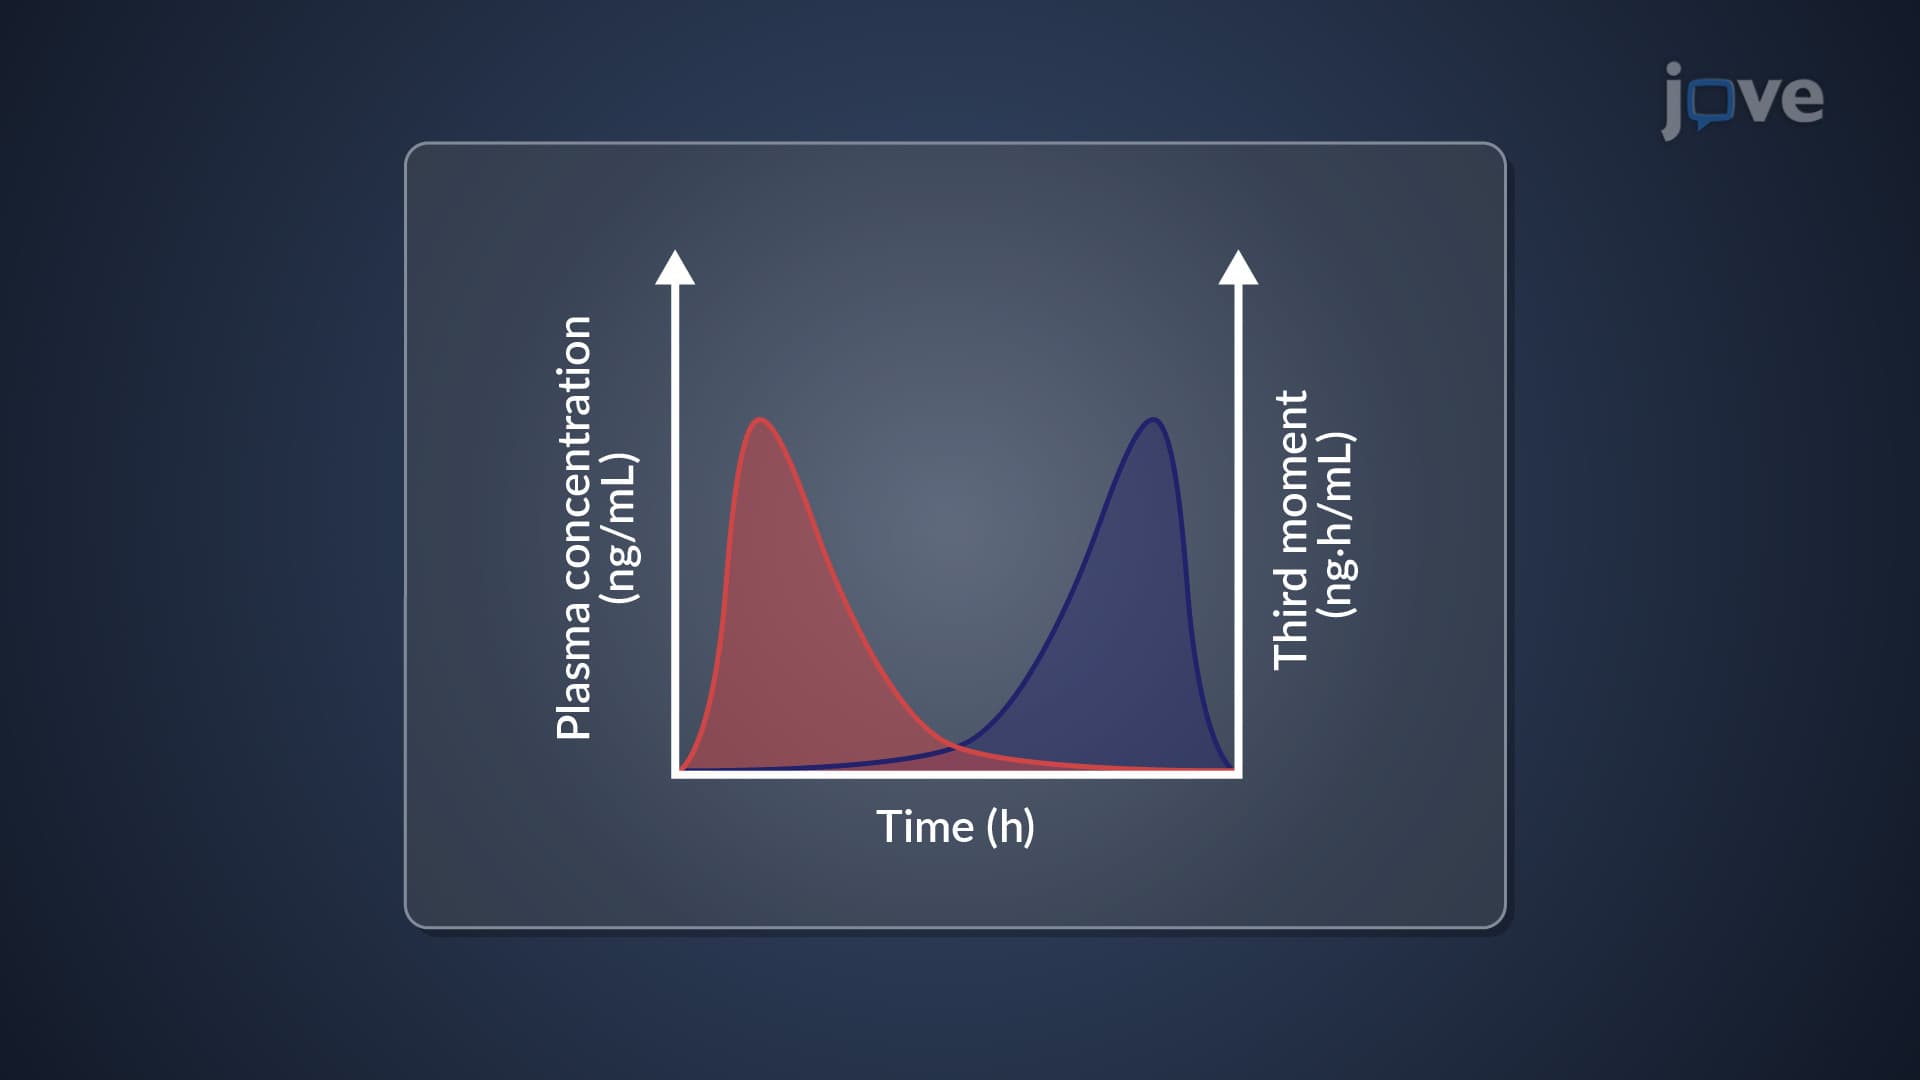
Noncompartmental Analysis: Statistical Moment Theory
 01:23
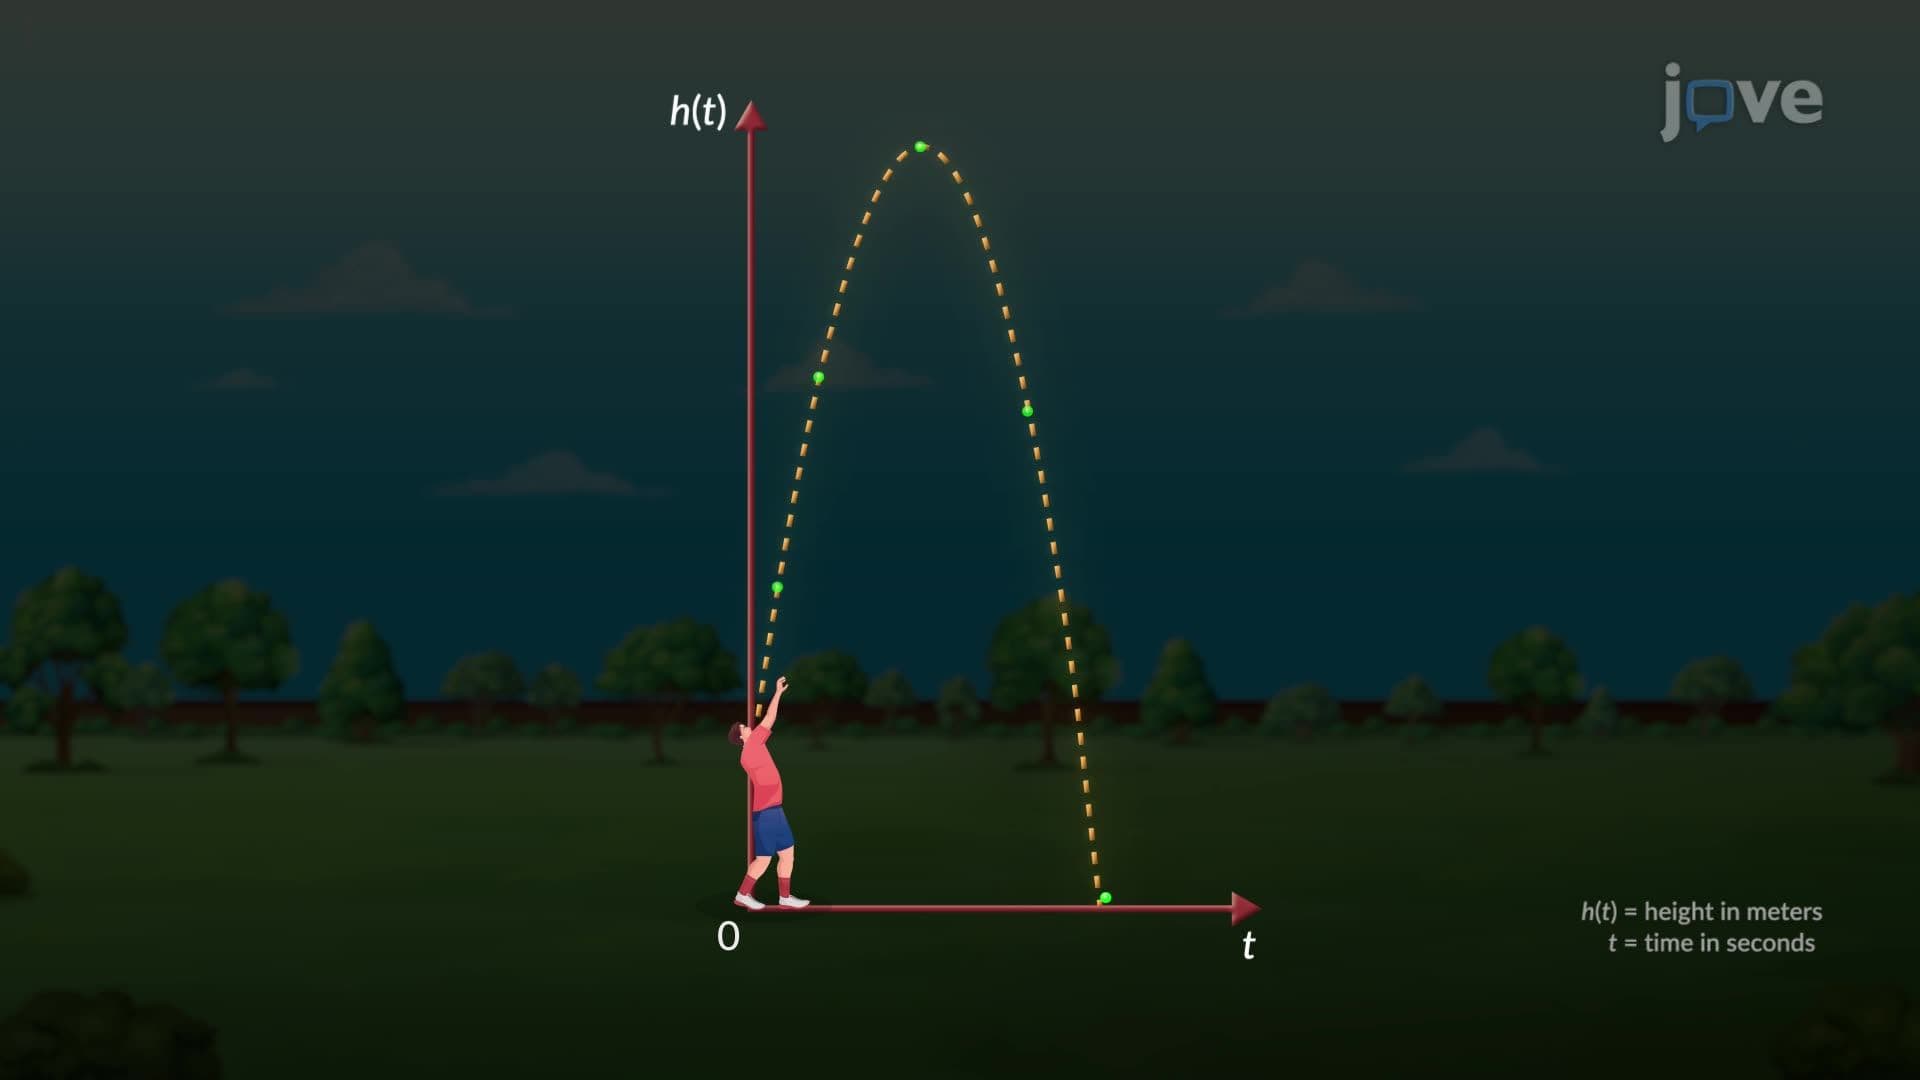
Quadratic Models
 01:23
Mechanistic Models: Compartment Models in Individual and Population Analysis