Related Experiment Video
Updated: Mar 9, 2026

Measuring Attention and Visual Processing Speed by Model-based Analysis of Temporal-order Judgments
Published on: January 23, 2017
Time-Varying Transition Probability Matrix Estimation and Its Application to Brand Share Analysis
Tomoaki Chiba1, Hideitsu Hino2, Shotaro Akaho3
1Department of Electrical Engineering and Bioscience, Waseda University, Shinjuku, Tokyo, Japan.

Abstract:
In a product market or stock market, different products or stocks compete for the same consumers or purchasers. We propose a method to estimate the time-varying transition matrix of the product share using a multivariate time series of the product share. The method is based on the assumption that each of the observed time series of shares is a stationary distribution of the underlying Markov processes characterized by transition probability matrices. We estimate transition probability matrices for every observation under natural assumptions. We demonstrate, on a real-world dataset of the share of automobiles, that the proposed method can find intrinsic transition of shares. The resulting transition matrices reveal interesting phenomena, for example, the change in flows between TOYOTA group and GM group for the fiscal year where TOYOTA group's sales beat GM's sales, which is a reasonable scenario.

Related Concept Videos
 01:21
Friedman Two-way Analysis of Variance by Ranks
 00:56
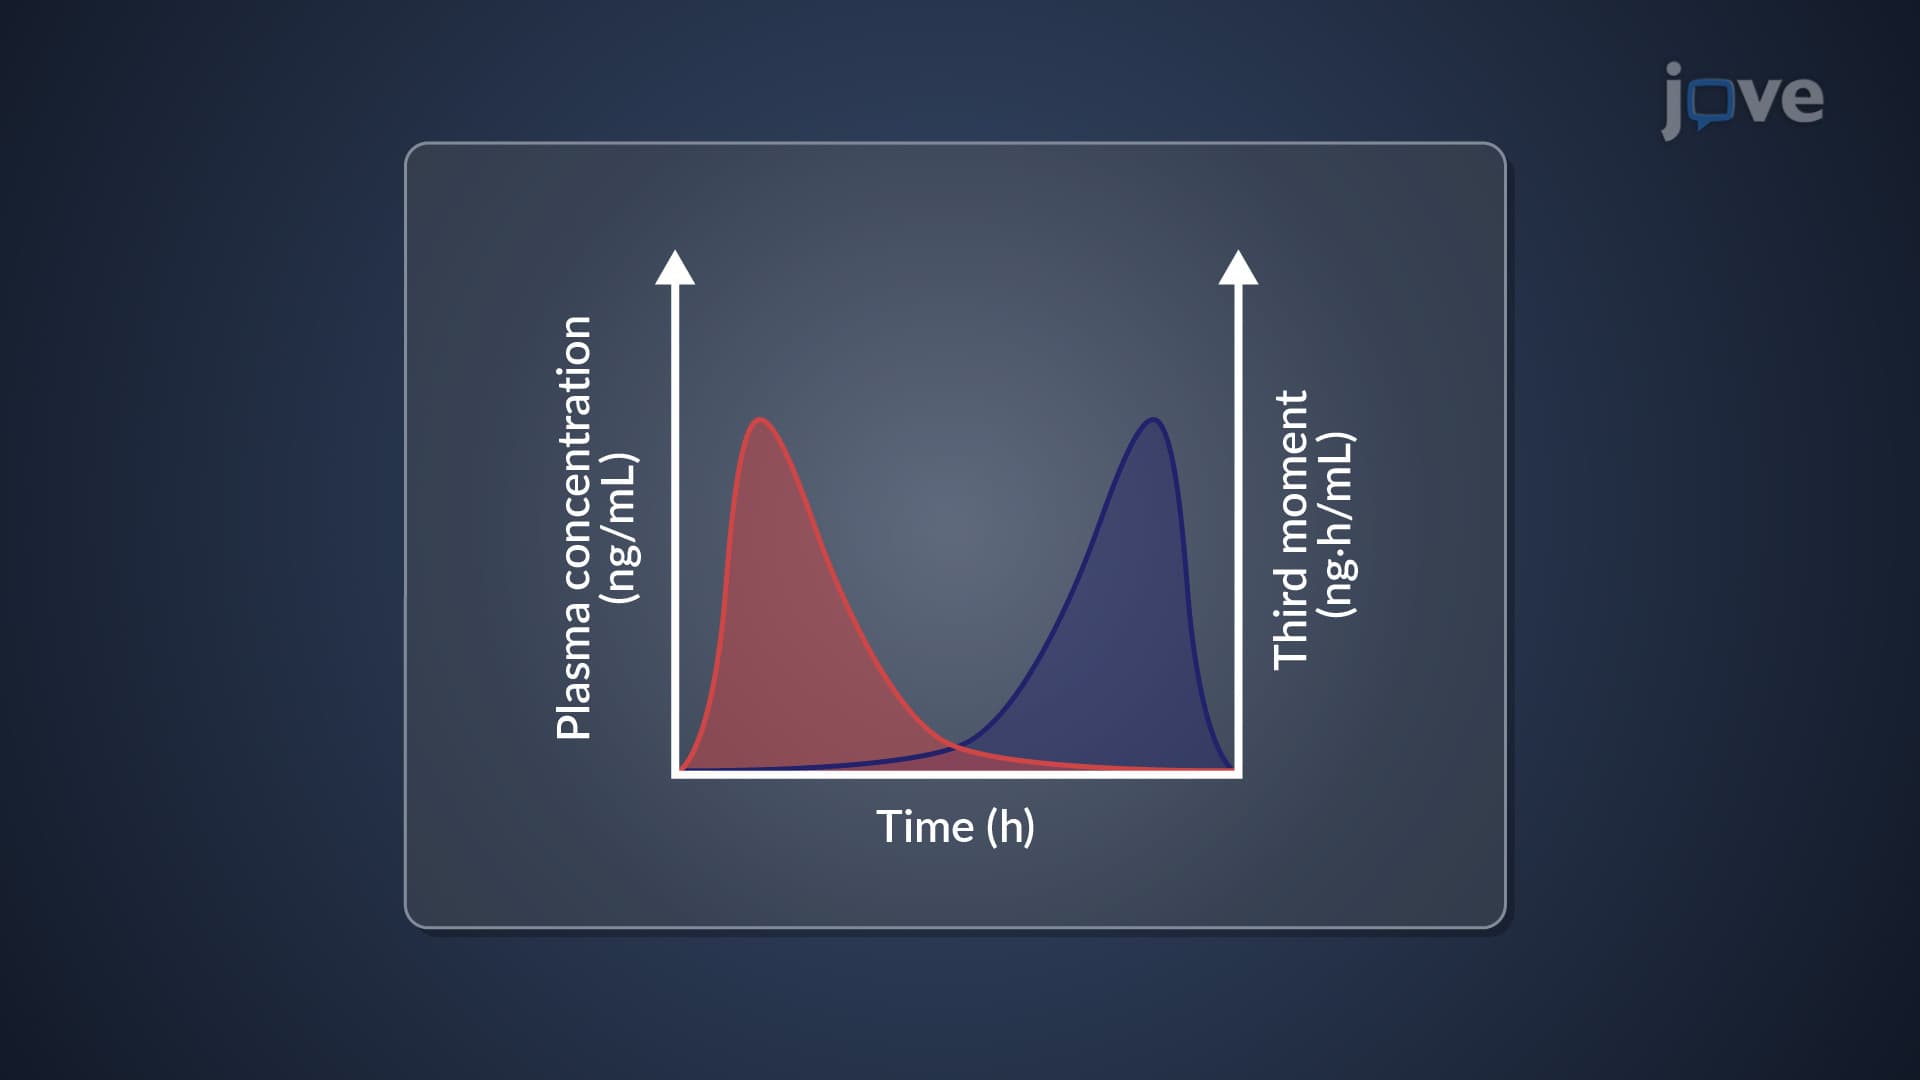
Noncompartmental Analysis: Statistical Moment Theory
 01:11
Variability: Analysis
The range is a simple measure of variability, indicating the difference between the highest and...
 01:32
Probability Distributions
A discrete probability distribution is a probability distribution of discrete random variables. It can be categorized into binomial probability distribution and Poisson...
 01:09
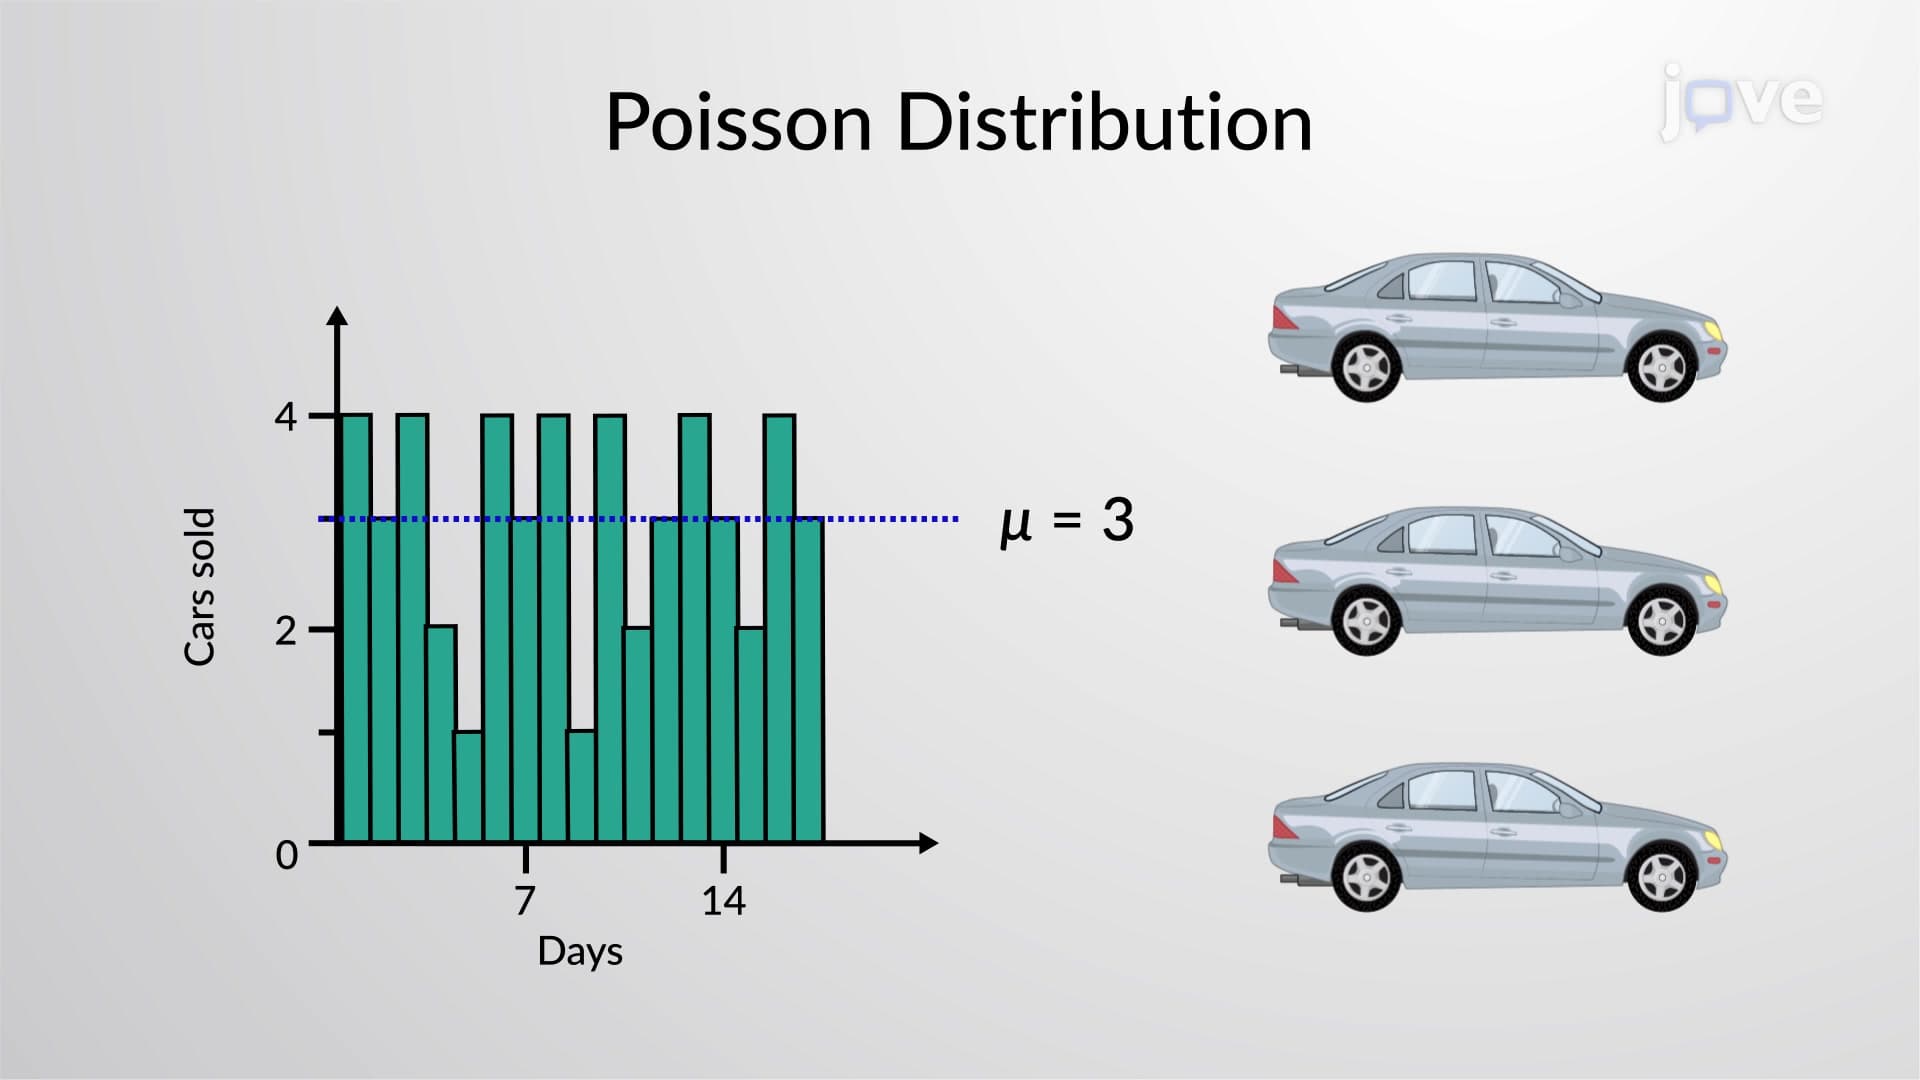
Poisson Probability Distribution
The...
 01:24
One-Compartment Open Model: Wagner-Nelson and Loo Riegelman Method for ka Estimation
On...