Related Experiment Video
Updated: Mar 7, 2026

Multiscale Sampling of a Heterogeneous Water/Metal Catalyst Interface using Density Functional Theory and Force-Field Molecular Dynamics
Published on: April 12, 2019
A detailed heterogeneous agent model for a single asset financial market with trading via an order book
Roberto Mota Navarro1, Hernán Larralde1
1Instituto de Ciencias Físicas, Cuernavaca, Morelos, México.

Abstract:
We present an agent based model of a single asset financial market that is capable of replicating most of the non-trivial statistical properties observed in real financial markets, generically referred to as stylized facts. In our model agents employ strategies inspired on those used in real markets, and a realistic trade mechanism based on a double auction order book. We study the role of the distinct types of trader on the return statistics: specifically, correlation properties (or lack thereof), volatility clustering, heavy tails, and the degree to which the distribution can be described by a log-normal. Further, by introducing the practice of "profit taking", our model is also capable of replicating the stylized fact related to an asymmetry in the distribution of losses and gains.
Related Concept Videos
 01:22
Heterogeneous Catalysis
 01:25
First Derivative Test: Problem Solving
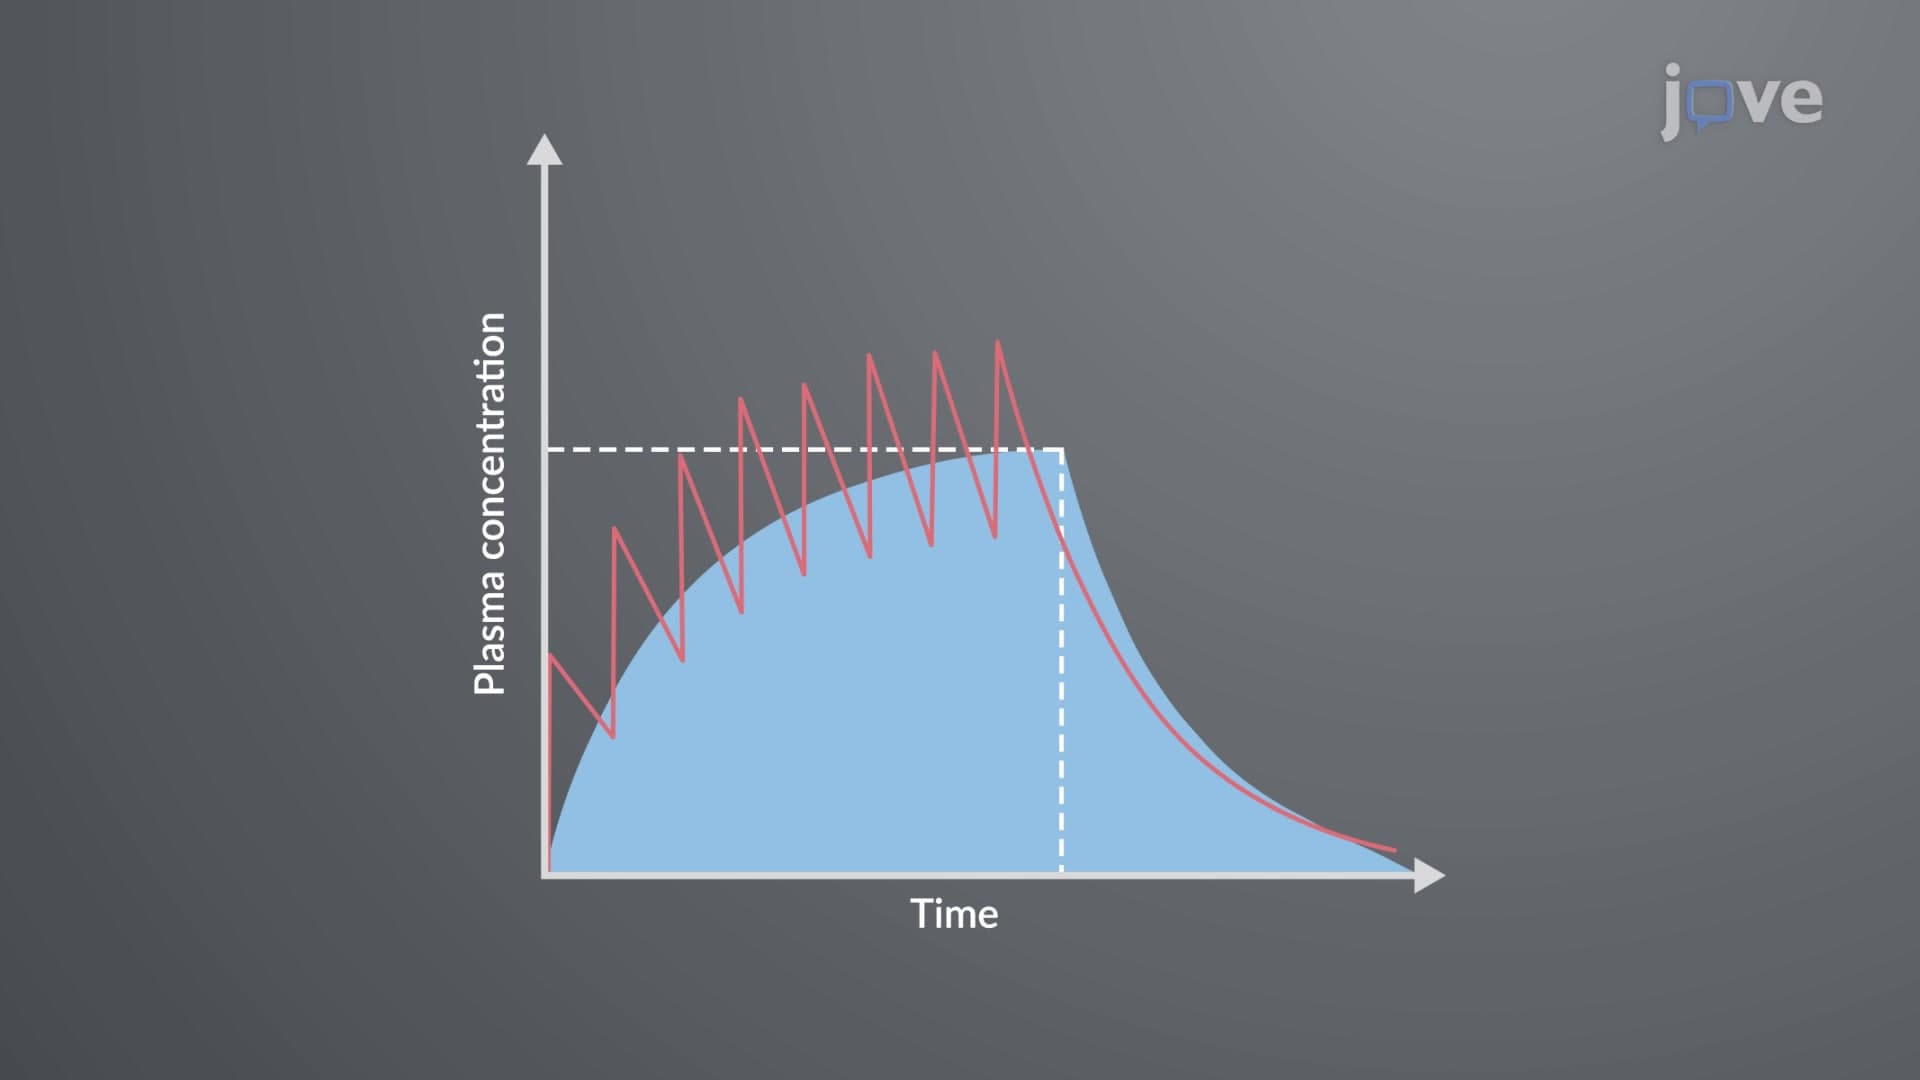 01:14
Compartment Models: Single-Compartment Model
 02:20
Dynamic Equilibrium
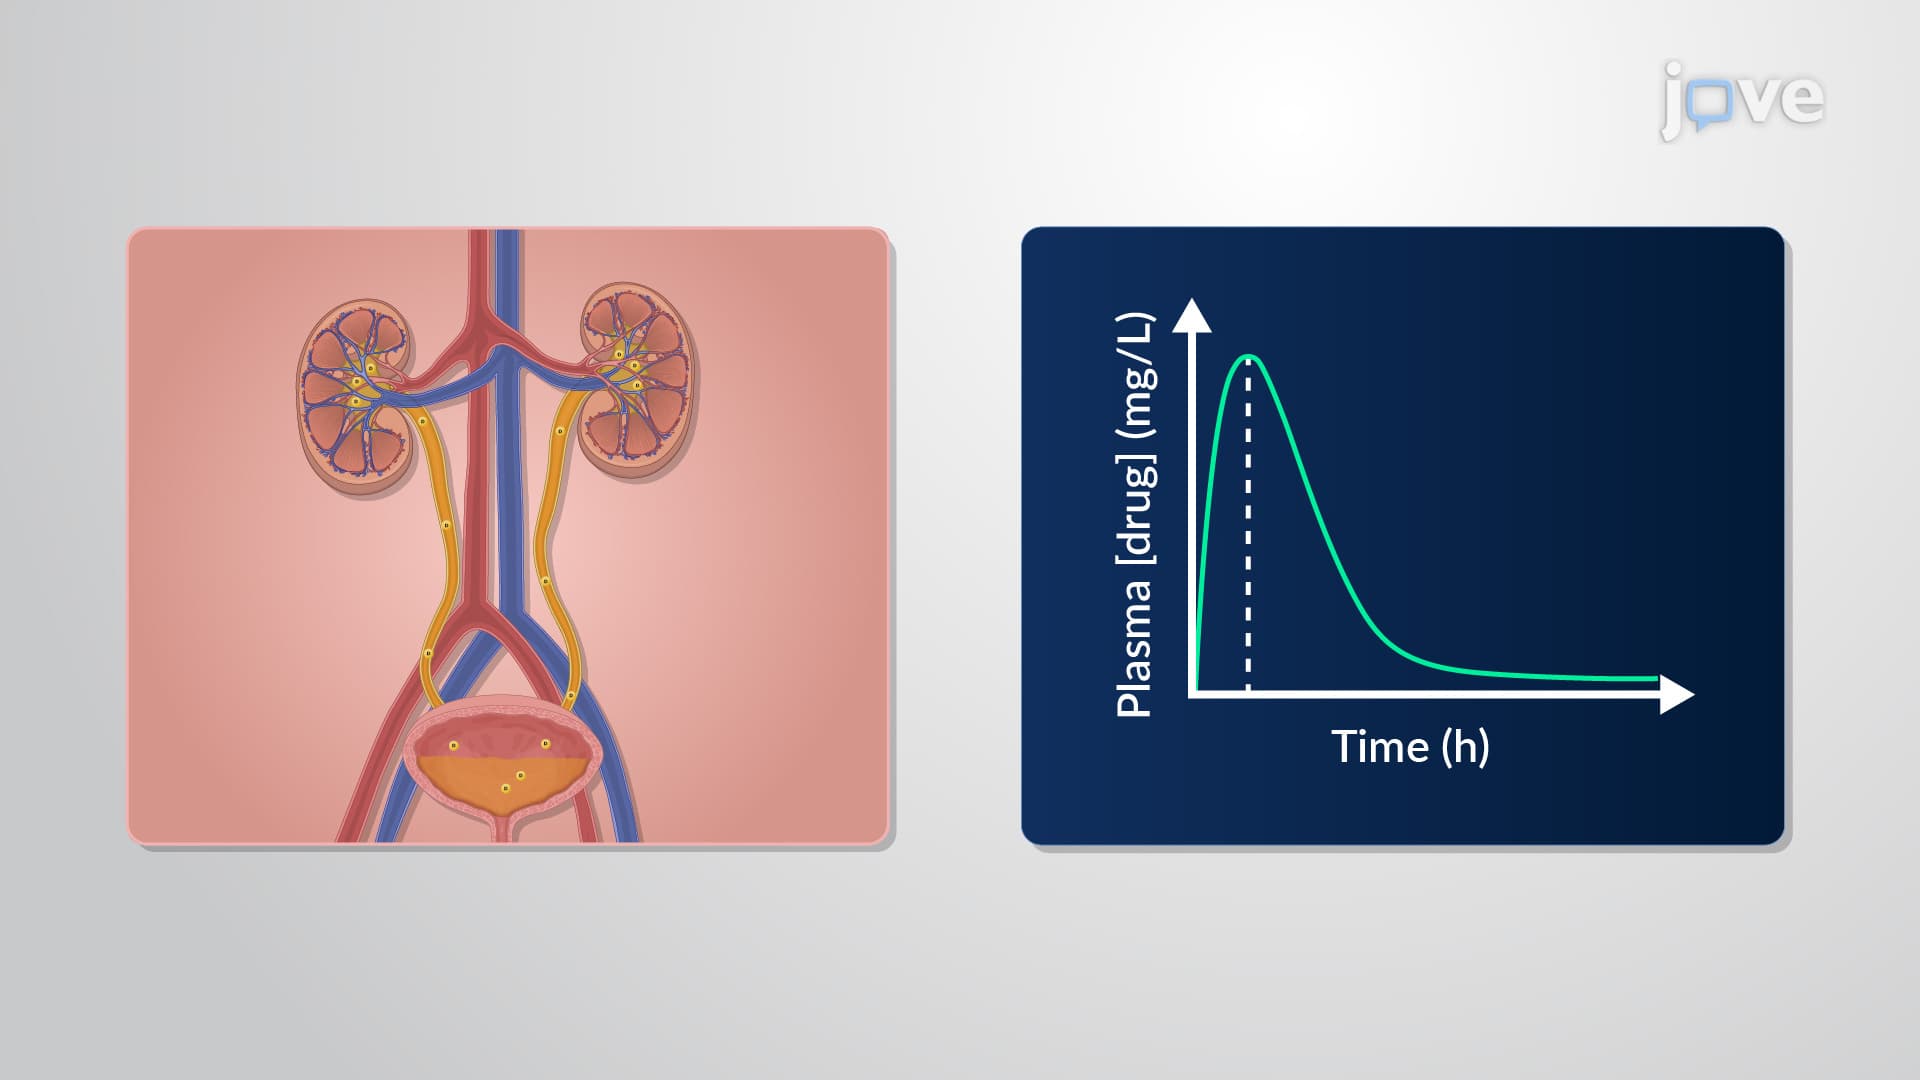 01:13
Parameters Affecting Nonlinear Elimination: Zero-Order Input, First-Order Absorption and Two-Compartment Model
When a drug is administered through a constant intravenous infusion and eliminated via nonlinear pharmacokinetics, it follows zero-order input. For example, oral drugs undergo first-order absorption upon administration and are eliminated through nonlinear pharmacokinetics.
In the case of subcutaneously administered drugs,...
 03:10
The Equilibrium Constant