Related Experiment Video
Updated: Dec 31, 2025

Accurate Determination of the Equilibrium Surface Tension Values with Area Perturbation Tests
Published on: August 30, 2019
A stochastic Fubini theorem: BSDE method
1School of Mathematics and Statistics, Southwest University, Chongqing, 400715 China.

Abstract:
In this paper, we prove a stochastic Fubini theorem by solving a special backward stochastic differential equation (BSDE, for short) which is different from the existing techniques. As an application, we obtain the well-posedness of a class of BSDEs with the Itô integral in drift term under a subtle Lipschitz condition.
Related Concept Videos
 01:30
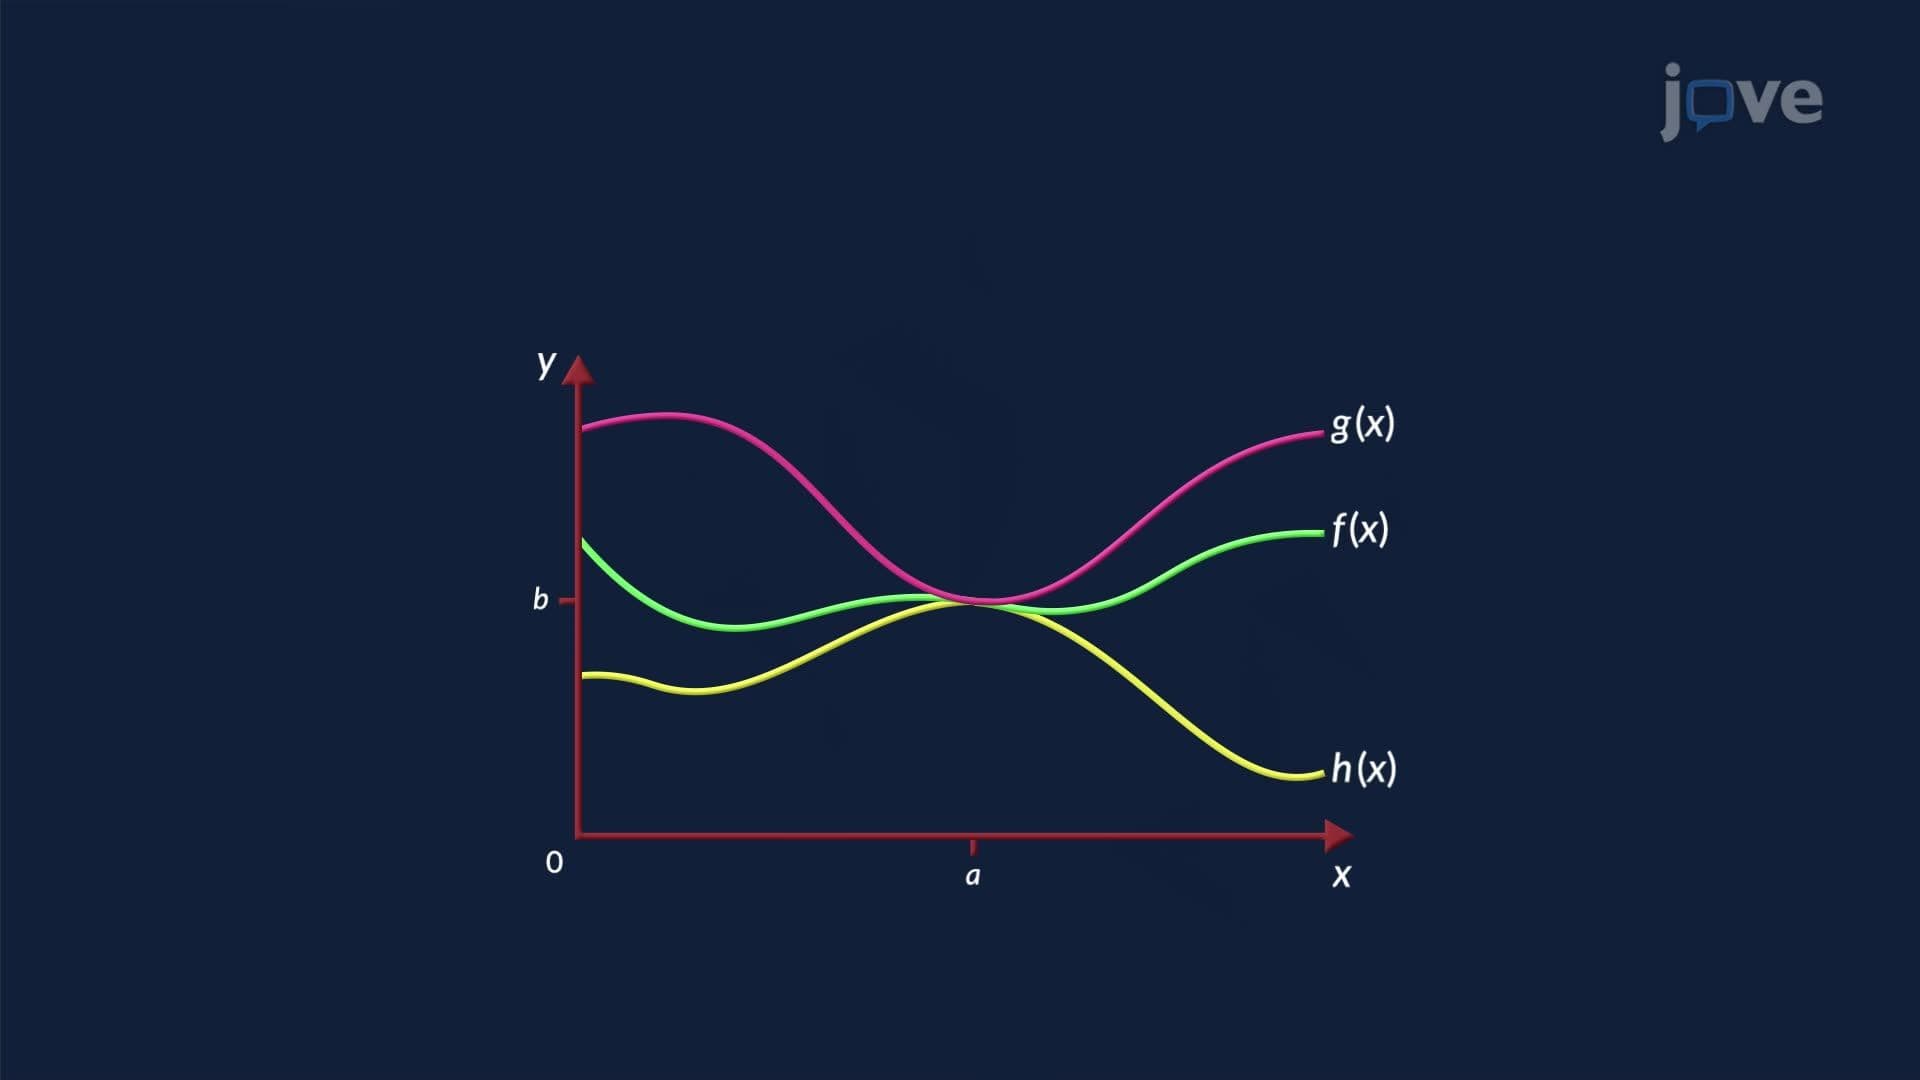
The Squeeze Theorem
 01:24
BIBO stability of continuous and discrete -time systems
To determine the BIBO stability, the convolution integral is utilized when a bounded continuous-time input is applied to a Linear Time-Invariant (LTI) system....
 01:16
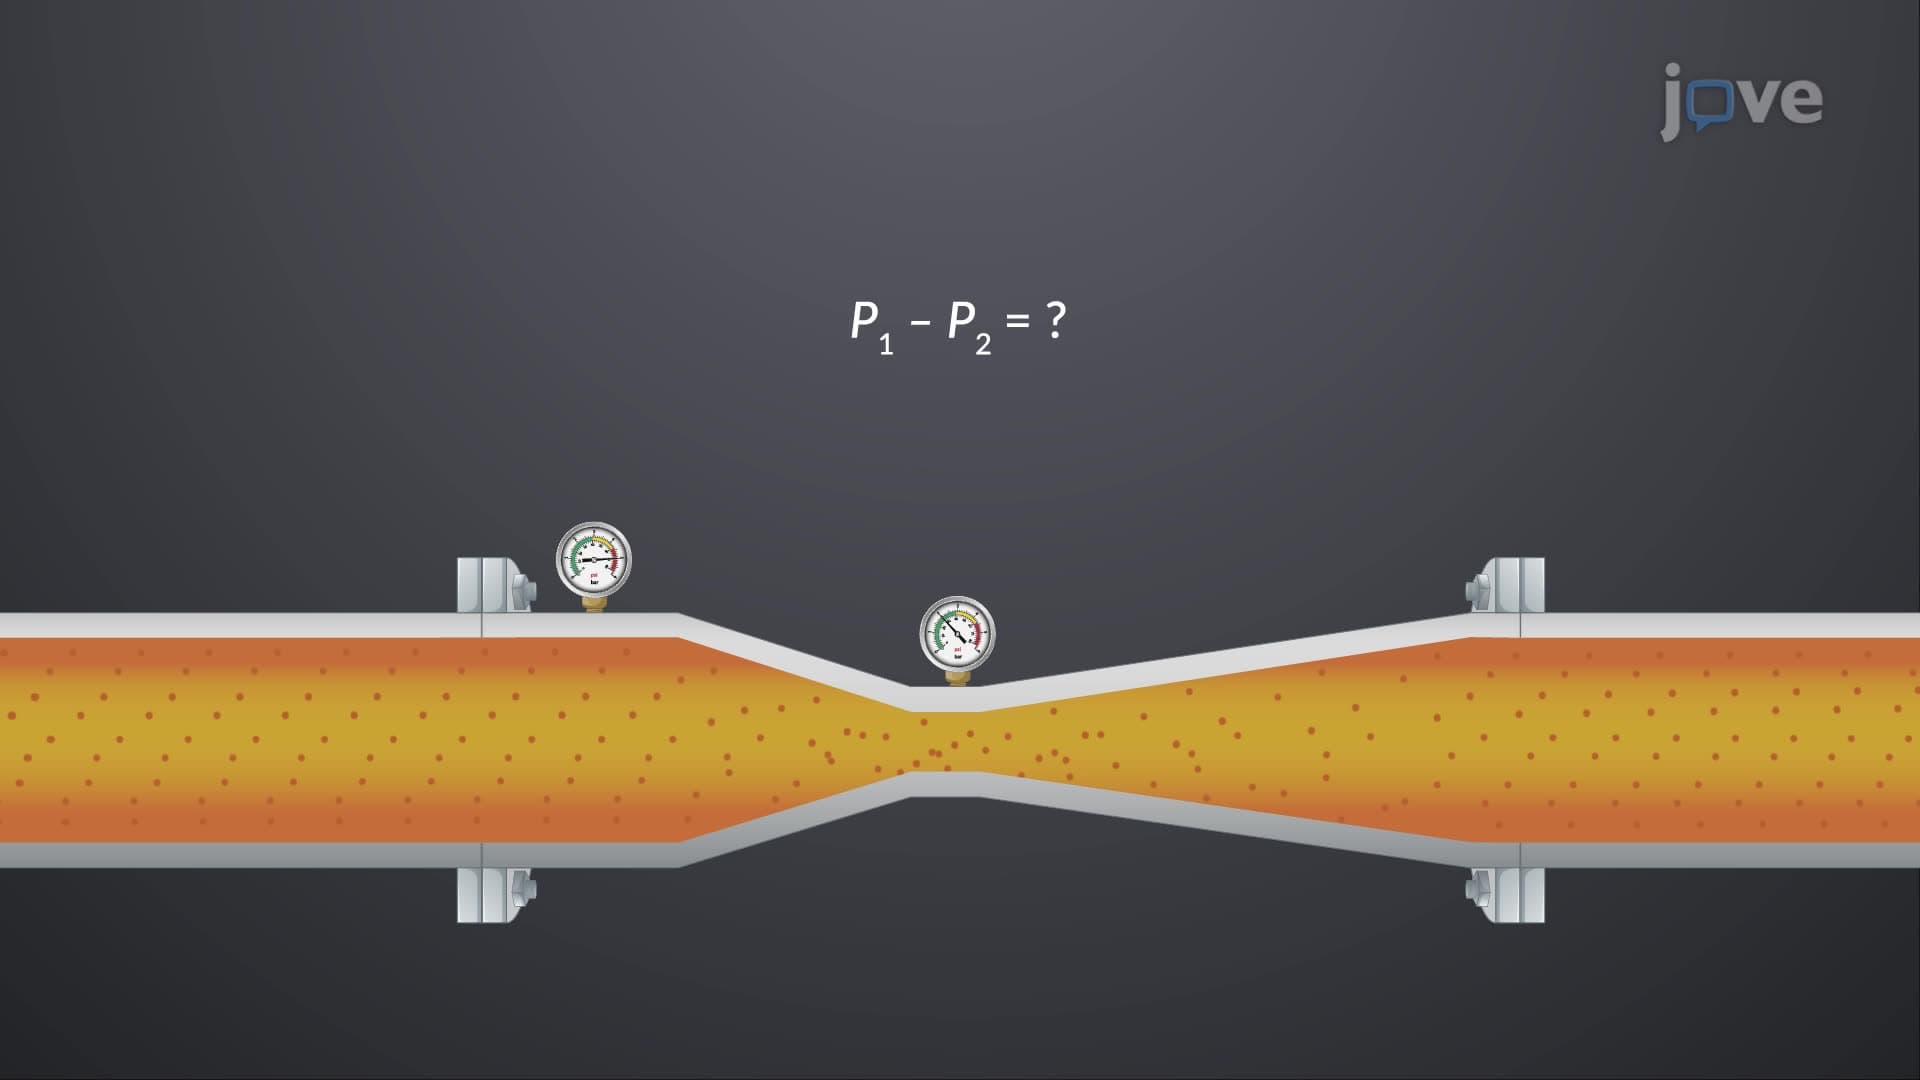
Bernoulli's Equation: Problem Solving
The first step is to compute the cross-sectional areas of the pipe and the Venturi throat to analyze the pressure difference indicated by the pressure gauge. Next, the continuity equation is...
 01:15
Chebyshev's Theorem to Interpret Standard Deviation
 01:19
Uniform Distribution
Two essential properties of this distribution are
 00:59
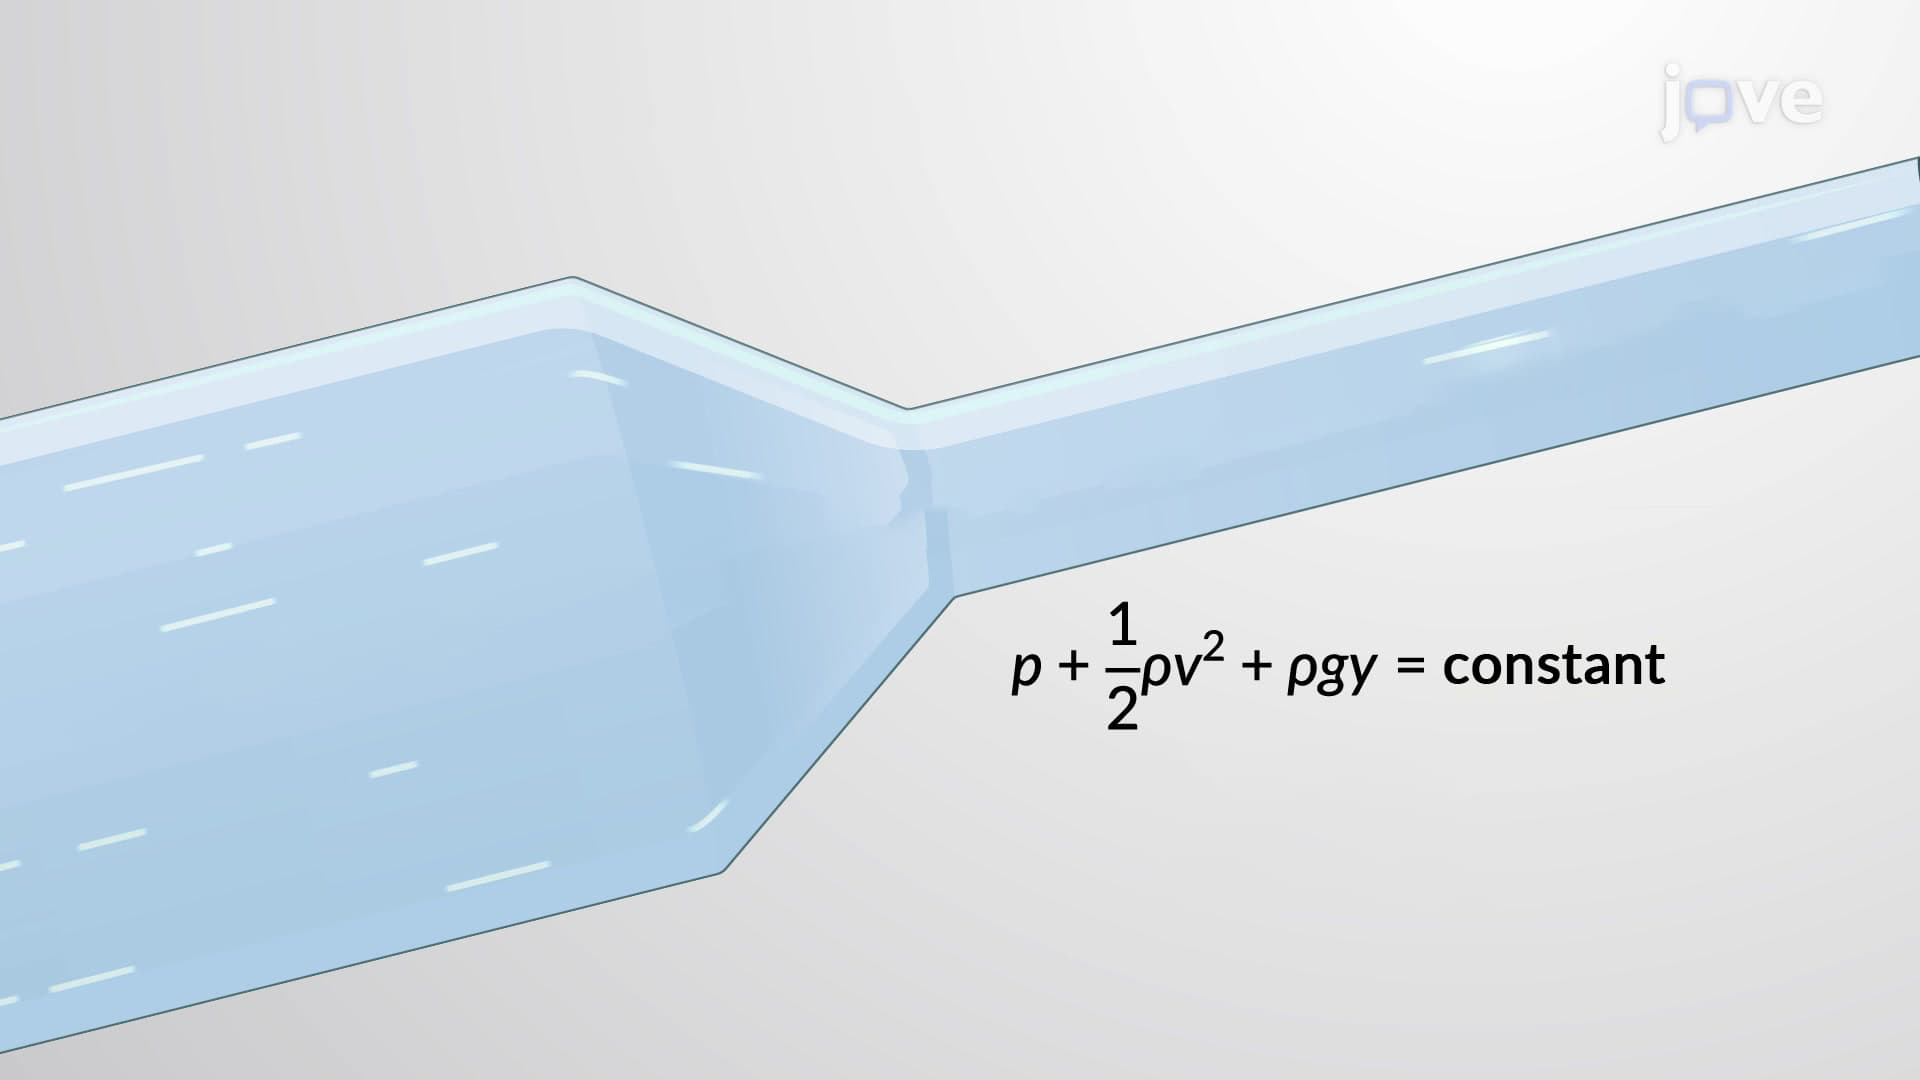
Bernoulli's Equation