Estimation of high dimensional mean regression in the absence of symmetry and light tail assumptions
Related Experiment Video
Updated: Mar 2, 2026
A Psychophysics Paradigm for the Collection and Analysis of Similarity Judgments
Published on: March 1, 2022
Jianqing Fan1, Quefeng Li1, Yuyan Wang1
1Department of Operations Research and Financial Engineering, Princeton University, Princeton, NJ 08544.

Abstract:
Data subject to heavy-tailed errors are commonly encountered in various scientific fields. To address this problem, procedures based on quantile regression and Least Absolute Deviation (LAD) regression have been developed in recent years. These methods essentially estimate the conditional median (or quantile) function. They can be very different from the conditional mean functions, especially when distributions are asymmetric and heteroscedastic. How can we efficiently estimate the mean regression functions in ultra-high dimensional setting with existence of only the second moment? To solve this problem, we propose a penalized Huber loss with diverging parameter to reduce biases created by the traditional Huber loss. Such a penalized robust approximate quadratic (RA-quadratic) loss will be called RA-Lasso. In the ultra-high dimensional setting, where the dimensionality can grow exponentially with the sample size, our results reveal that the RA-lasso estimator produces a consistent estimator at the same rate as the optimal rate under the light-tail situation. We further study the computational convergence of RA-Lasso and show that the composite gradient descent algorithm indeed produces a solution that admits the same optimal rate after sufficient iterations. As a byproduct, we also establish the concentration inequality for estimating population mean when there exists only the second moment. We compare RA-Lasso with other regularized robust estimators based on quantile regression and LAD regression. Extensive simulation studies demonstrate the satisfactory finite-sample performance of RA-Lasso.
Related Concept Videos
 01:52
Regression Toward the Mean
 01:22
Estimating Population Mean with Unknown Standard Deviation
William S. Gosset (1876–1937) of the...
 01:16
Estimating Population Mean with Known Standard Deviation
The confidence interval estimate will have the form as follows:
(point estimate - error bound, point estimate +...
 01:10
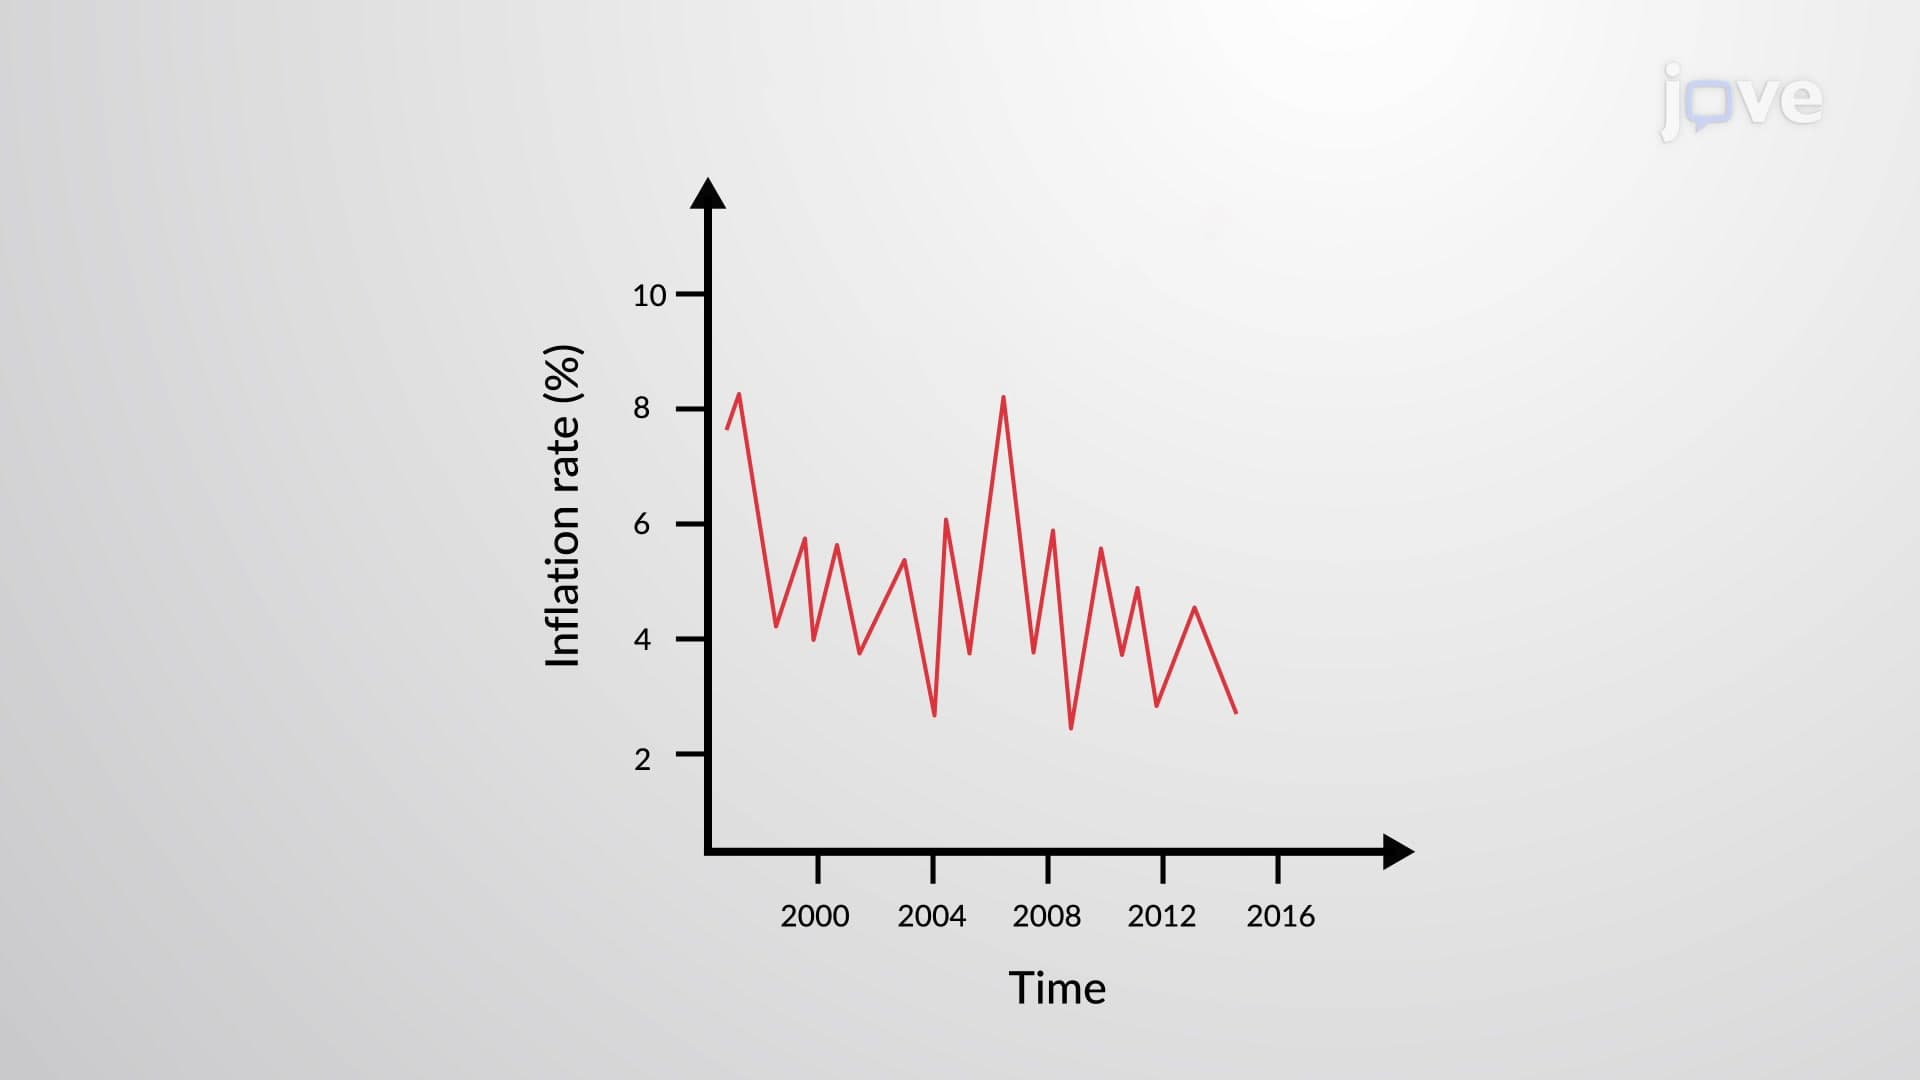
Trimmed Mean
Although certain measures of central tendency are not sensitive to outliers, there are alternative versions of the mean that get around the...
 01:06
What are Estimates?
The estimate for the mean of a sample is denoted by ͞x, whereas the mean of the population is designated as μ. Further, parameters such...
 01:06
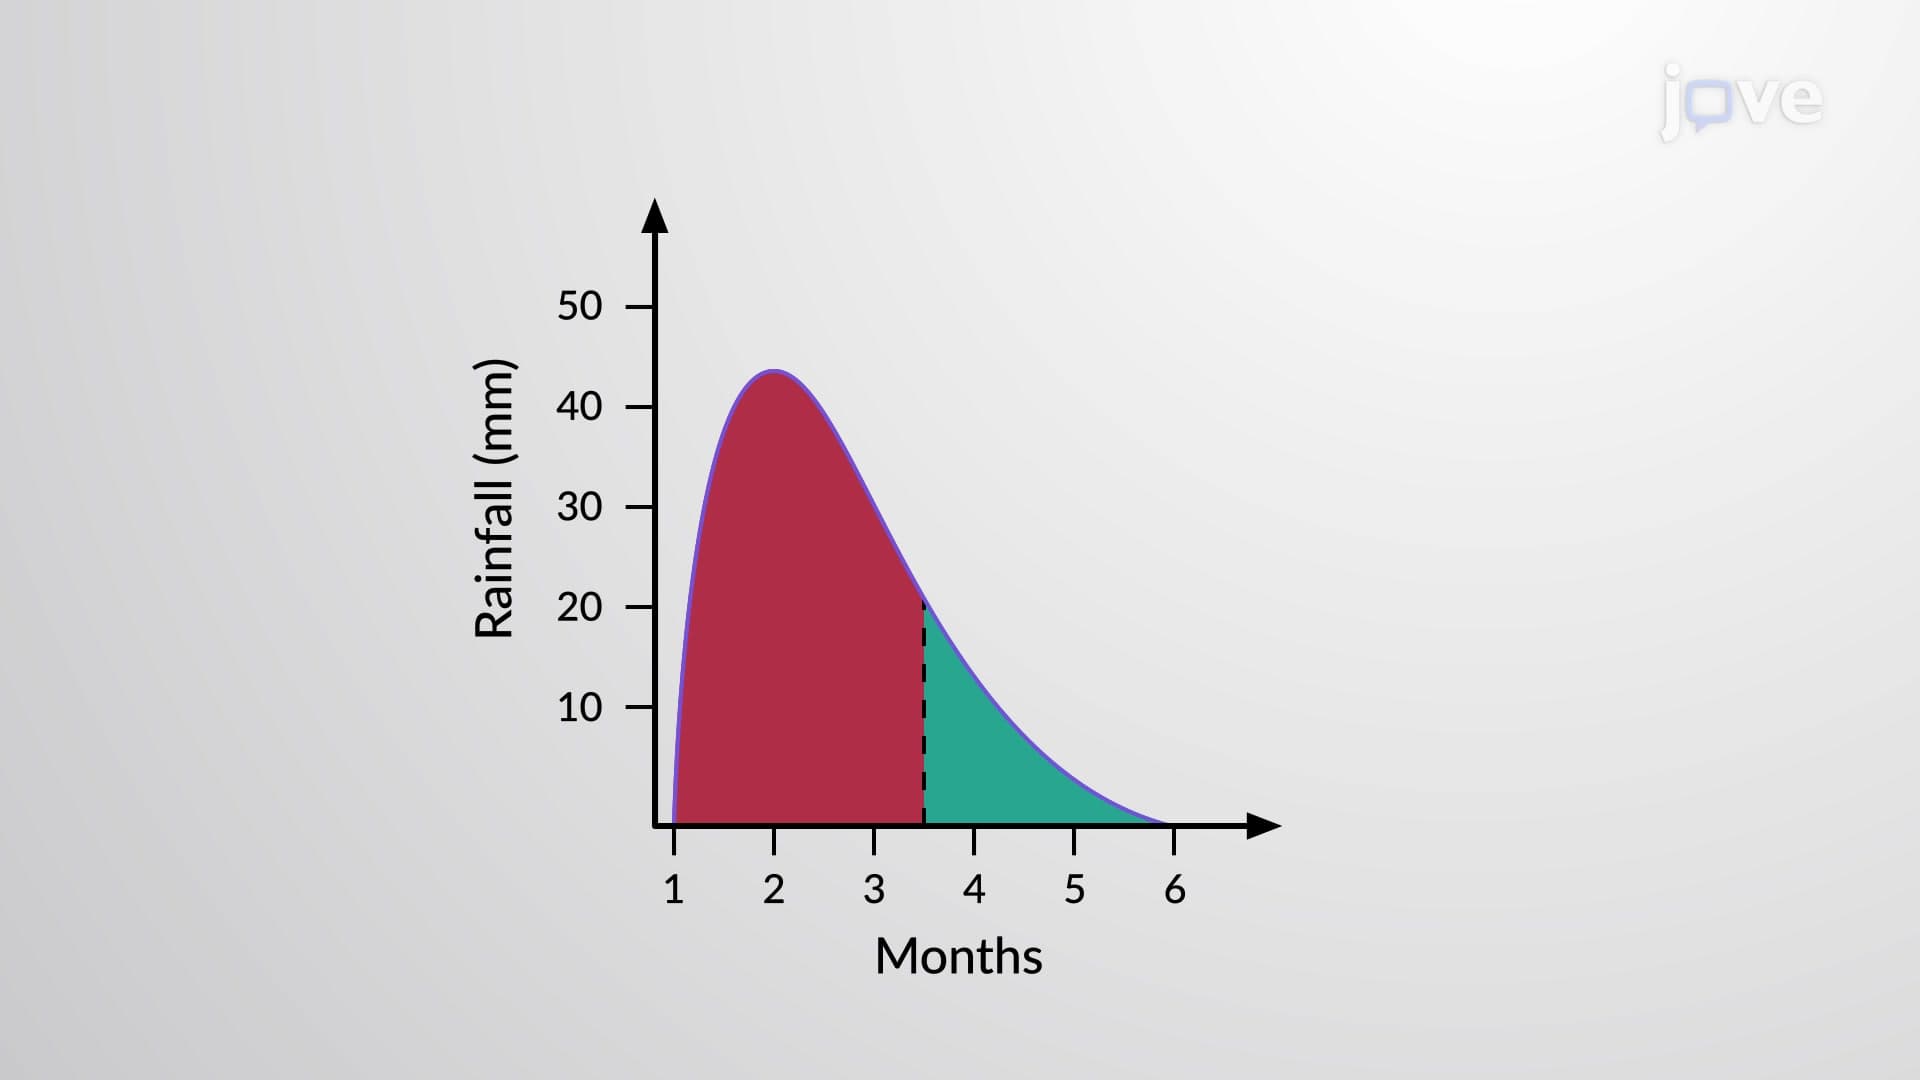
Skewness
The longer the tail of the plot on one side, the more skewed it is. The skewness of a data set’s values suggests that the measures of central tendency...