
Detection of statistical asymmetries in non-stationary sign time series: Analysis of foreign exchange data
Arthur Matsuo Yamashita Rios de Sousa1, Hideki Takayasu2,3, Misako Takayasu1,3
1Department of Mathematical and Computing Science, School of Computing, Tokyo Institute of Technology, Midori-ku, Yokohama, Japan.

Abstract:
We extend the concept of statistical symmetry as the invariance of a probability distribution under transformation to analyze binary sign time series data of price difference from the foreign exchange market. We model segments of the sign time series as Markov sequences and apply a local hypothesis test to evaluate the symmetries of independence and time reversion in different periods of the market. For the test, we derive the probability of a binary Markov process to generate a given set of number of symbol pairs. Using such analysis, we could not only segment the time series according the different behaviors but also characterize the segments in terms of statistical symmetries. As a particular result, we find that the foreign exchange market is essentially time reversible but this symmetry is broken when there is a strong external influence.
More Related Videos
 10:46
A Method of Trigonometric Modelling of Seasonal Variation Demonstrated with Multiple Sclerosis Relapse Data
Published on: December 9, 2015
 08:42
Measurement of the Directional Information Flow in fNIRS-Hyperscanning Data using the Partial Wavelet Transform Coherence Method
Published on: September 3, 2021
Related Concept Videos
 01:17
Sign Test for Matched Pairs
To conduct the sign test, we first calculate the differences in...
 01:21
Properties of Fourier series II
A function f(t) is...
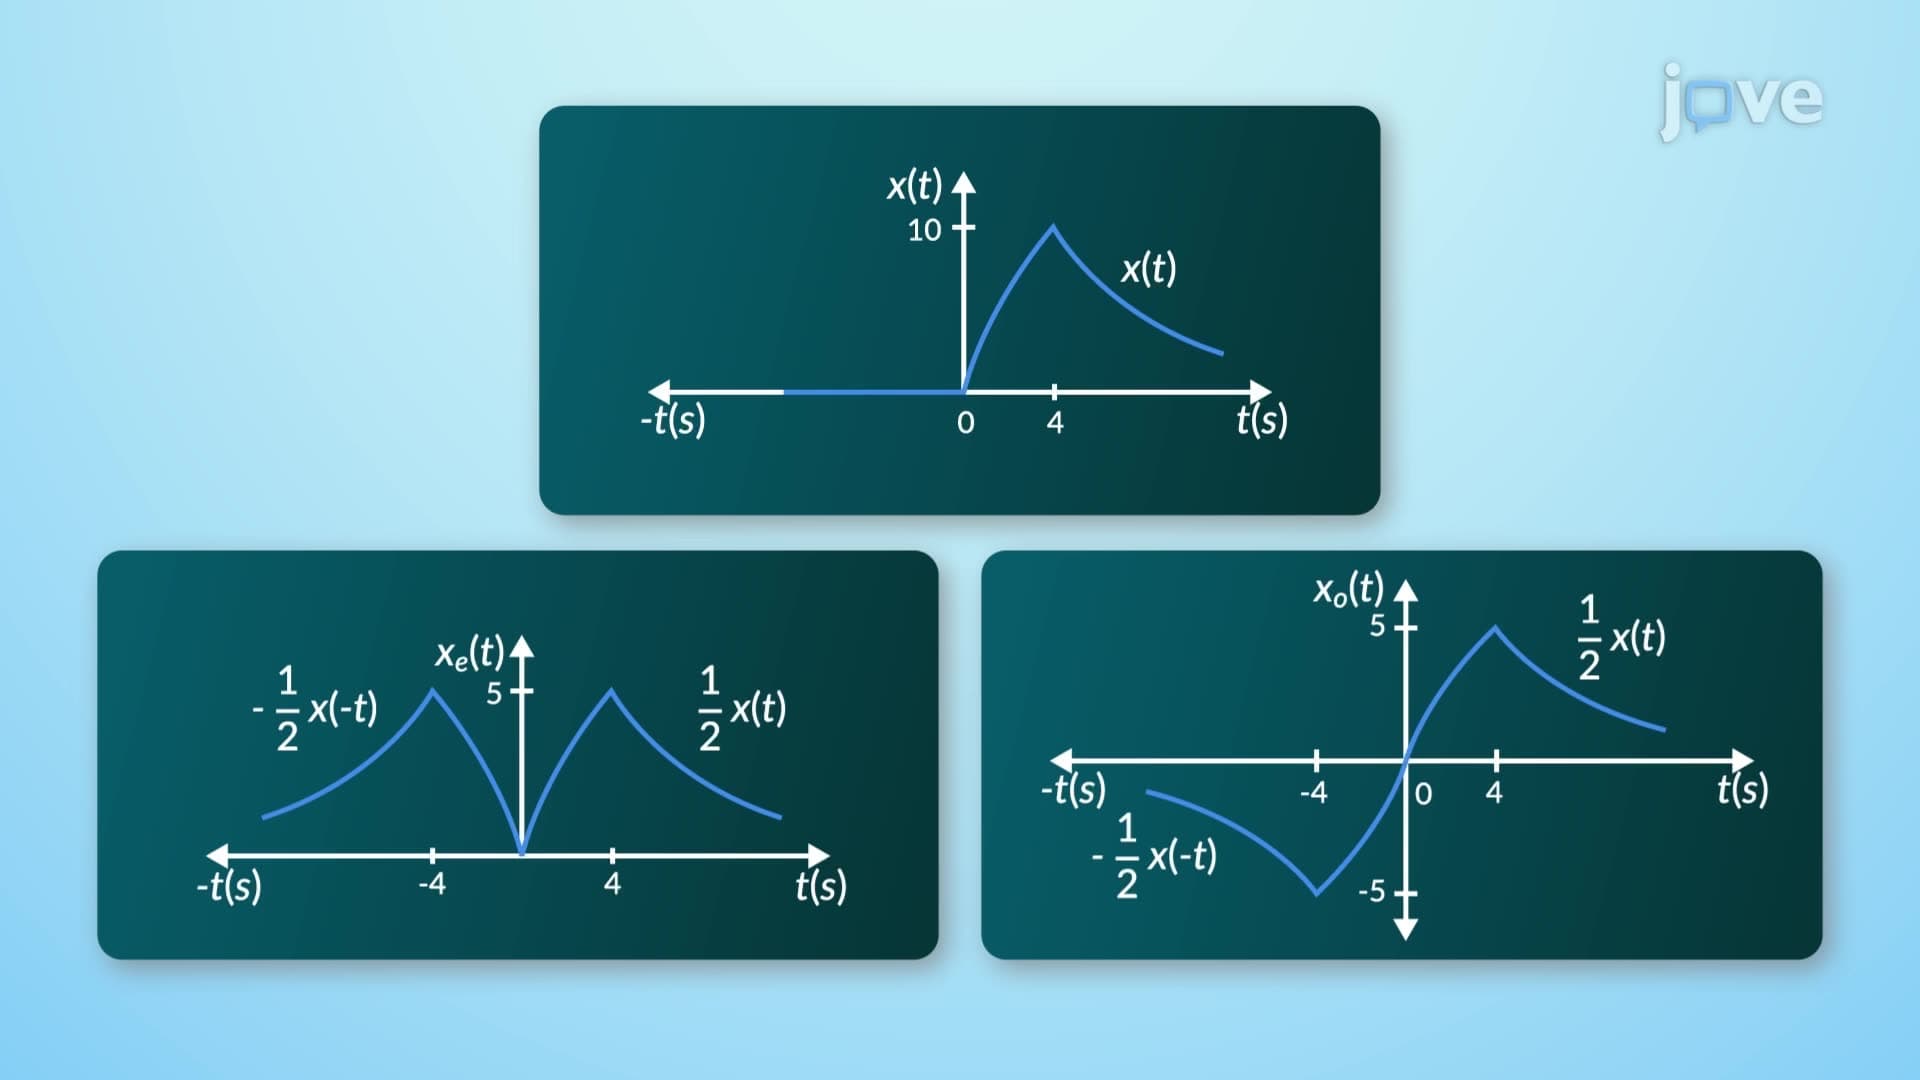 01:17
Even and Odd Signals
 01:00
Detection of Gross Error: The Q Test
 01:10
Introduction to the Sign Test
 01:20
Properties of Fourier series I