Related Experiment Video
Updated: Feb 19, 2026


Selecting Multiple Biomarker Subsets with Similarly Effective Binary Classification Performances
Published on: October 11, 2018
Efficient ℓ0 -norm feature selection based on augmented and penalized minimization
Xiang Li1, Shanghong Xie2, Donglin Zeng3
1Statistics and Decision Sciences, Janssen Research & Development, LLC, Raritan, NJ, USA.

Abstract:
Advances in high-throughput technologies in genomics and imaging yield unprecedentedly large numbers of prognostic biomarkers. To accommodate the scale of biomarkers and study their association with disease outcomes, penalized regression is often used to identify important biomarkers. The ideal variable selection procedure would search for the best subset of predictors, which is equivalent to imposing an ℓ0 -penalty on the regression coefficients. Since this optimization is a nondeterministic polynomial-time hard (NP-hard) problem that does not scale with number of biomarkers, alternative methods mostly place smooth penalties on the regression parameters, which lead to computationally feasible optimization problems. However, empirical studies and theoretical analyses show that convex approximation of ℓ0 -norm (eg, ℓ1 ) does not outperform their ℓ0 counterpart. The progress for ℓ0 -norm feature selection is relatively slower, where the main methods are greedy algorithms such as stepwise regression or orthogonal matching pursuit. Penalized regression based on regularizing ℓ0 -norm remains much less explored in the literature. In this work, inspired by the recently popular augmenting and data splitting algorithms including alternating direction method of multipliers, we propose a 2-stage procedure for ℓ0 -penalty variable selection, referred to as augmented penalized minimization-L0 (APM-L0 ). The APM-L0 targets ℓ0 -norm as closely as possible while keeping computation tractable, efficient, and simple, which is achieved by iterating between a convex regularized regression and a simple hard-thresholding estimation. The procedure can be viewed as arising from regularized optimization with truncated ℓ1 norm. Thus, we propose to treat regularization parameter and thresholding parameter as tuning parameters and select based on cross-validation. A 1-step coordinate descent algorithm is used in the first stage to significantly improve computational efficiency. Through extensive simulation studies and real data application, we demonstrate superior performance of the proposed method in terms of selection accuracy and computational speed as compared to existing methods. The proposed APM-L0 procedure is implemented in the R-package APML0.


Related Concept Videos
 01:11
Residuals and Least-Squares Property
If the observed data point lies above the line, the residual is positive, and the line underestimates the actual data value for y. If the observed data point lies below the line, the residual is negative, and the line overestimates the actual data value for y.
The process of fitting the best-fit...
 01:52
Regression Toward the Mean
 01:29
Application of Linearization and Approximation
 01:02
Quantifying and Rejecting Outliers: The Grubbs Test
 01:29
Mechanistic Models: Compartment Models in Algorithms for Numerical Problem Solving
In individual population analyses, different algorithms are employed, such as Cauchy's method, which uses a...
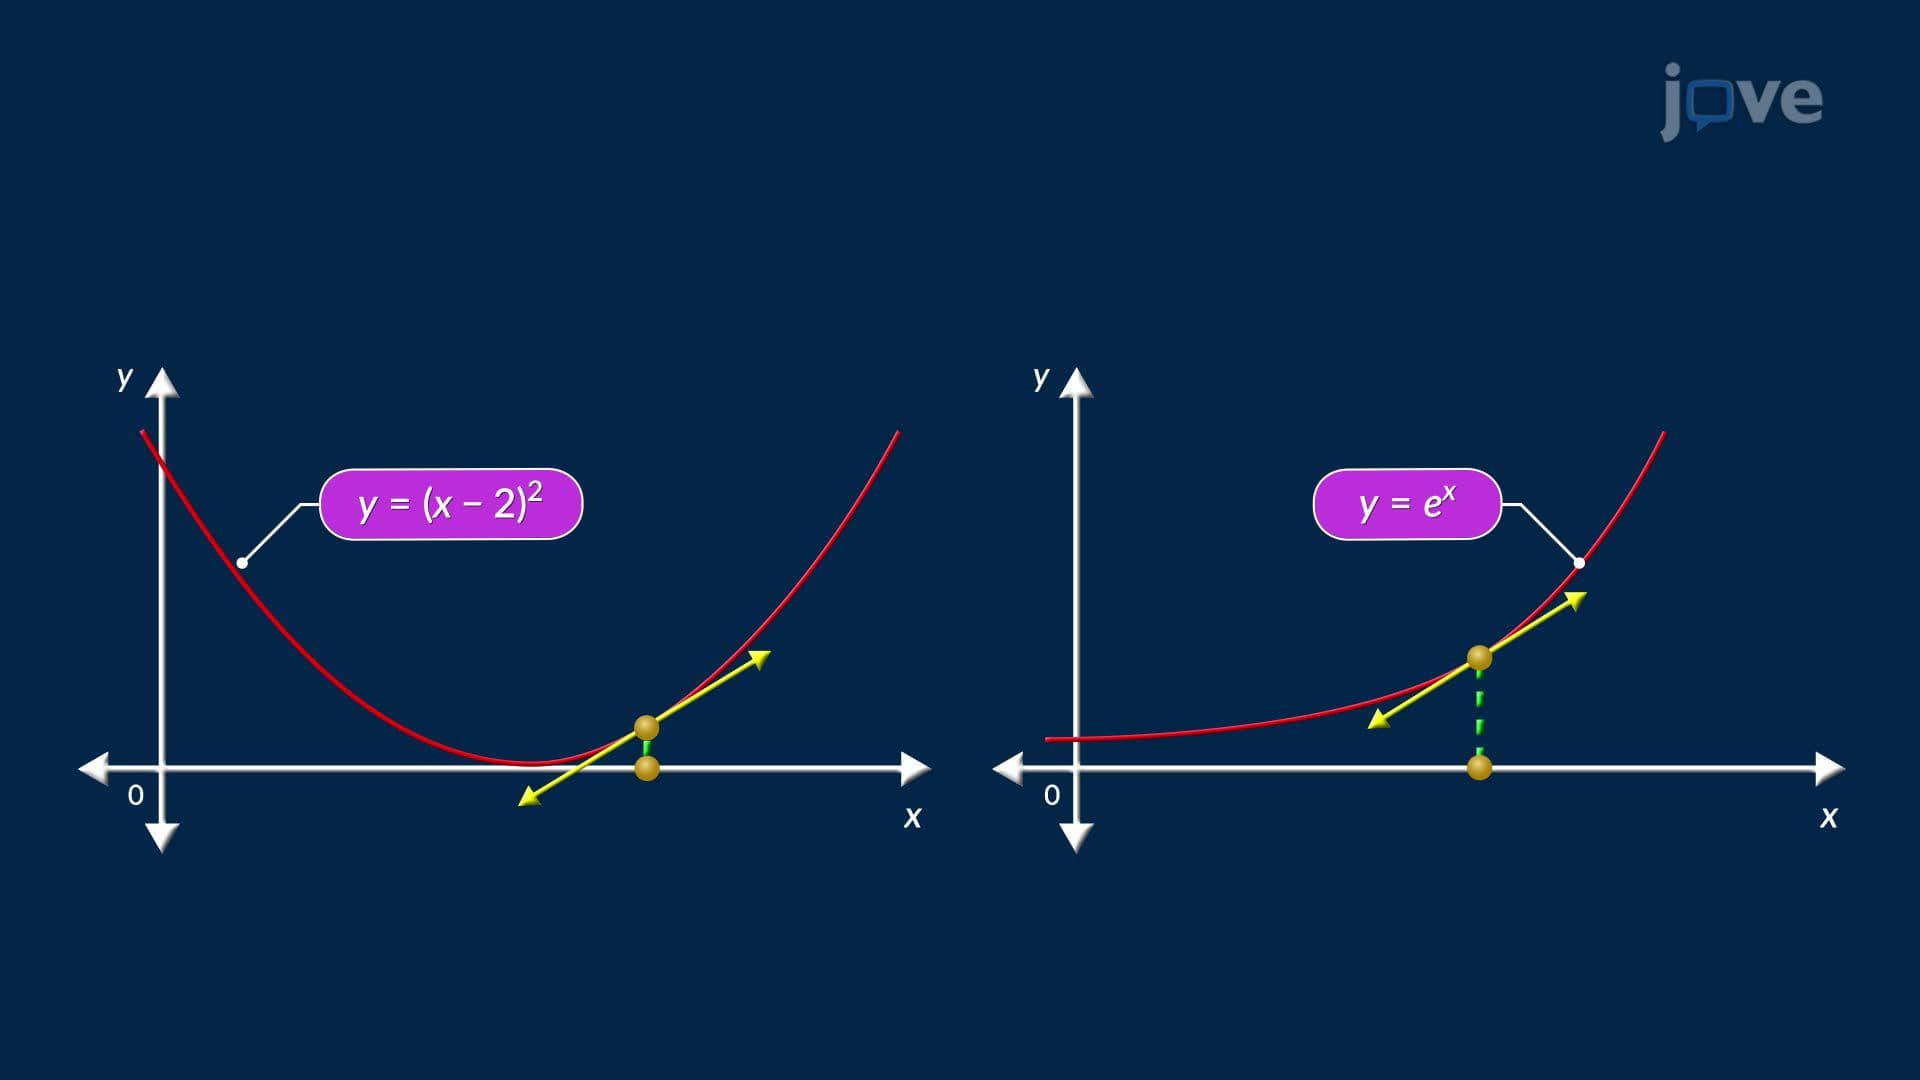 01:26
Linearization and Approximation