Related Experiment Video
Updated: Feb 17, 2026
Age-dependent Dynamics of Locomotion in Caenorhabditis elegans: A Lyapunov Exponent Analysis
Published on: September 23, 2025
On stochastic differential equations with arbitrarily slow convergence rates for strong approximation in two space
Máté Gerencsér1, Arnulf Jentzen2, Diyora Salimova2
1Institute of Science and Technology Austria, Klosterneuburg, Austria.

Abstract:
In a recent article (Jentzen et al. 2016 Commun. Math. Sci.14, 1477-1500 (doi:10.4310/CMS.2016.v14.n6.a1)), it has been established that, for every arbitrarily slow convergence speed and every natural number d∈{4,5,…}, there exist d-dimensional stochastic differential equations with infinitely often differentiable and globally bounded coefficients such that no approximation method based on finitely many observations of the driving Brownian motion can converge in absolute mean to the solution faster than the given speed of convergence. In this paper, we strengthen the above result by proving that this slow convergence phenomenon also arises in two (d=2) and three (d=3) space dimensions.
Related Concept Videos
 01:21
Linear Approximation in Time Domain
For a simple pendulum with a mass evenly distributed along its length and the center of mass located at half the pendulum's length,...
 01:06
Divergence and Stokes' Theorems
 01:21
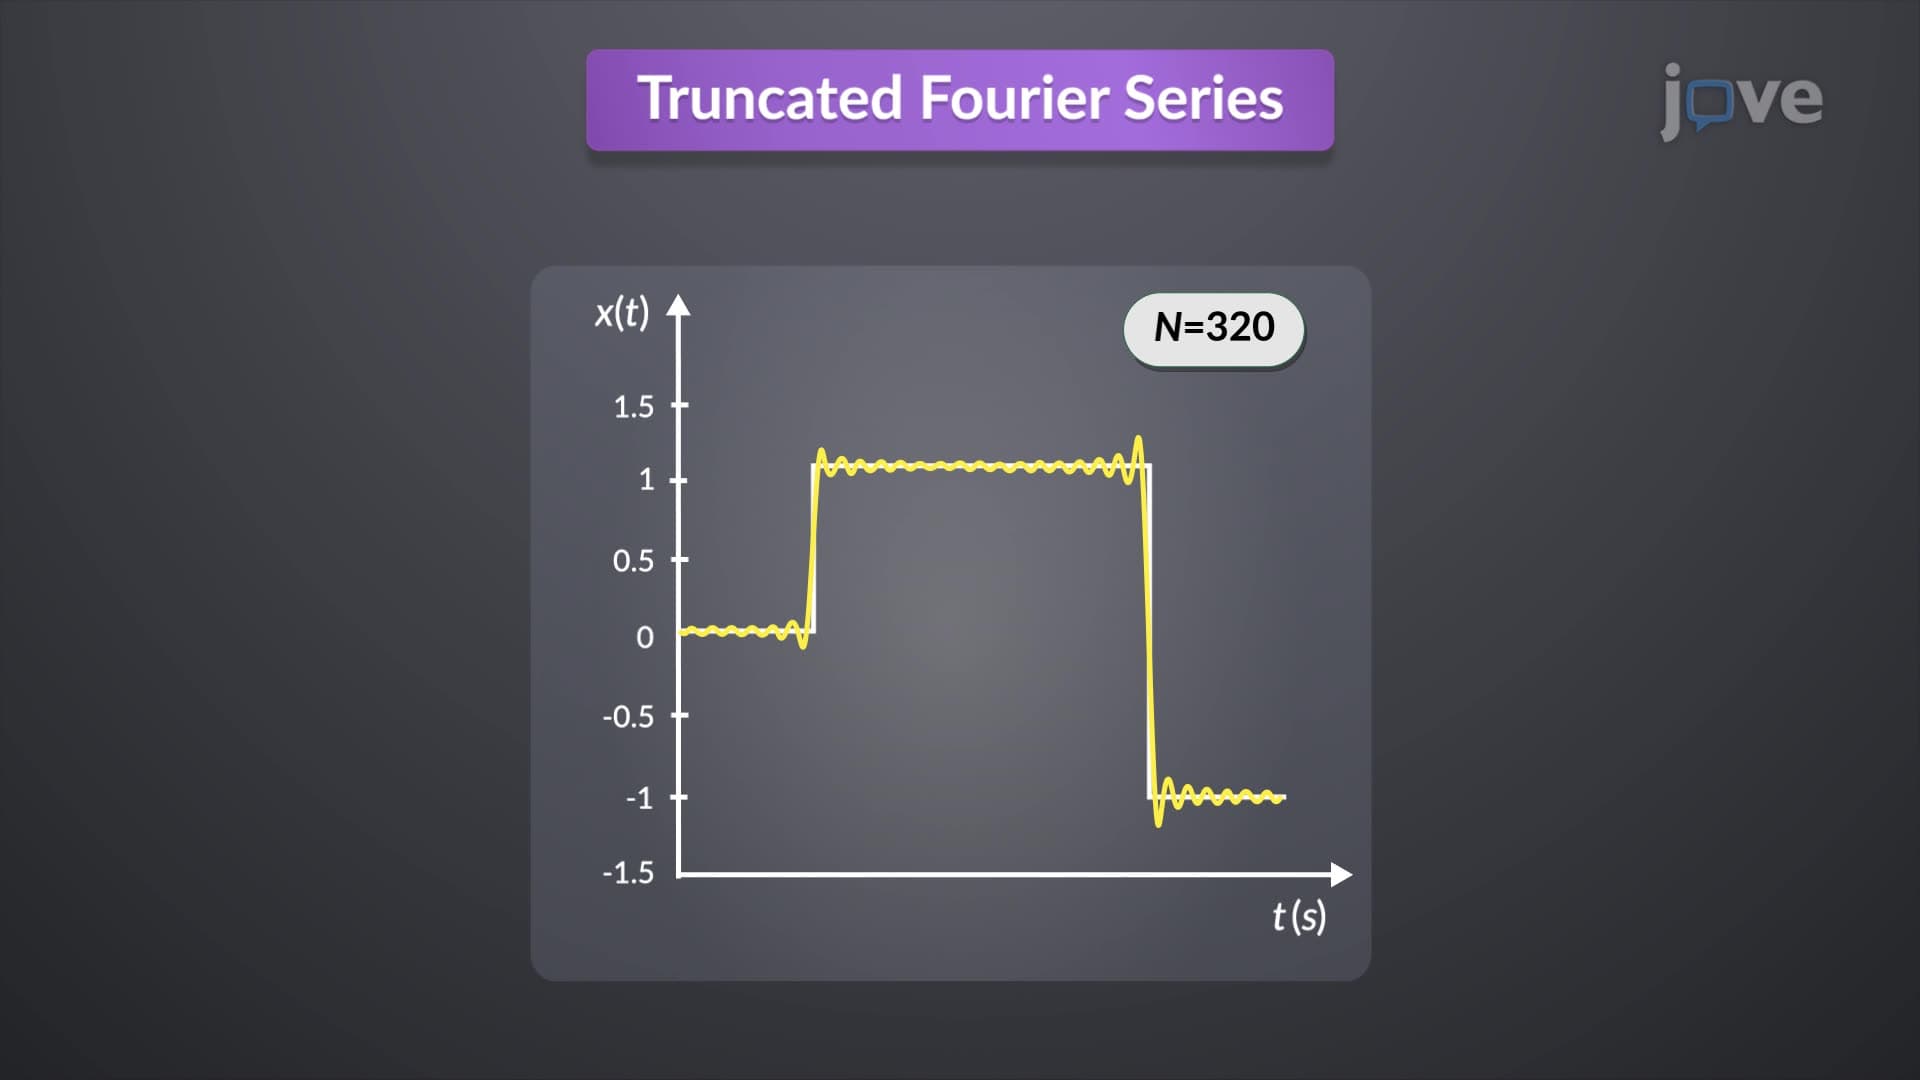
Convergence of Fourier Series
The Gibbs phenomenon refers to the persistent oscillations and overshoots that occur near discontinuities...
 01:19
Limits with Oscillating Discontinuities
 01:29
Improper Integrals: Infinite Intervals
 01:27
Linear Differential Equations