Related Experiment Video
Updated: Feb 6, 2026

Programmed Electrical Stimulation in Mice
Published on: May 26, 2010
An accelerating algorithm for globally solving nonconvex quadratic programming
Li Ge1,2, Sanyang Liu1
11School of Mathematics and Statistics, Xidian University, Xi'an, China.

Abstract:
To globally solve a nonconvex quadratic programming problem, this paper presents an accelerating linearizing algorithm based on the framework of the branch-and-bound method. By utilizing a new linear relaxation approach, the initial quadratic programming problem is reduced to a sequence of linear relaxation programming problems, which is used to obtain a lower bound of the optimal value of this problem. Then, by using the deleting operation of the investigated regions, we can improve the convergent speed of the proposed algorithm. The proposed algorithm is proved to be convergent, and some experiments are reported to show higher feasibility and efficiency of the proposed algorithm.
More Related Videos
Related Concept Videos
 01:29
Quadratic Equations
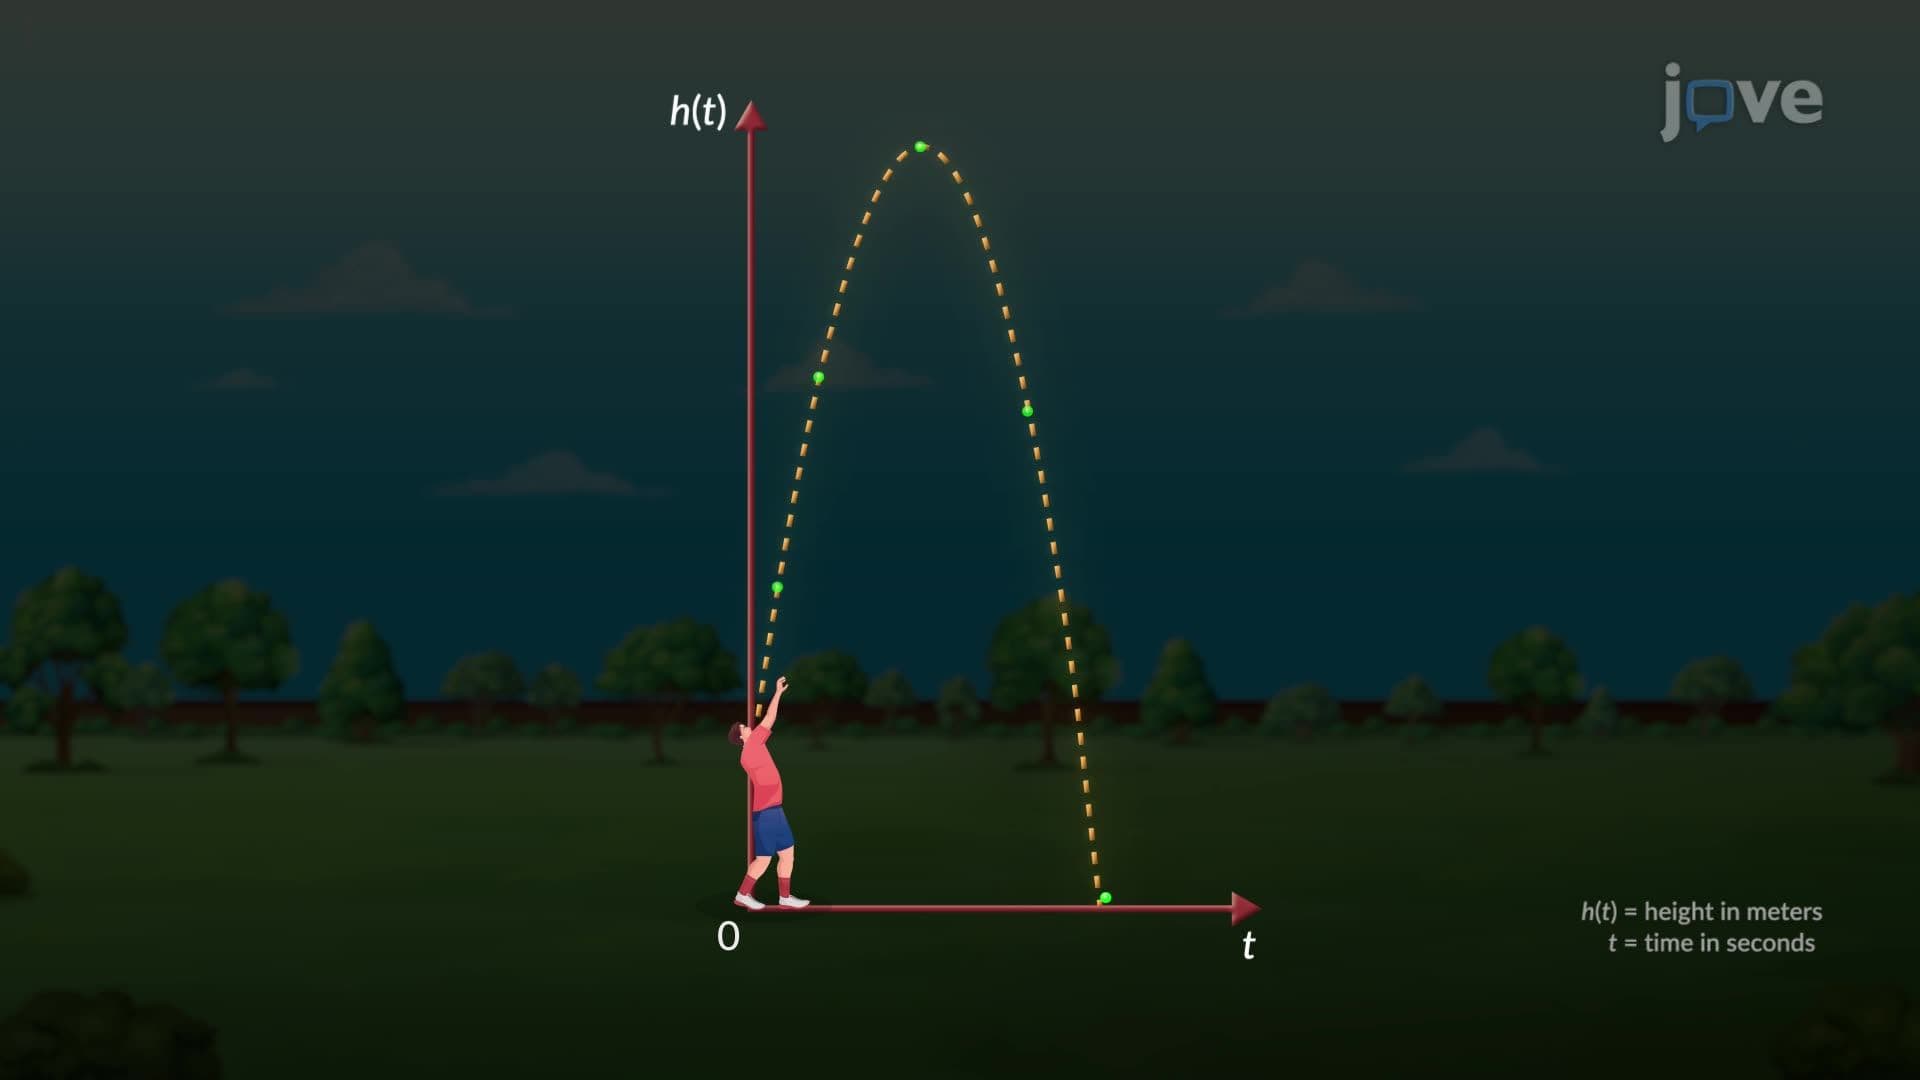 01:23
Quadratic Models
 01:29
Mechanistic Models: Compartment Models in Algorithms for Numerical Problem Solving
In individual population analyses, different algorithms are employed, such as Cauchy's method, which uses a...
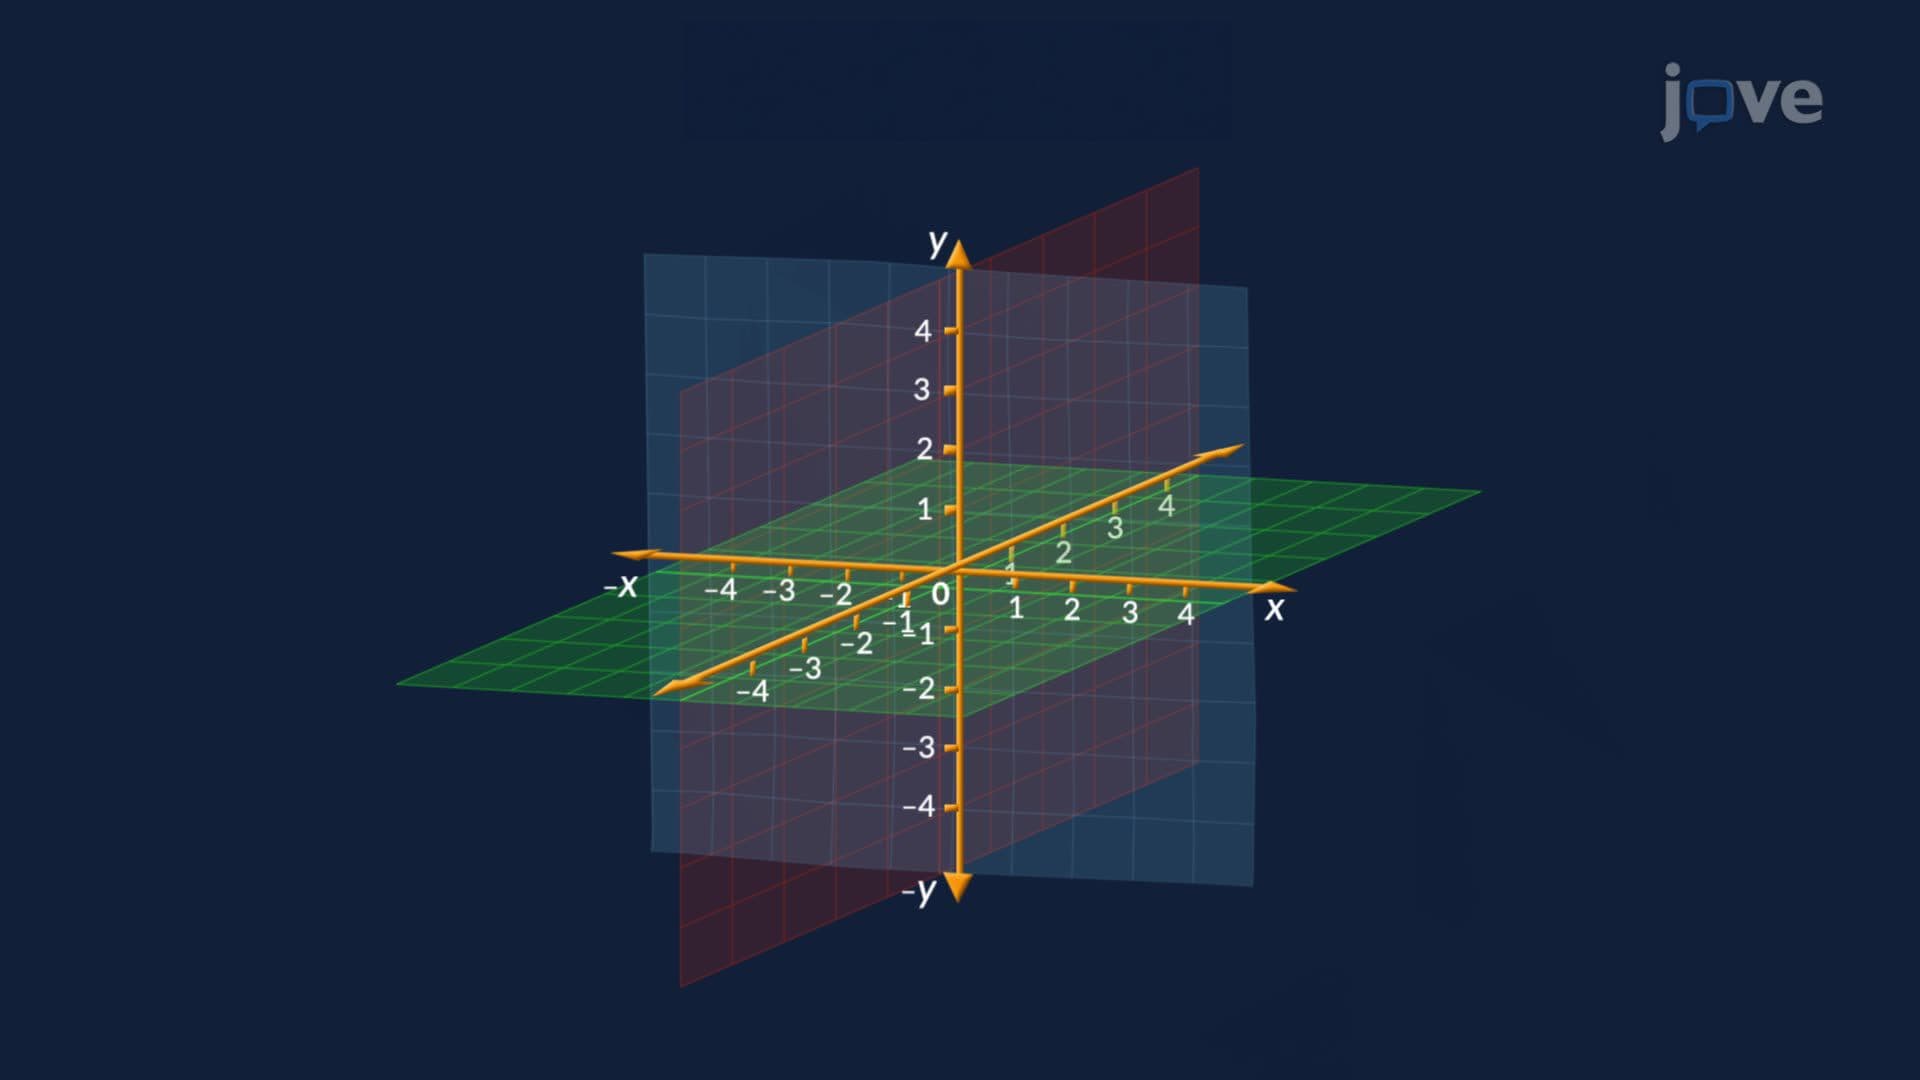 01:29
Quadratic Equations in the Complex Number System
 01:50
Global Climate Change
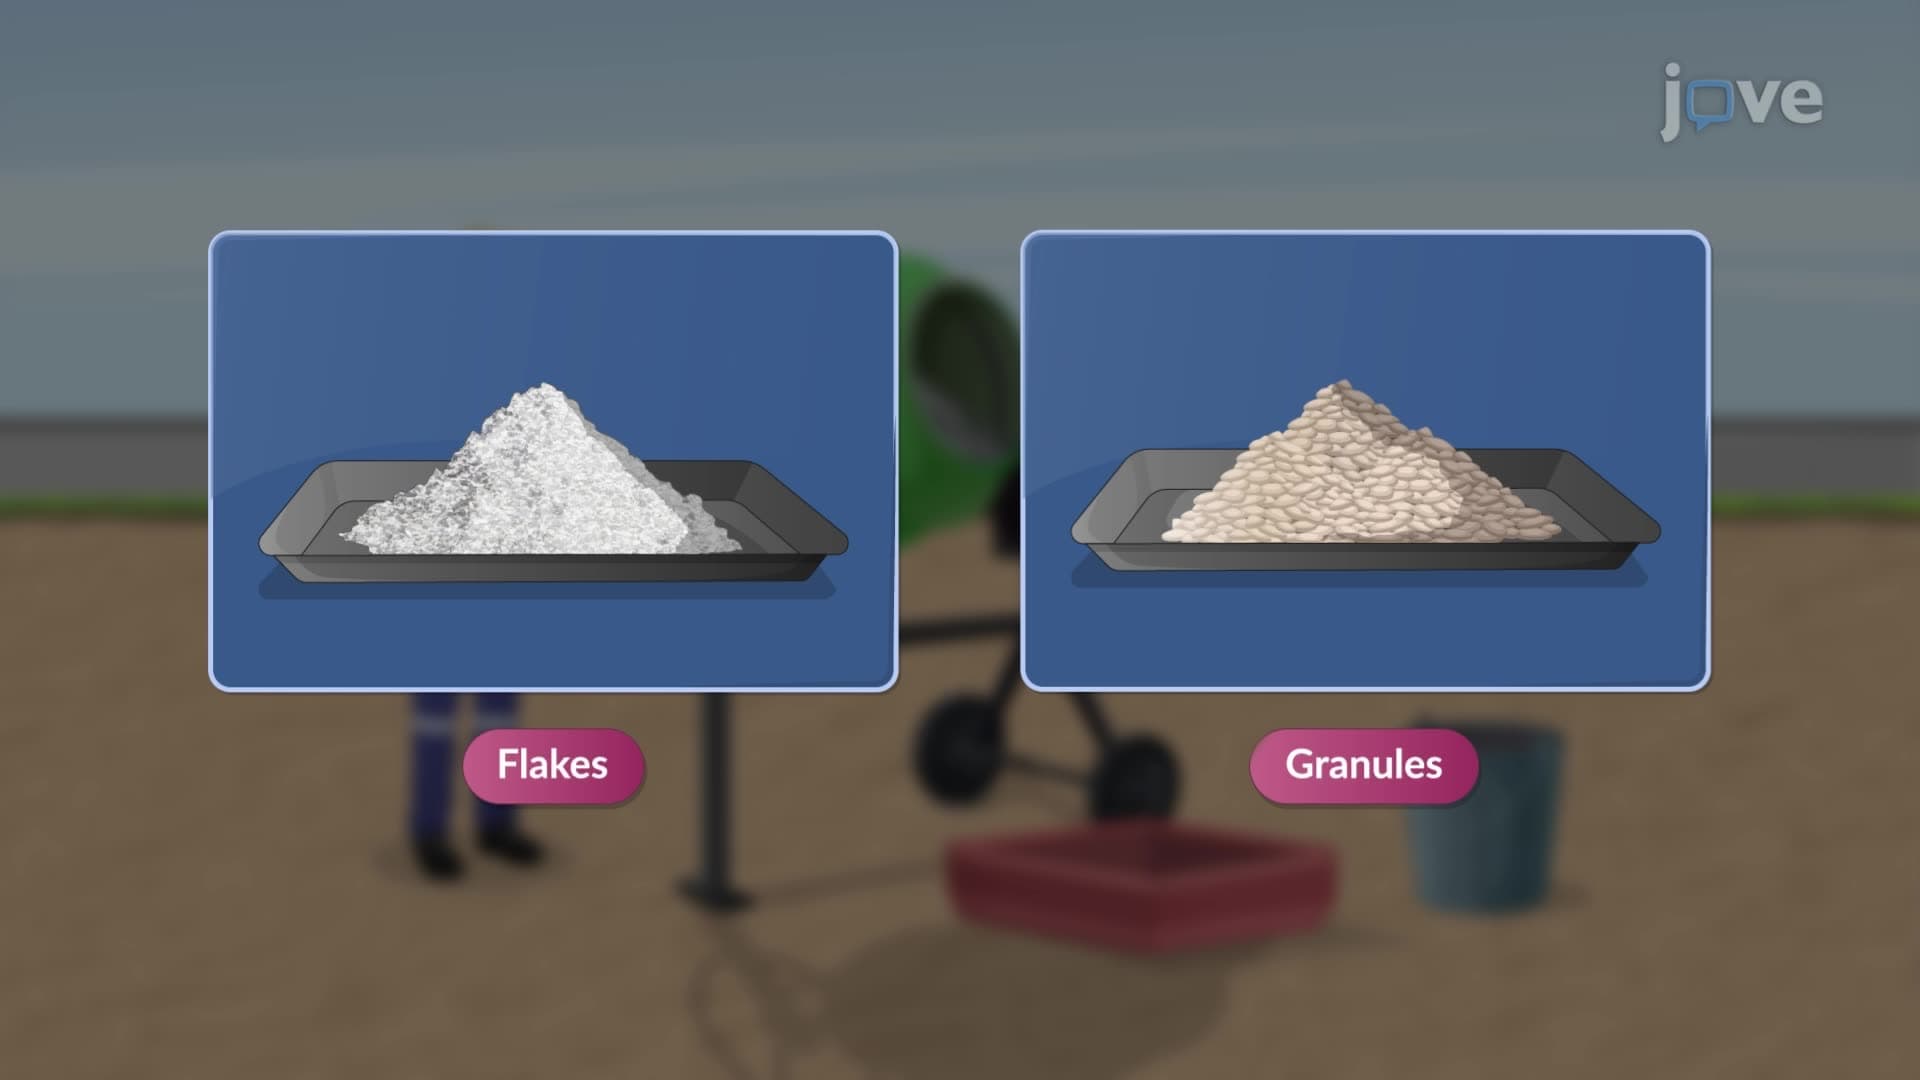 01:17
Accelerators
The effectiveness of calcium chloride can...