Related Experiment Video
Updated: Feb 5, 2026

Area-based Image Analysis Algorithm for Quantification of Macrophage-fibroblast Cocultures
Published on: February 15, 2022
Accelerating MCMC algorithms
Christian P Robert1,2, Víctor Elvira3,4, Nick Tawn2
1Université Paris Dauphine PSL Research University Paris France.

Abstract:
Markov chain Monte Carlo algorithms are used to simulate from complex statistical distributions by way of a local exploration of these distributions. This local feature avoids heavy requests on understanding the nature of the target, but it also potentially induces a lengthy exploration of this target, with a requirement on the number of simulations that grows with the dimension of the problem and with the complexity of the data behind it. Several techniques are available toward accelerating the convergence of these Monte Carlo algorithms, either at the exploration level (as in tempering, Hamiltonian Monte Carlo and partly deterministic methods) or at the exploitation level (with Rao-Blackwellization and scalable methods). This article is categorized under: Statistical and Graphical Methods of Data Analysis > Markov Chain Monte Carlo (MCMC)Algorithms and Computational Methods > AlgorithmsStatistical and Graphical Methods of Data Analysis > Monte Carlo Methods.
Related Concept Videos
 01:17
Accelerators
The effectiveness of calcium chloride can...
 01:12
Trial and Error and Algorithm
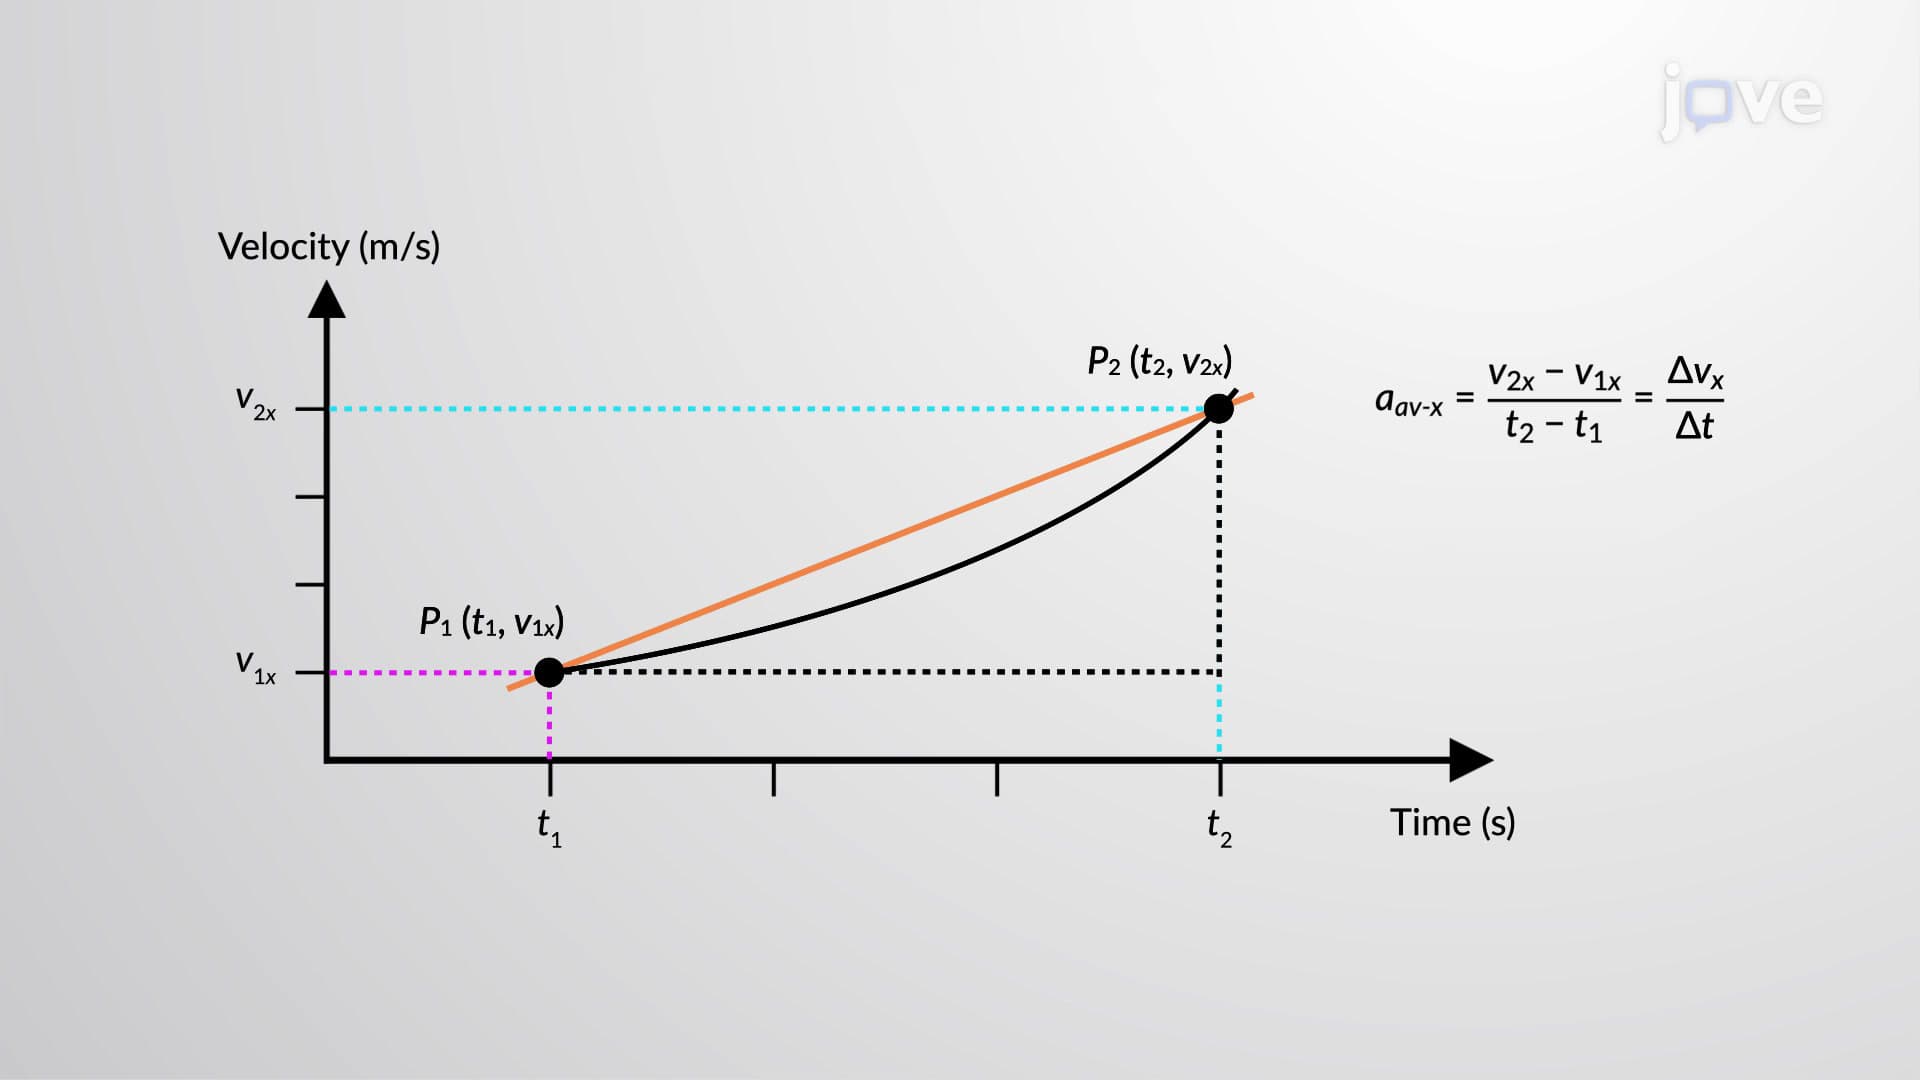 01:30
Average Acceleration
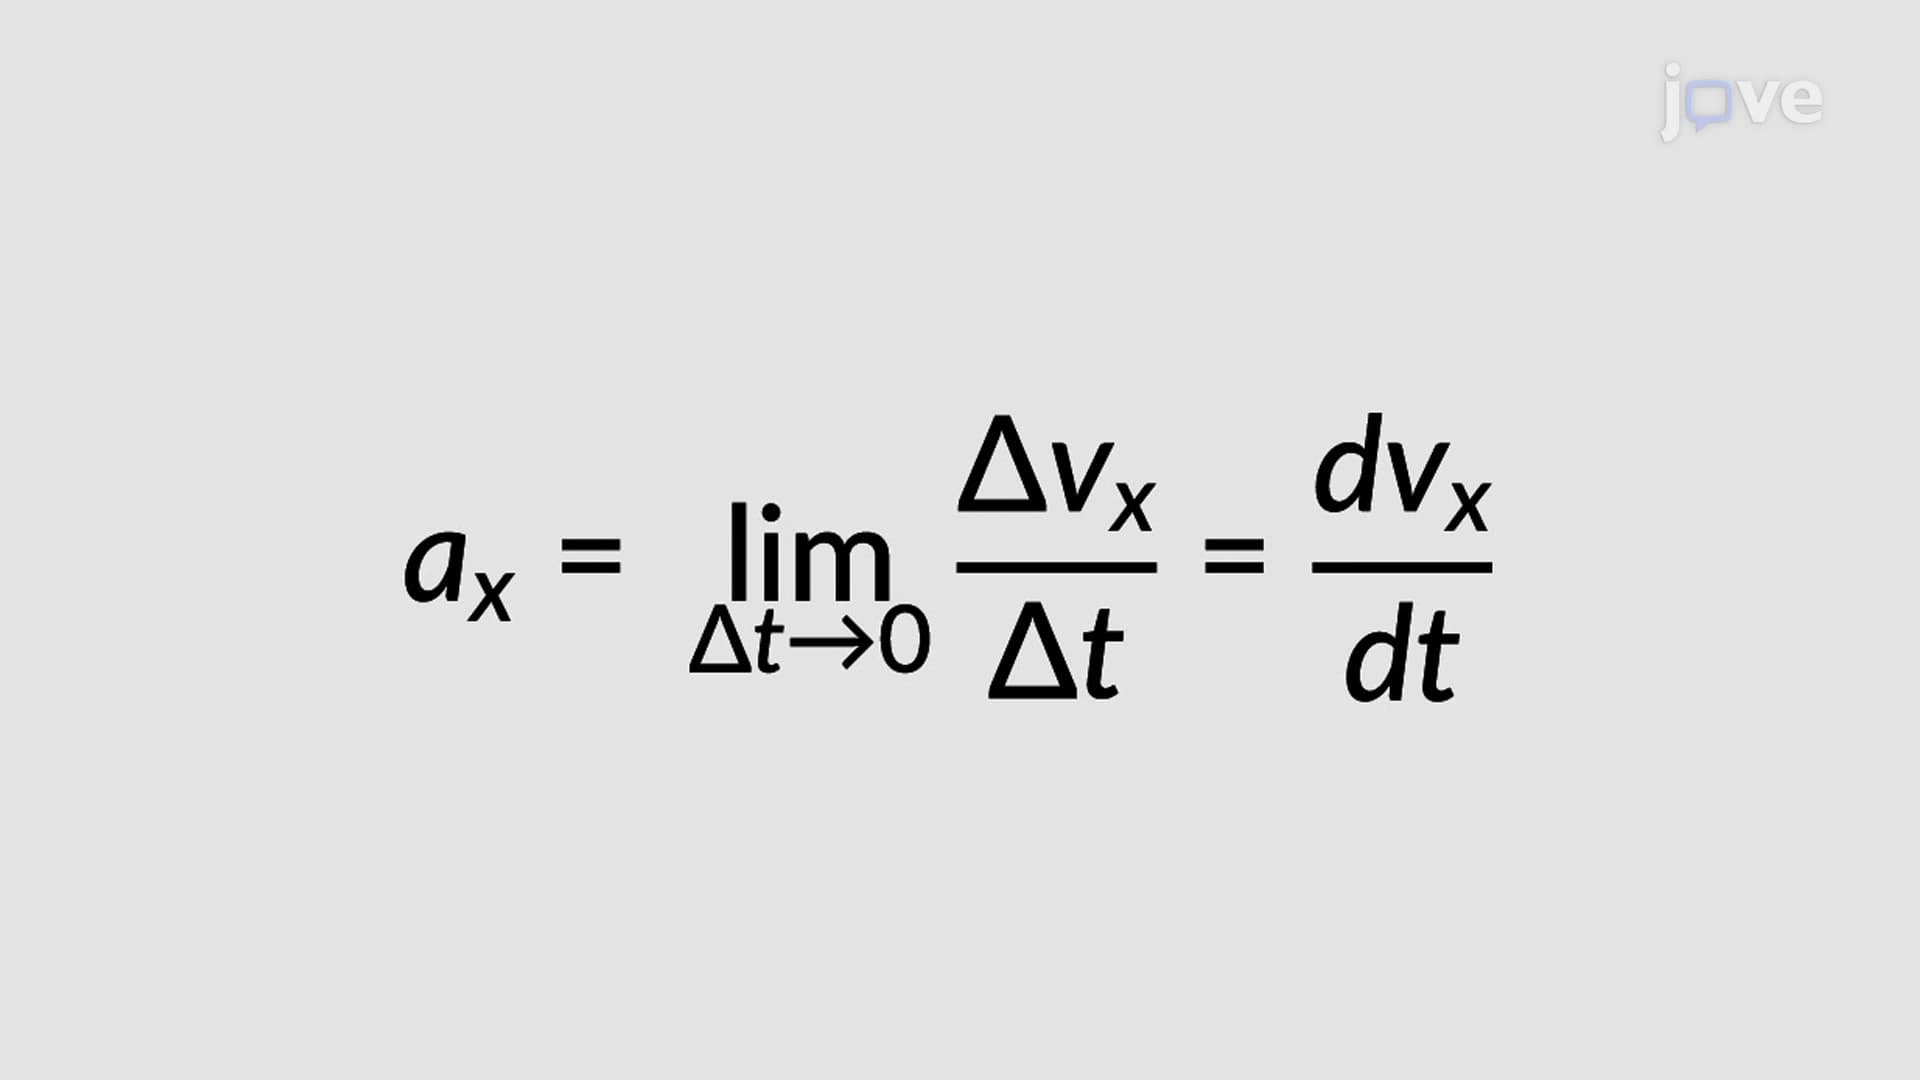 01:16
Instantaneous Acceleration
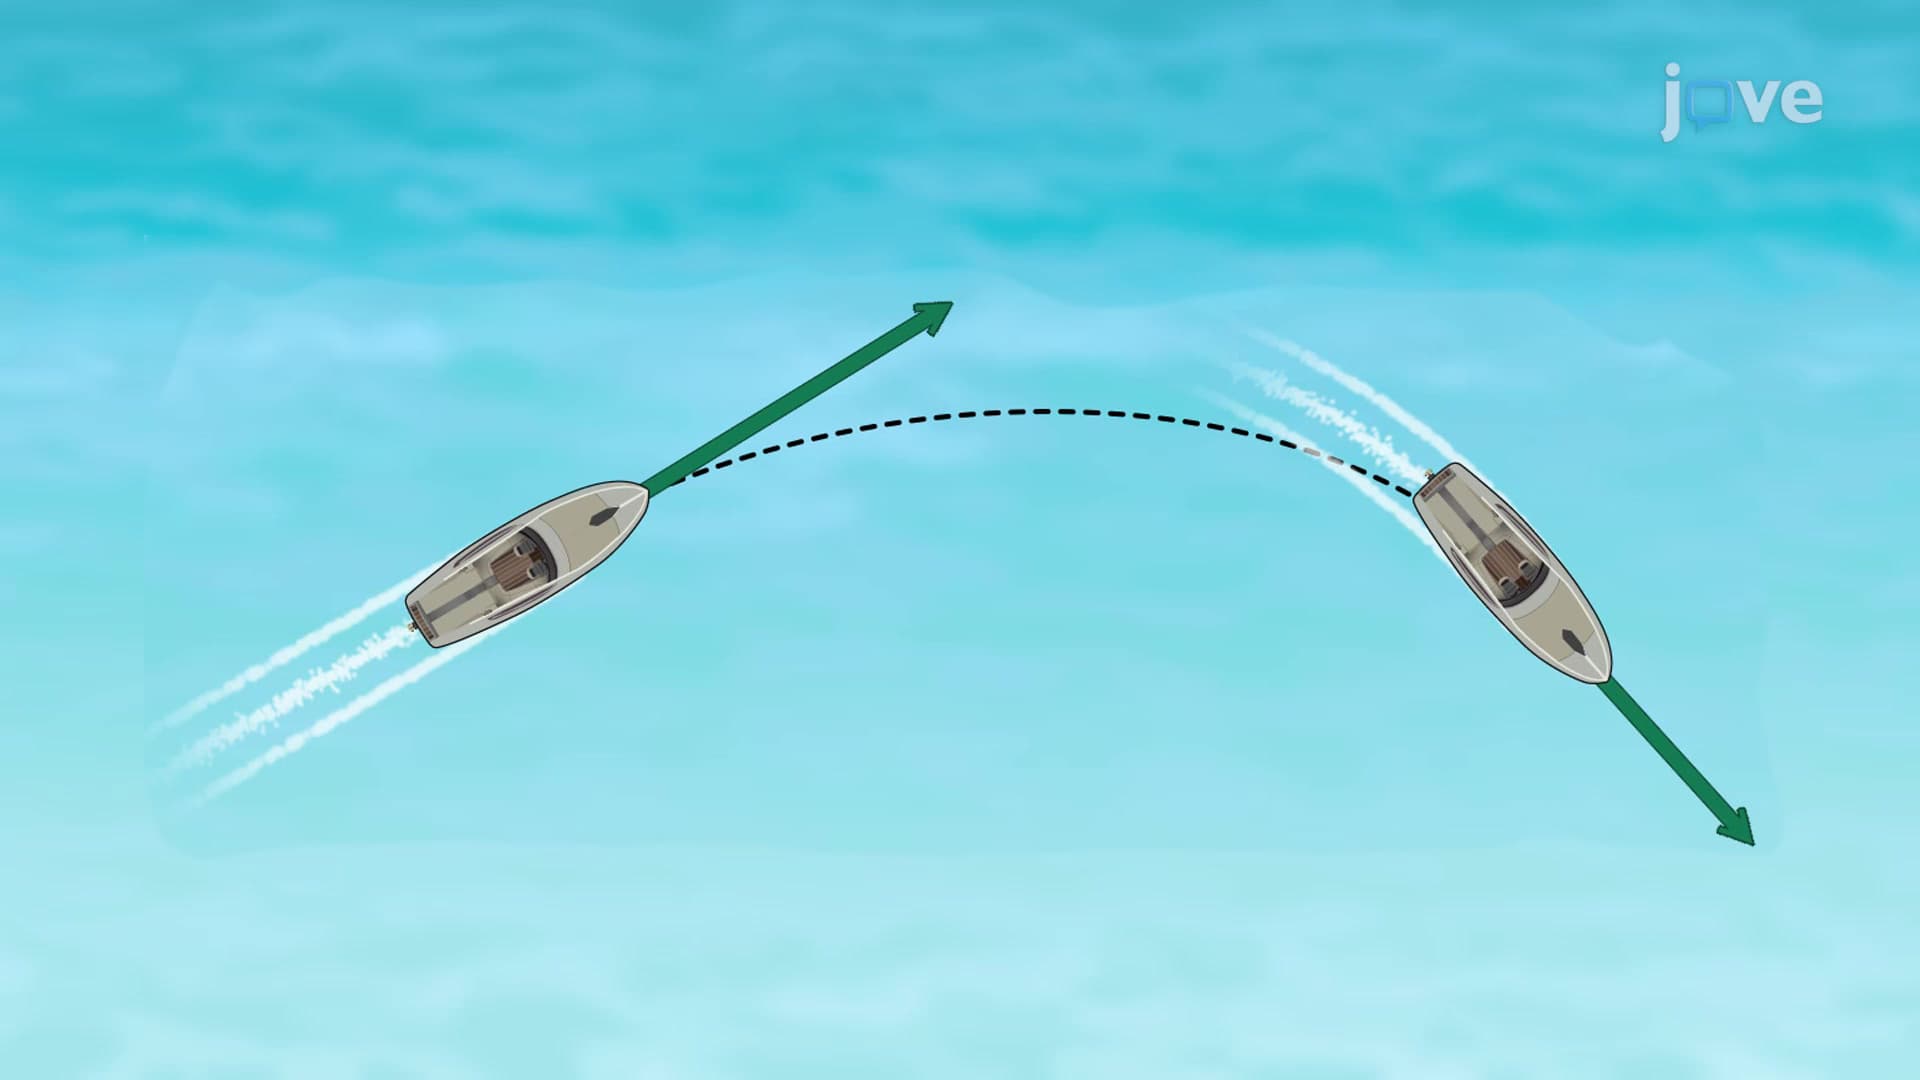 01:30
Acceleration Vectors
 01:17
Accelerating Fluids
The motion of the liquid within this infinitesimal cylinder is considered to obtain the pressure difference. Three vertical forces act on this liquid: