Related Experiment Video
Updated: Feb 3, 2026
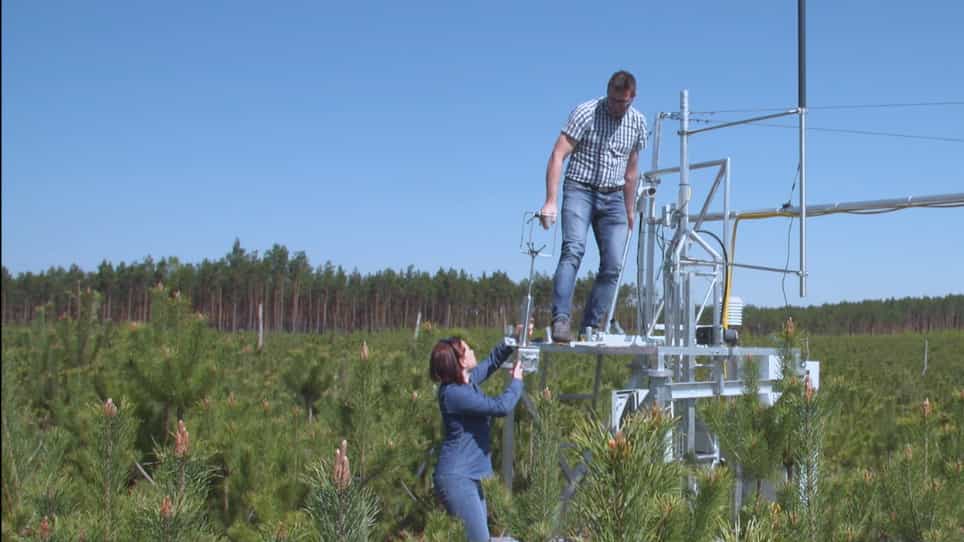

Measurements of CO2 Fluxes at Non-Ideal Eddy Covariance Sites
Published on: June 24, 2019
Robust estimation of high-dimensional covariance and precision matrices
Marco Avella-Medina1, Heather S Battey2, Jianqing Fan3
1Sloan School of Management, Massachusetts Institute of Technology, 30 Memorial Drive, Cambridge, Massachusetts 02142, U.S.A.

Abstract:
High-dimensional data are often most plausibly generated from distributions with complex structure and leptokurtosis in some or all components. Covariance and precision matrices provide a useful summary of such structure, yet the performance of popular matrix estimators typically hinges upon a sub-Gaussianity assumption. This paper presents robust matrix estimators whose performance is guaranteed for a much richer class of distributions. The proposed estimators, under a bounded fourth moment assumption, achieve the same minimax convergence rates as do existing methods under a sub-Gaussianity assumption. Consistency of the proposed estimators is also established under the weak assumption of bounded 2 + ε moments for ε ∈ (0, 2). The associated convergence rates depend on ε.
Related Concept Videos
 01:29
Theory of Attribution II: Kelley's Covariation Theory
 01:06
What are Estimates?
The estimate for the mean of a sample is denoted by ͞x, whereas the mean of the population is designated as μ. Further, parameters such...
 03:37
Uncertainty in Measurement: Accuracy and Precision
 01:20
Estimation of k and VD of Aminoglycosides
 01:52
Accuracy and Precision
 03:40
Dimensional Analysis
Conversion Factors and Dimensional Analysis
The unit...