Related Experiment Video
Updated: Feb 2, 2026

Sample Drift Correction Following 4D Confocal Time-lapse Imaging
Published on: April 12, 2014
Numerical path integral calculation of the probability function and exit time: an application to non-gradient drift
Fernando Mora1,2, Pierre Coullet2, Sergio Rica1
1Facultad de Ingeniería y Ciencias and UAI Physics Center, Universidad Adolfo Ibáñez, Santiago, Chile.

Abstract:
We provide numerical solutions based on the path integral representation of stochastic processes for non-gradient drift Langevin forces in the presence of noise, to follow the temporal evolution of the probability density function and to compute exit times even for arbitrary noise. We compare the results with theoretical calculations, obtaining excellent agreement in the weak noise limit.This article is part of the theme issue 'Dissipative structures in matter out of equilibrium: from chemistry, photonics and biology (part 2)'.
Related Concept Videos
 01:27
Applications of Integration to Probability Density Functions
 01:24
Numerical Calculations
The solution to a problem is obtained using different methods. While manually solving algebraic symbols is one of the most common methods, the graphical method is often preferred. Computers...
 01:22
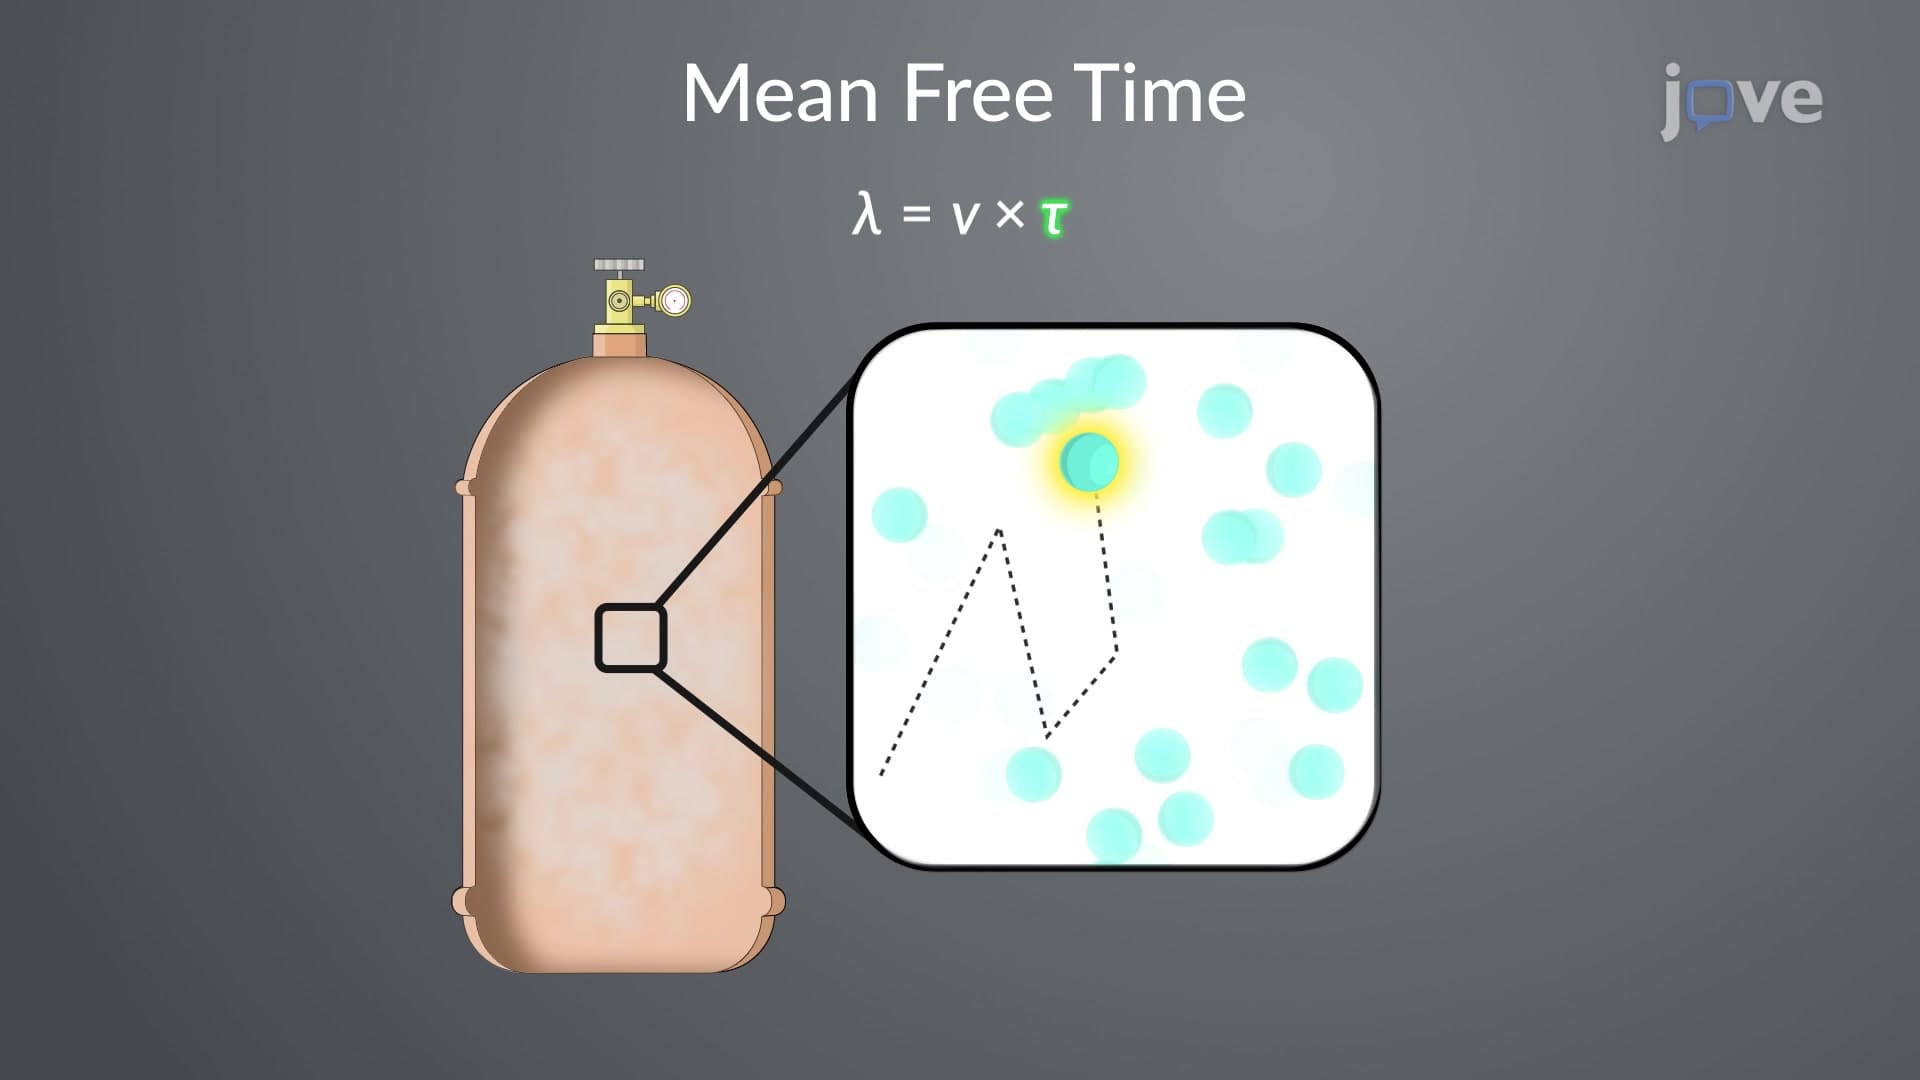
Mean free path and Mean free time
 01:49
Probability Laws
 01:27
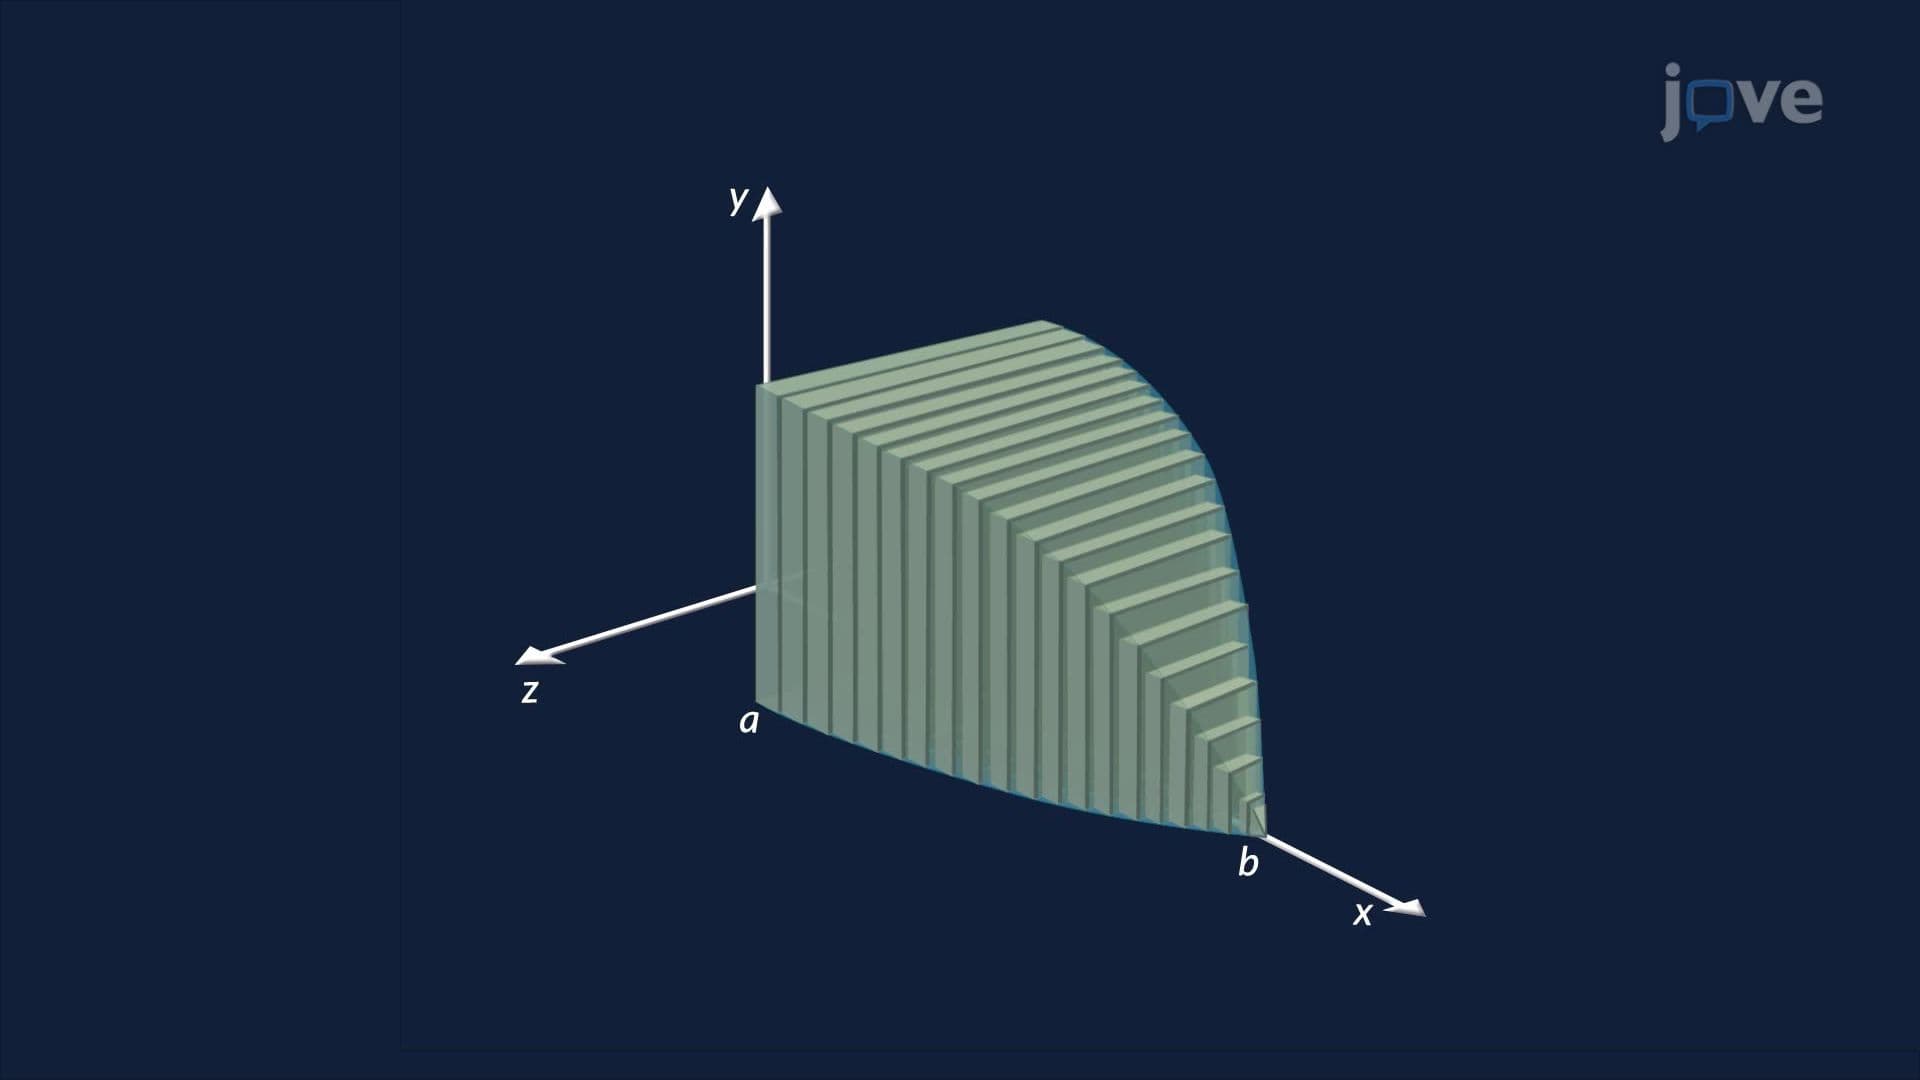
Calculation of Volume of Solids by Integration
 01:26
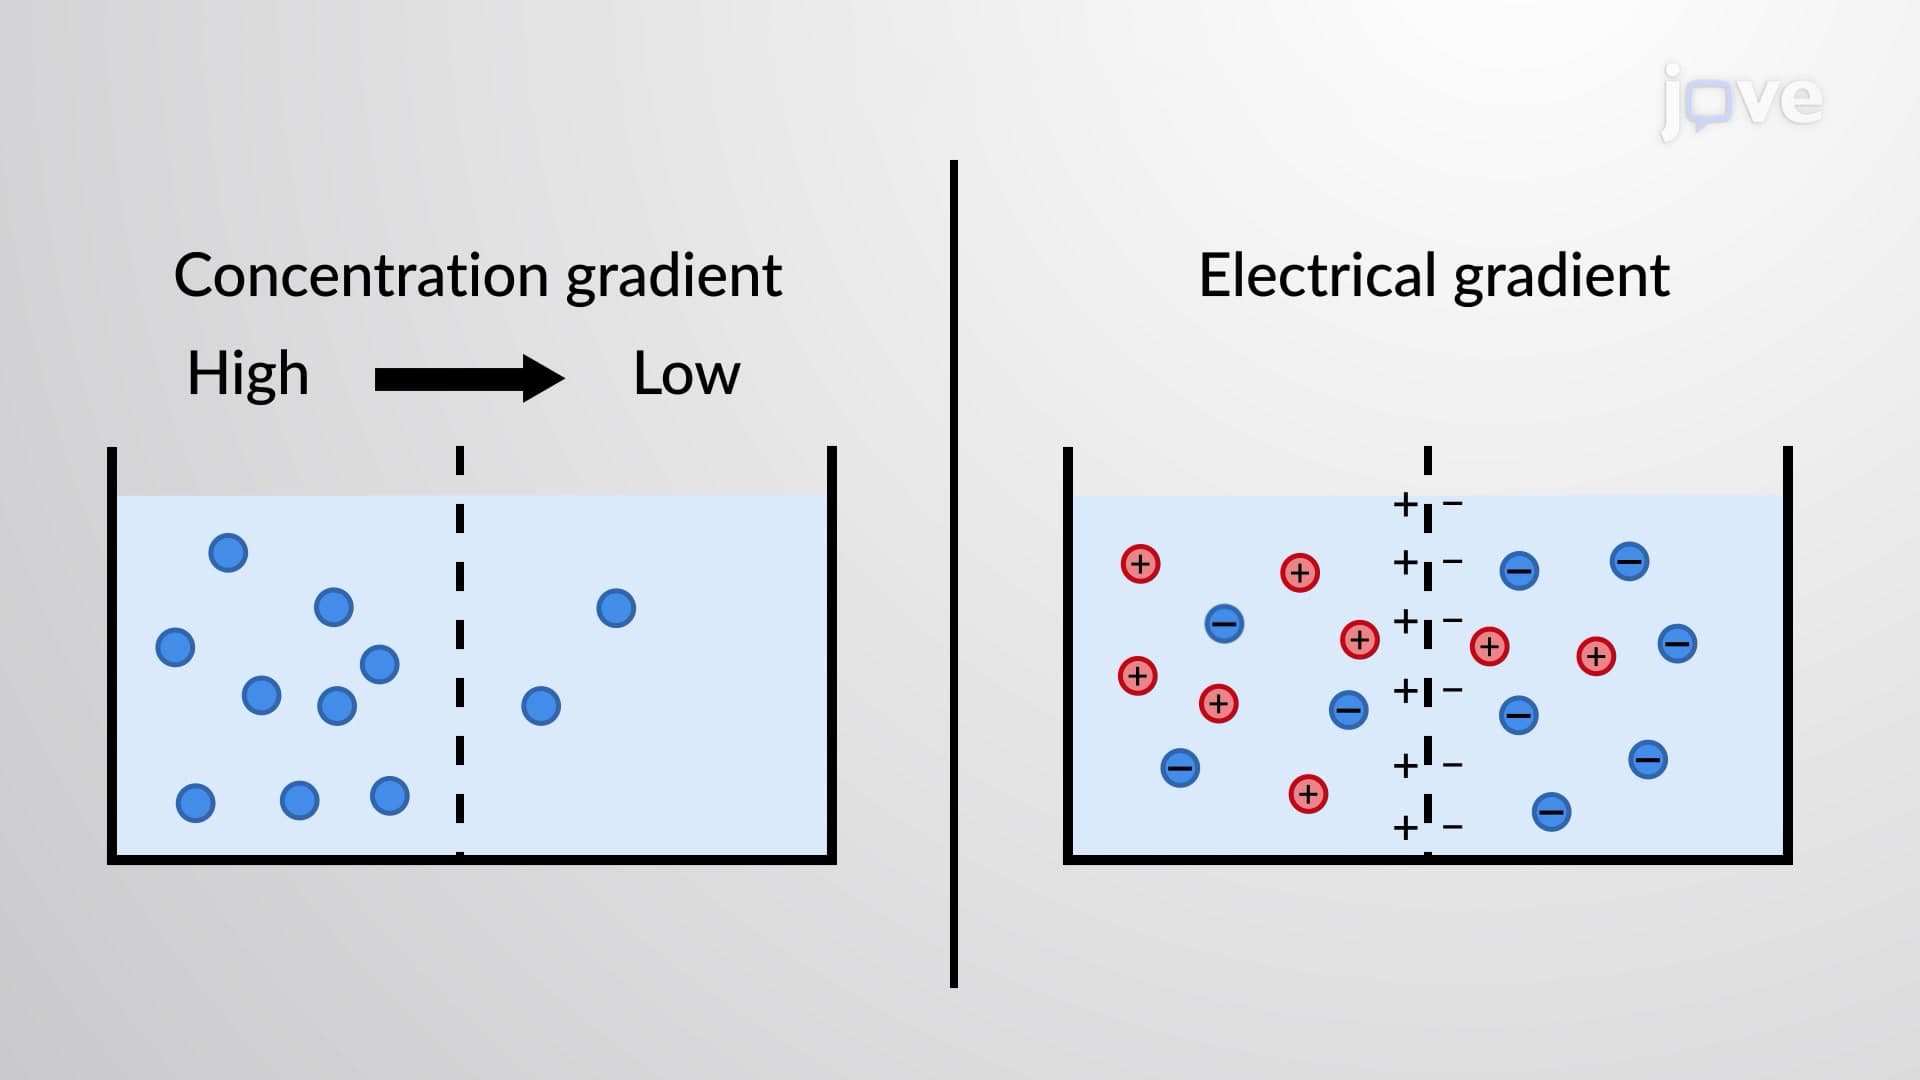
What is an Electrochemical Gradient?
The chemical gradient relies on differences in the abundance of a substance on the outside versus the inside of a cell and flows from areas of high to low ion concentration. In contrast, the electrical gradient revolves around an...