Related Experiment Video
Updated: Feb 1, 2026
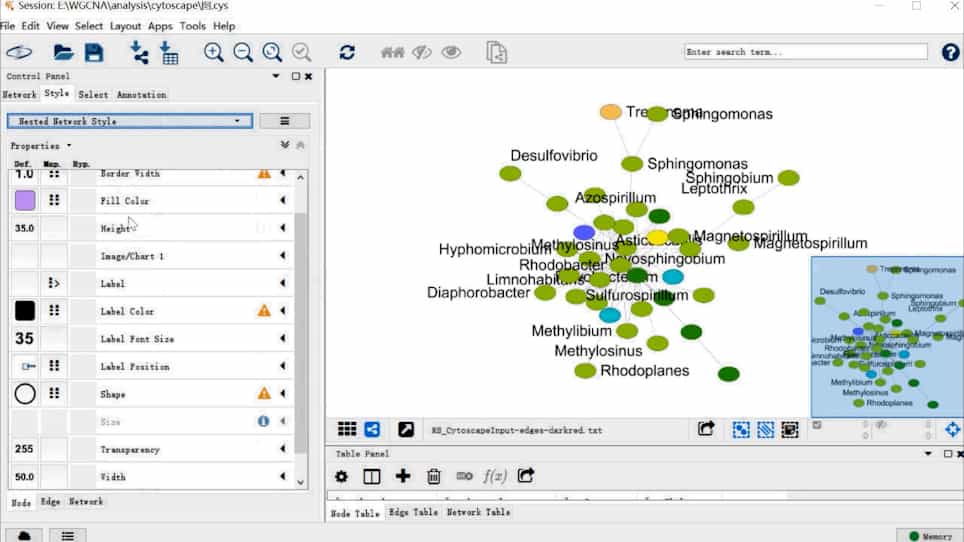

Divergence of Root Microbiota in Different Habitats based on Weighted Correlation Networks
Published on: September 25, 2021
Building a dynamic correlation network for fat-tailed financial asset returns
1Bank of Japan, 2-1-1 Nihonbashi-Hongokucho, Chuo-ku, Tokyo, 103-8660 Japan.

Abstract:
In this paper, a novel approach to building a dynamic correlation network of highly volatile financial asset returns is presented. Our method avoids the spurious correlation problem when estimating the dynamic correlation matrix of financial asset returns by using a filtering approach. A multivariate volatility model, DCC-GARCH, is employed to filter the fat-tailed returns. The method is proven to be more reliable for detecting dynamic changes in the correlation matrix compared with the widely used method of calculating time-dependent correlation matrices over a fixed size moving window, which can have fundamental problems when applied to fat-tailed returns. We apply the method to selected Japanese stock returns to observe the dynamic network changes as a case study. The estimated time-dependent correlation matrices are then compared with those calculated by using the traditional method to highlight the advantages of the proposed method. Two types of indicators, namely the largest eigenvalue and cosine distance measures, are introduced to identify significant changes in the correlation matrix for an initial screening of remarkable stress events. A more detailed network-based analysis is then conducted by examining topological measures calculated from the network adjacency matrices. The higher density and lower heterogeneity of the correlation network during stress periods are clearly observed, while the correlation network of stock returns is shown to be robust with regard to time. The method discussed in this paper is not limited to stock returns; it can also be applied to build a dynamic correlation network of other financial and non-financial time series with high volatility.
Related Concept Videos
 01:27
Correlation and Causation
Correlation versus Causation
If the dependent variable increases or decreases when the independent variable increases, there is a positive or negative...
 02:20
Correlations
 01:04
Venous Return
What is Venous Return?
Venous return refers to the rate at which blood flows back to the heart from the body's peripheral veins. It's an integral part of the circulatory system...
 02:26
Protein Networks
These interactions can be represented through maps depicting protein-protein interaction networks, represented as nodes and edges. Nodes are circles that are representative of a protein,...
 01:09
Correlation
Two variables, for example, a and b, are said to be positively correlated if both variables move in the same direction. In other words, a positive correlation exists between two variables, a and b, if:
 02:18
Network Covalent Solids
To break or to melt a covalent network solid, covalent bonds must be broken. Because covalent bonds are relatively strong, covalent network solids are typically...