Properties of Mean Shift
Related Experiment Video
Updated: Jan 25, 2026
New Variations for Strategy Set-shifting in the Rat
Published on: January 23, 2017

Abstract:
We study properties of the mean shift (MS)-type algorithms for estimating modes of probability density functions (PDFs), via regarding these algorithms as gradient ascent on estimated PDFs with adaptive step sizes. We rigorously prove convergence of mode estimate sequences generated by the MS-type algorithms, under the assumption that an analytic kernel function is used. Moreover, our analysis on the MS function finds several new properties of mode estimate sequences and corresponding density estimate sequences, including the result that in the MS-type algorithm using a Gaussian kernel the density estimate monotonically increases between two consecutive mode estimates. This implies that, in the one-dimensional case, the mode estimate sequence monotonically converges to the stationary point nearest to an initial point without jumping over any stationary point.
Related Concept Videos
 02:57
Physical and Chemical Properties of Matter
 02:58
Properties of Transition Metals
 01:15
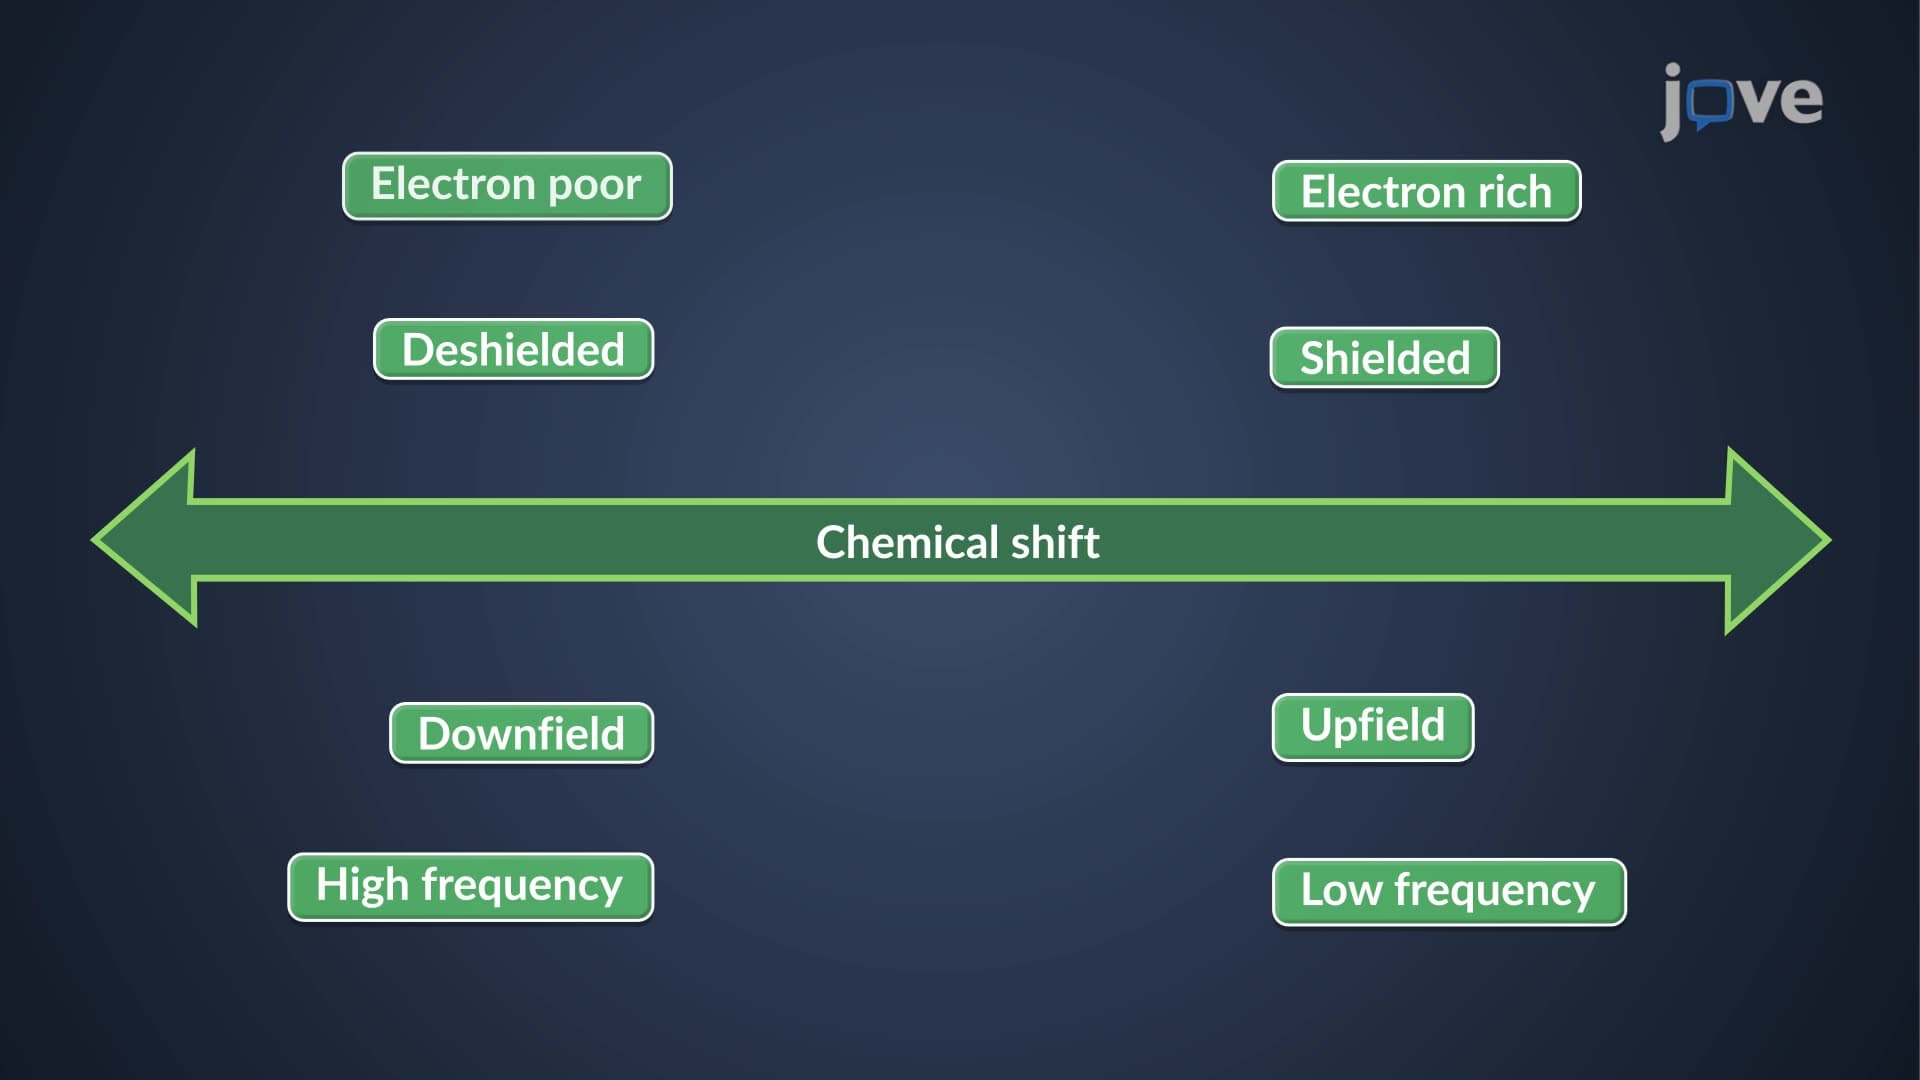
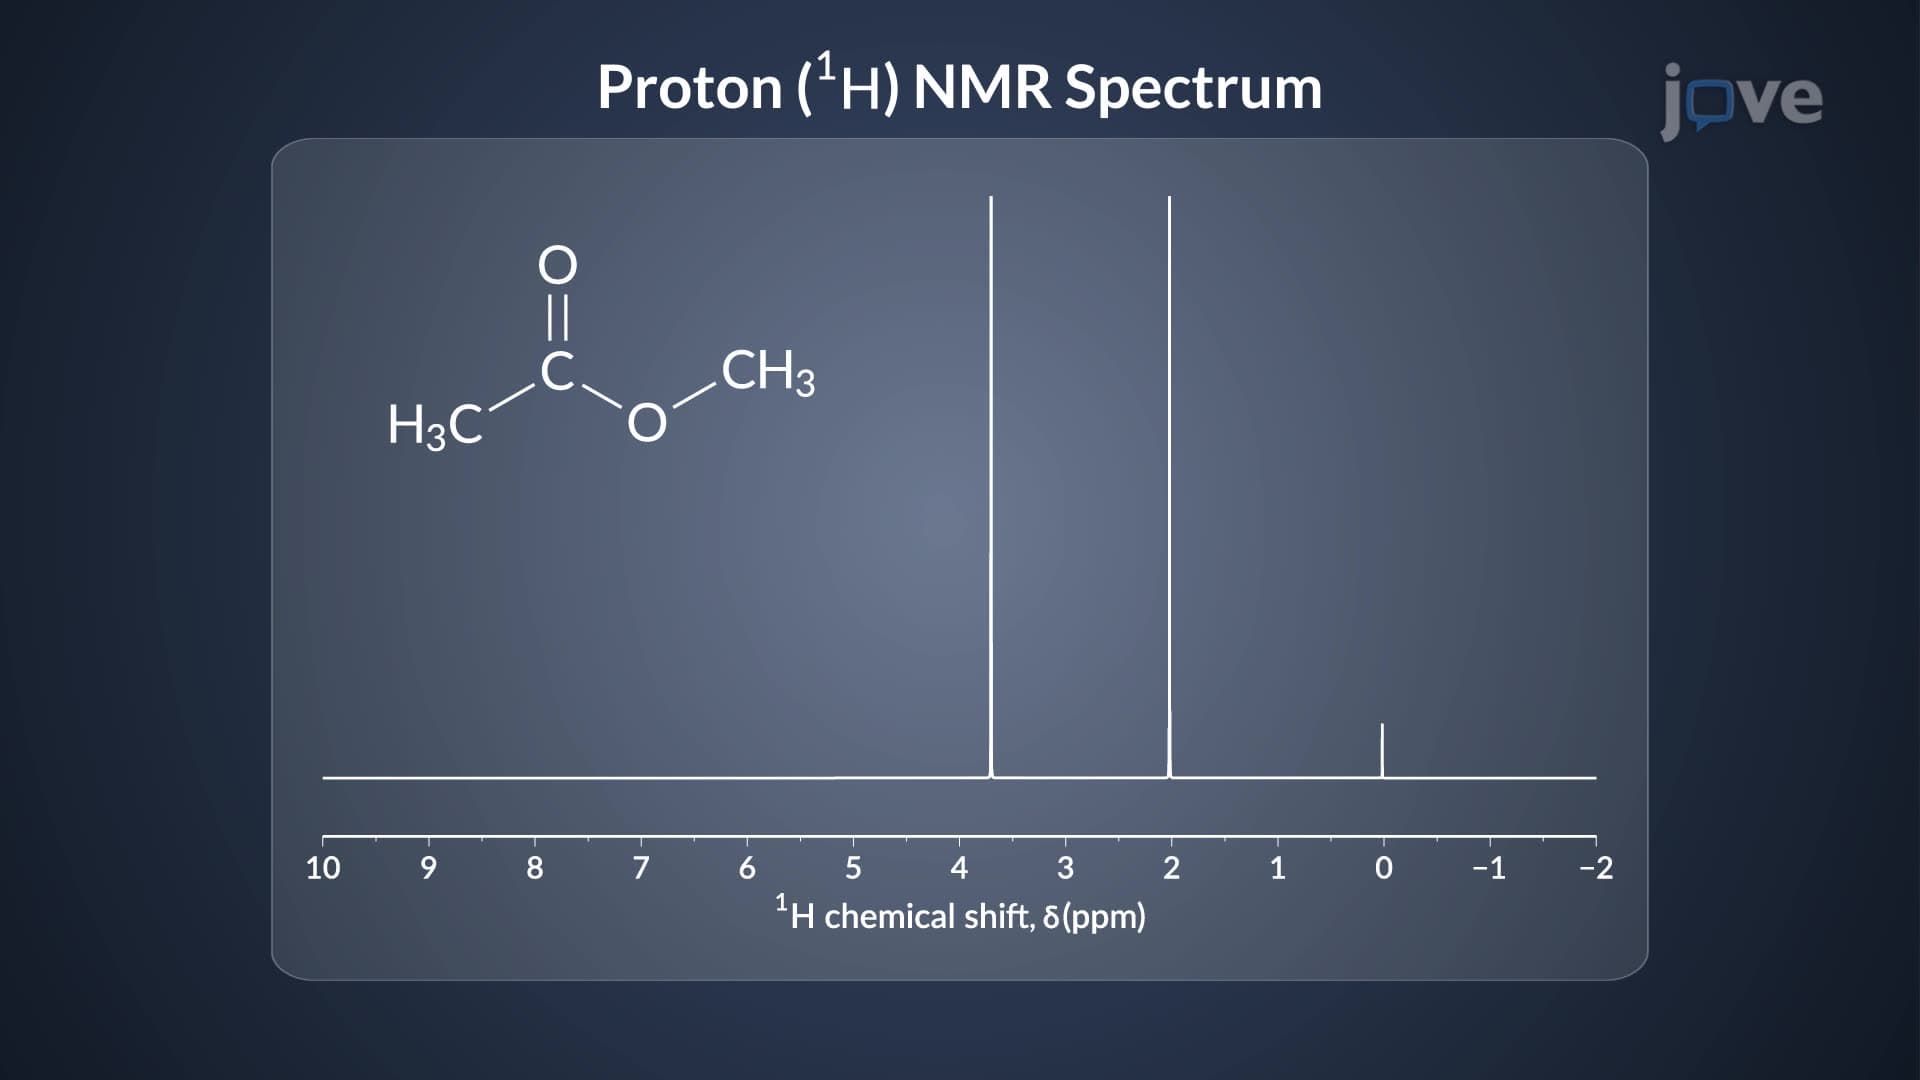
NMR Spectroscopy: Chemical Shift Overview
For instance, the proton...
 01:07
Proton (¹H) NMR: Chemical Shift
Absorption signals of all the protium nuclei...
 01:20
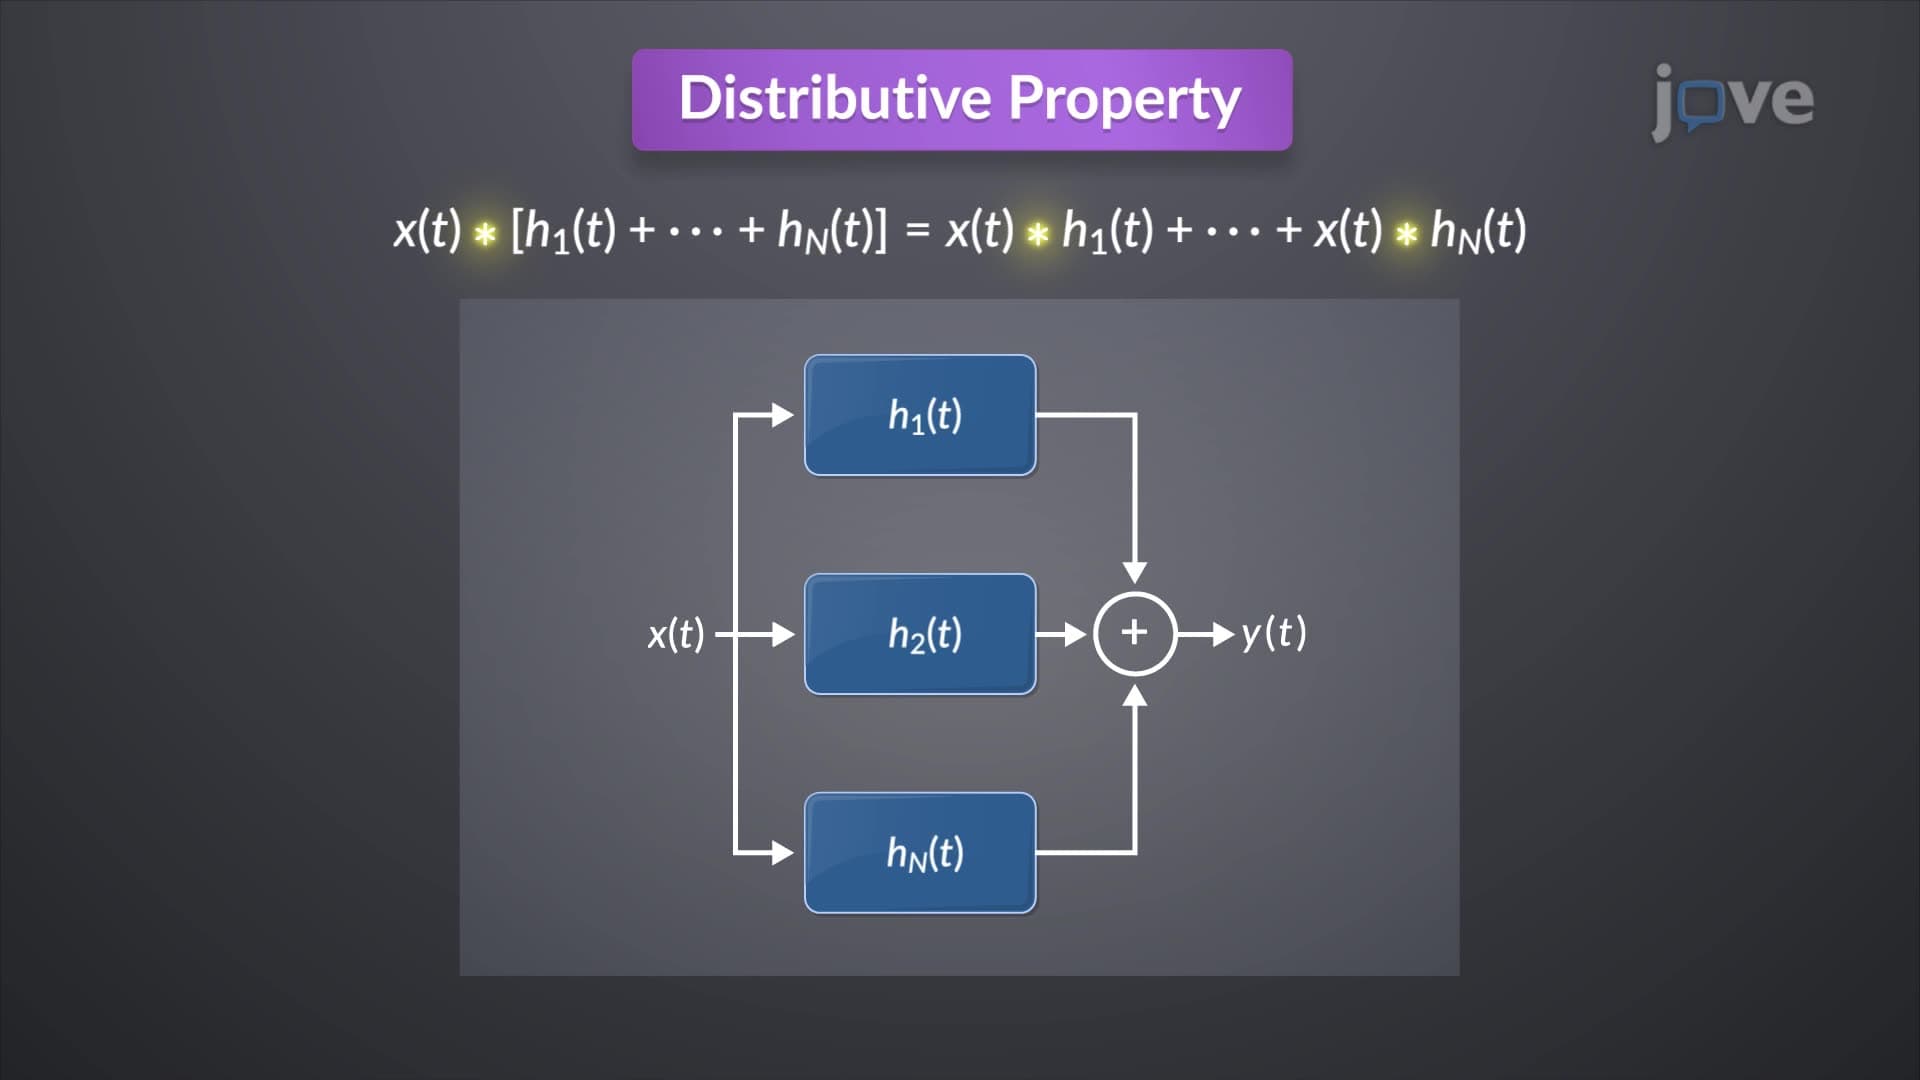
Convolution Properties I
The commutative property reveals that the input and the impulse response of an LTI (Linear Time-Invariant) system can be interchanged without affecting the output:
 01:24
Properties of DTFT II
The frequency differentiation property is illustrated by considering a DTFT pair and differentiating both sides with respect to ω.