Related Experiment Video
Updated: Jan 21, 2026

Screening of Tobacco Genotypes for Phytophthora nicotianae Resistance
Published on: April 15, 2022
The Relation Between Tobacco Tax Structure and Corruption in European Union Member States
Ajay Shah1, Katie Eminson1, Ilze Bogdanovica2
1UK Centre for Tobacco and Alcohol Studies, Division of Epidemiology and Public Health, University of Nottingham, Clinical Sciences Building, City Hospital, Nottingham NG5 1PB, UK.

Abstract:
Background: Taxing tobacco products is one of the most effective tobacco control measures, and most countries apply a combination of specific taxes, which comprise a fixed amount per cigarette or gram of hand-rolling tobacco, and ad valorem taxes, which increase in proportion to the cost of the product. Since specific taxes reduce price differentials across tobacco product ranges while ad valorem taxes amplify them, we hypothesised that tobacco companies seeking to minimise the effect of tax increases on sales across a range of products will tend to favour, and hence lobby for, ad valorem rather than specific taxes; and that relatively corrupt governments would be more susceptible to such lobbying and hence, more likely to favour ad valorem taxes. Methods: We searched for cigarette tax data and Transparency International Corruption Perceptions Index (CPI) scores for current 28 EU Member States for the years 1995 to 2017/8. Trends in cigarette tax levels and the ratio of ad valorem to specific taxes at a national and mean EU level were analysed by visual inspection, the within-country relation between the ad valorem to specific tax ratio and CPI scores over time by time-series regression analysis, and at EU level, for which complete data were available from 1995 to 2017, using a multi-level regression model. Results: Within most Member States, the ad valorem to specific cigarette tax ratio declined over the study period and was not significantly associated with corruption score. However, at an aggregate EU-level, our multi-level model indicated that reduced corruption was associated with a significant increase in the ad valorem to specific cigarette tax ratio, by 0.04 (95% confidence interval: 0.003-0.077, p < 0.036) per unit increase in CPI score. Conclusions: The ratio of ad valorem to specific taxes declined in most EU Member States over the study period, with no evidence that those with higher levels of perceived corruption tended to favour ad valorem taxes.
Related Concept Videos
 01:12
Relative Risk
 01:10
Relative Velocity in One Dimension
 02:22
Structures of Solids
 01:20
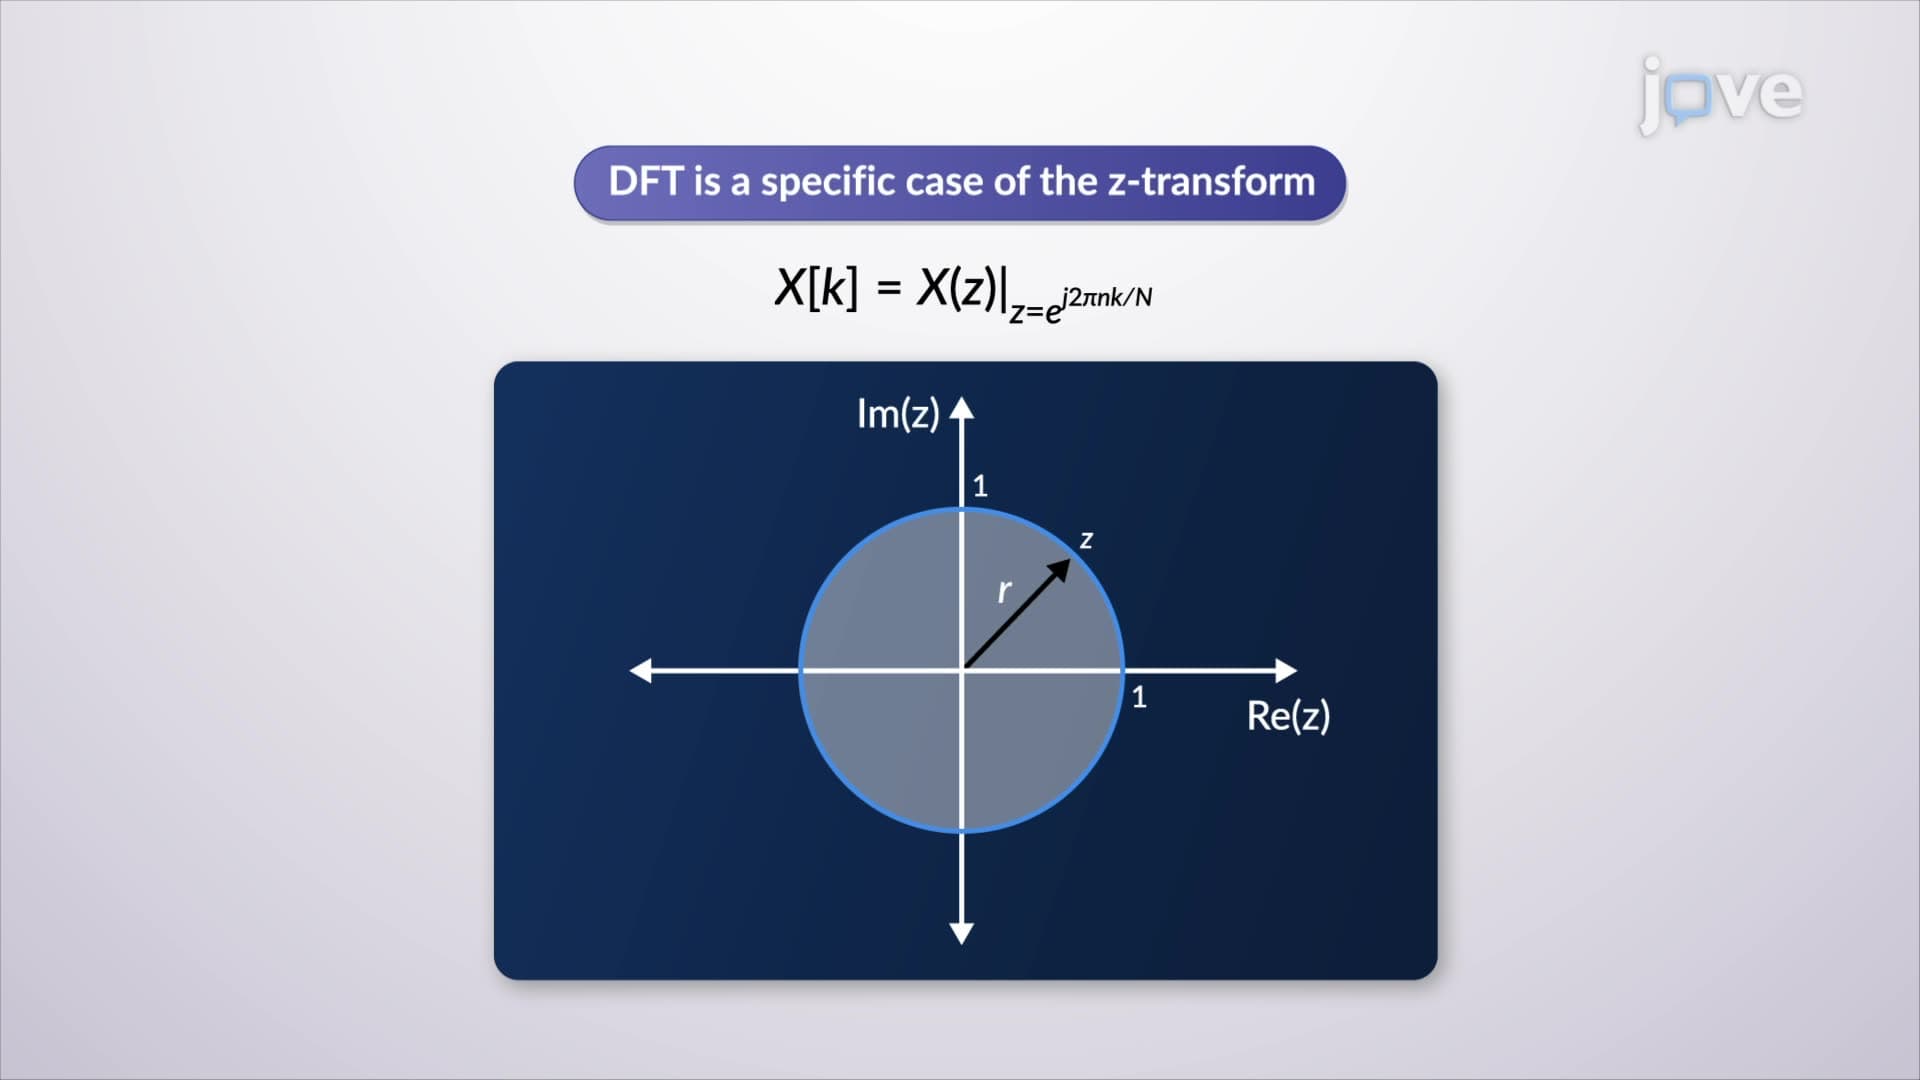
Relation of DFT to z-Transform
To understand how the DFT works, it's helpful to consider the z-transform, which is a method for representing discrete sequences in the complex frequency domain. The z-transform involves summing the...
 01:23
Maxwell's Thermodynamic Relations
All thermodynamic potentials are exact differentials. Therefore, their second-order...
 01:14
Relative Frequency Histogram