Related Experiment Video
Updated: Dec 29, 2025

Laboratory Production of Biofuels and Biochemicals from a Rapeseed Oil through Catalytic Cracking Conversion
Published on: September 2, 2016
Liquidity and volatility commonality in the Canadian stock market
Nathan Gold1, Qiming Wang2,3, Melanie Cao4
11Department of Mathematics and Statistics, York University, 4700 Keele St., Toronto, M3J 1P3 Canada.

Abstract:
This paper studies liquidity and volatility commonality in the Canadian stock market. We show that five various liquidity measures display strong evidence of commonality at both market-wide and industry specific levels. Our findings extend the results of previous studies in liquidity commonality, and show that even after controlling for individual determinants of liquidity such as price, volume, and volatility, liquidity commonality remains. In addition to demonstrating liquidity commonality, we also investigated the causal relationship between liquidity and volatility. Our evidence indicates that depth, proportional effective spread, and liquidity changes predict volatility changes for bid-ask spread, depth, and proportional effective spread.
Related Concept Videos
 01:10
Standard Deviation
 01:15
Variance
The standard deviation measures the spread in the same units as the data....
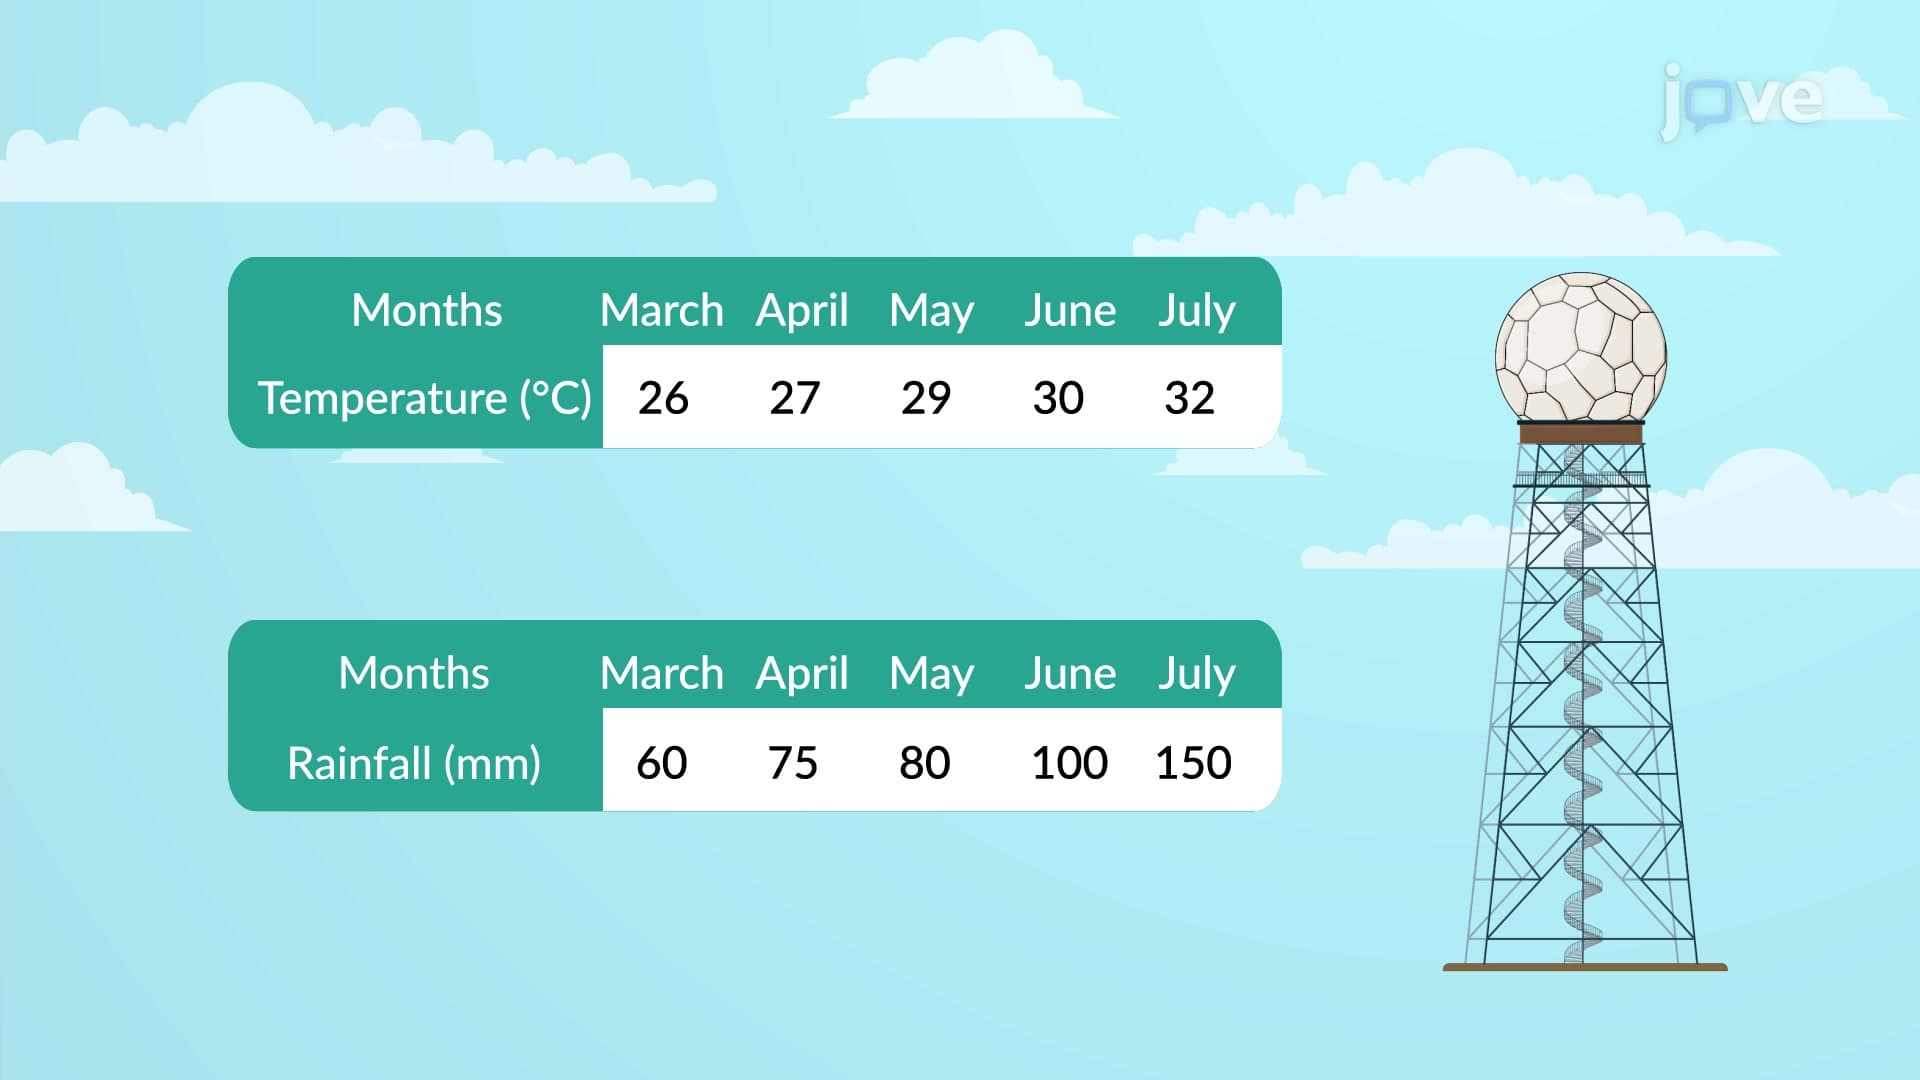 01:10
Coefficient of Variation
The coefficient of variation is a practical statistical tool in finance. It allows investors to assess the volatility or...
 01:26
Equity Theory
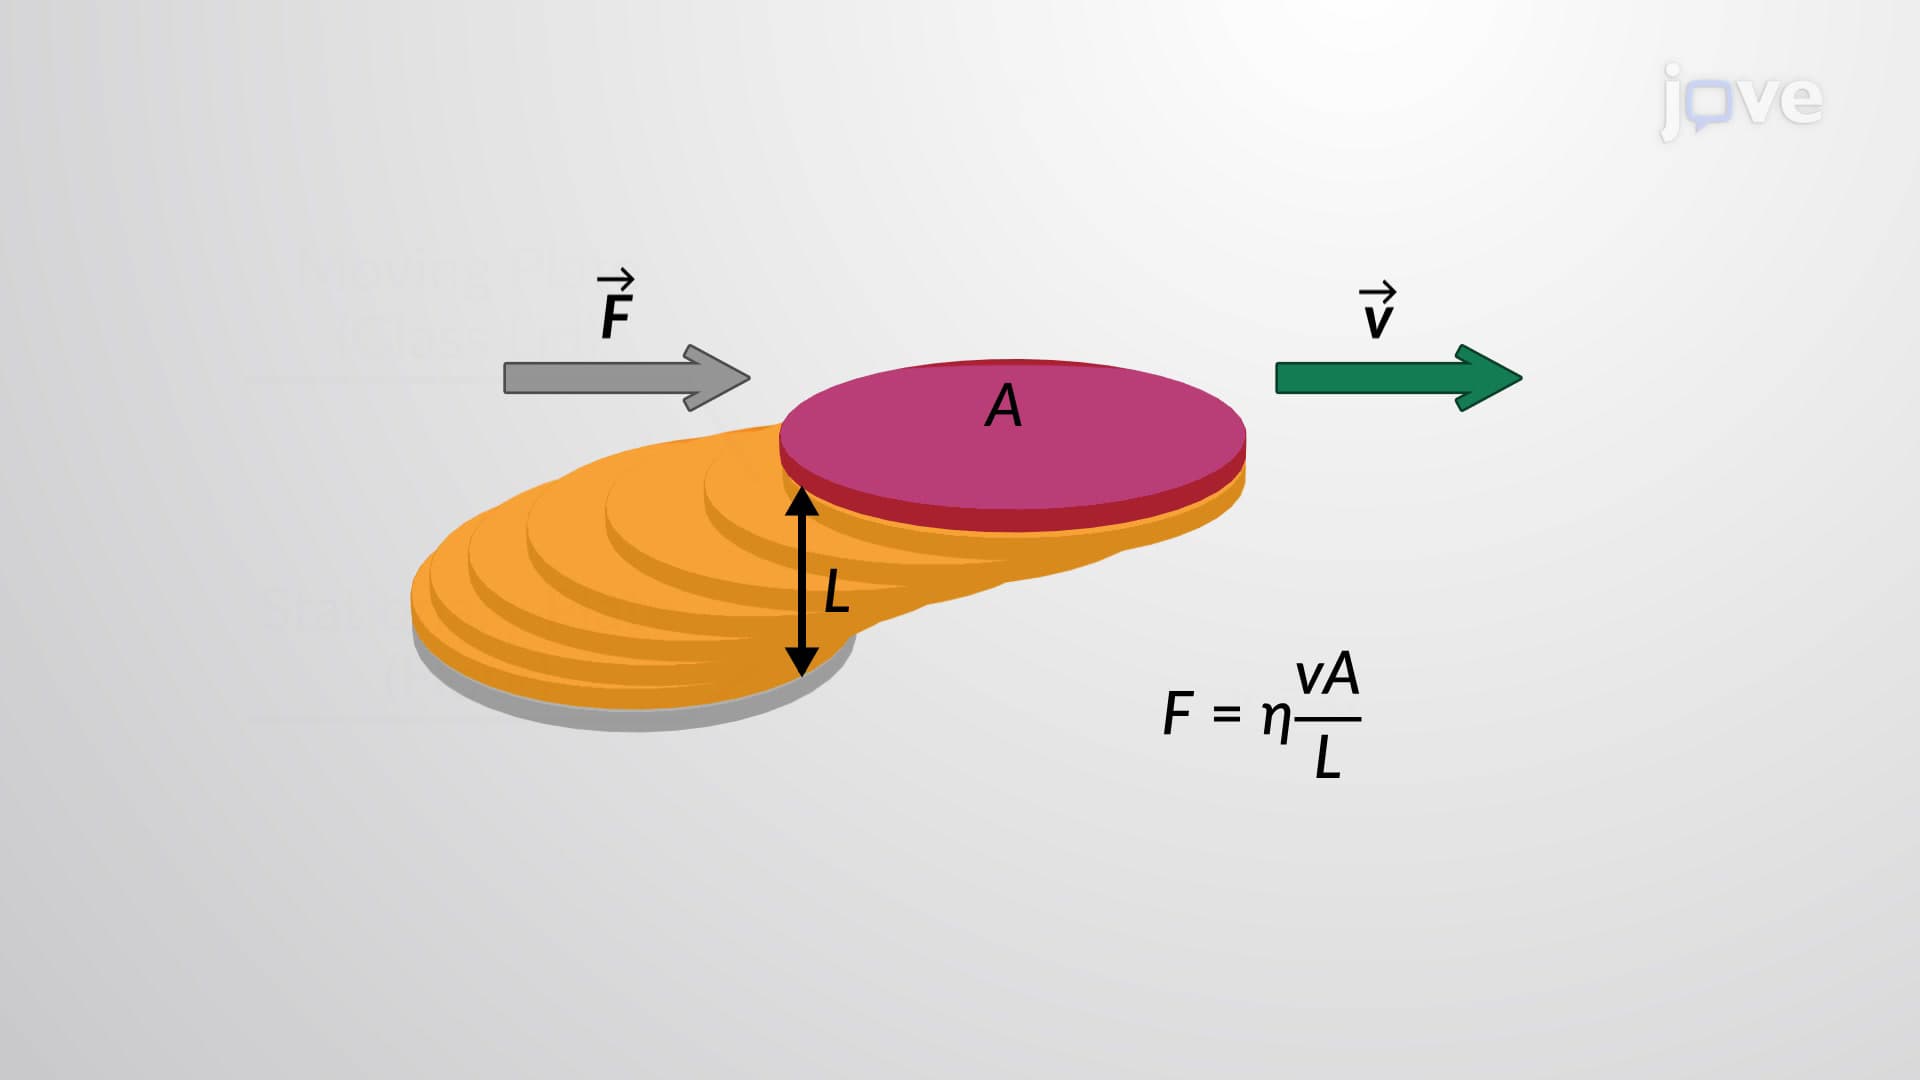 01:17
Viscosity
The SI unit of viscosity is...
 01:11
Variability: Analysis
The range is a simple measure of variability, indicating the difference between the highest and...