Statistical analysis of differential equations: introducing probability measures on numerical solutions
Related Experiment Video
Updated: Dec 25, 2025
Synthesis of Cyclic Polymers and Characterization of Their Diffusive Motion in the Melt State at the Single Molecule Level
Published on: September 26, 2016
Patrick R Conrad1, Mark Girolami1,2, Simo Särkkä3
11Department of Statistics, University of Warwick, Coventry, UK.

Abstract:
In this paper, we present a formal quantification of uncertainty induced by numerical solutions of ordinary and partial differential equation models. Numerical solutions of differential equations contain inherent uncertainties due to the finite-dimensional approximation of an unknown and implicitly defined function. When statistically analysing models based on differential equations describing physical, or other naturally occurring, phenomena, it can be important to explicitly account for the uncertainty introduced by the numerical method. Doing so enables objective determination of this source of uncertainty, relative to other uncertainties, such as those caused by data contaminated with noise or model error induced by missing physical or inadequate descriptors. As ever larger scale mathematical models are being used in the sciences, often sacrificing complete resolution of the differential equation on the grids used, formally accounting for the uncertainty in the numerical method is becoming increasingly more important. This paper provides the formal means to incorporate this uncertainty in a statistical model and its subsequent analysis. We show that a wide variety of existing solvers can be randomised, inducing a probability measure over the solutions of such differential equations. These measures exhibit contraction to a Dirac measure around the true unknown solution, where the rates of convergence are consistent with the underlying deterministic numerical method. Furthermore, we employ the method of modified equations to demonstrate enhanced rates of convergence to stochastic perturbations of the original deterministic problem. Ordinary differential equations and elliptic partial differential equations are used to illustrate the approach to quantify uncertainty in both the statistical analysis of the forward and inverse problems.
Related Concept Videos
 01:21
Linear Approximation in Time Domain
For a simple pendulum with a mass evenly distributed along its length and the center of mass located at half the pendulum's length,...
 01:09
Poisson Probability Distribution
The...
 01:25
Poisson's And Laplace's Equation
 01:31
Classification of Systems-II
 01:23
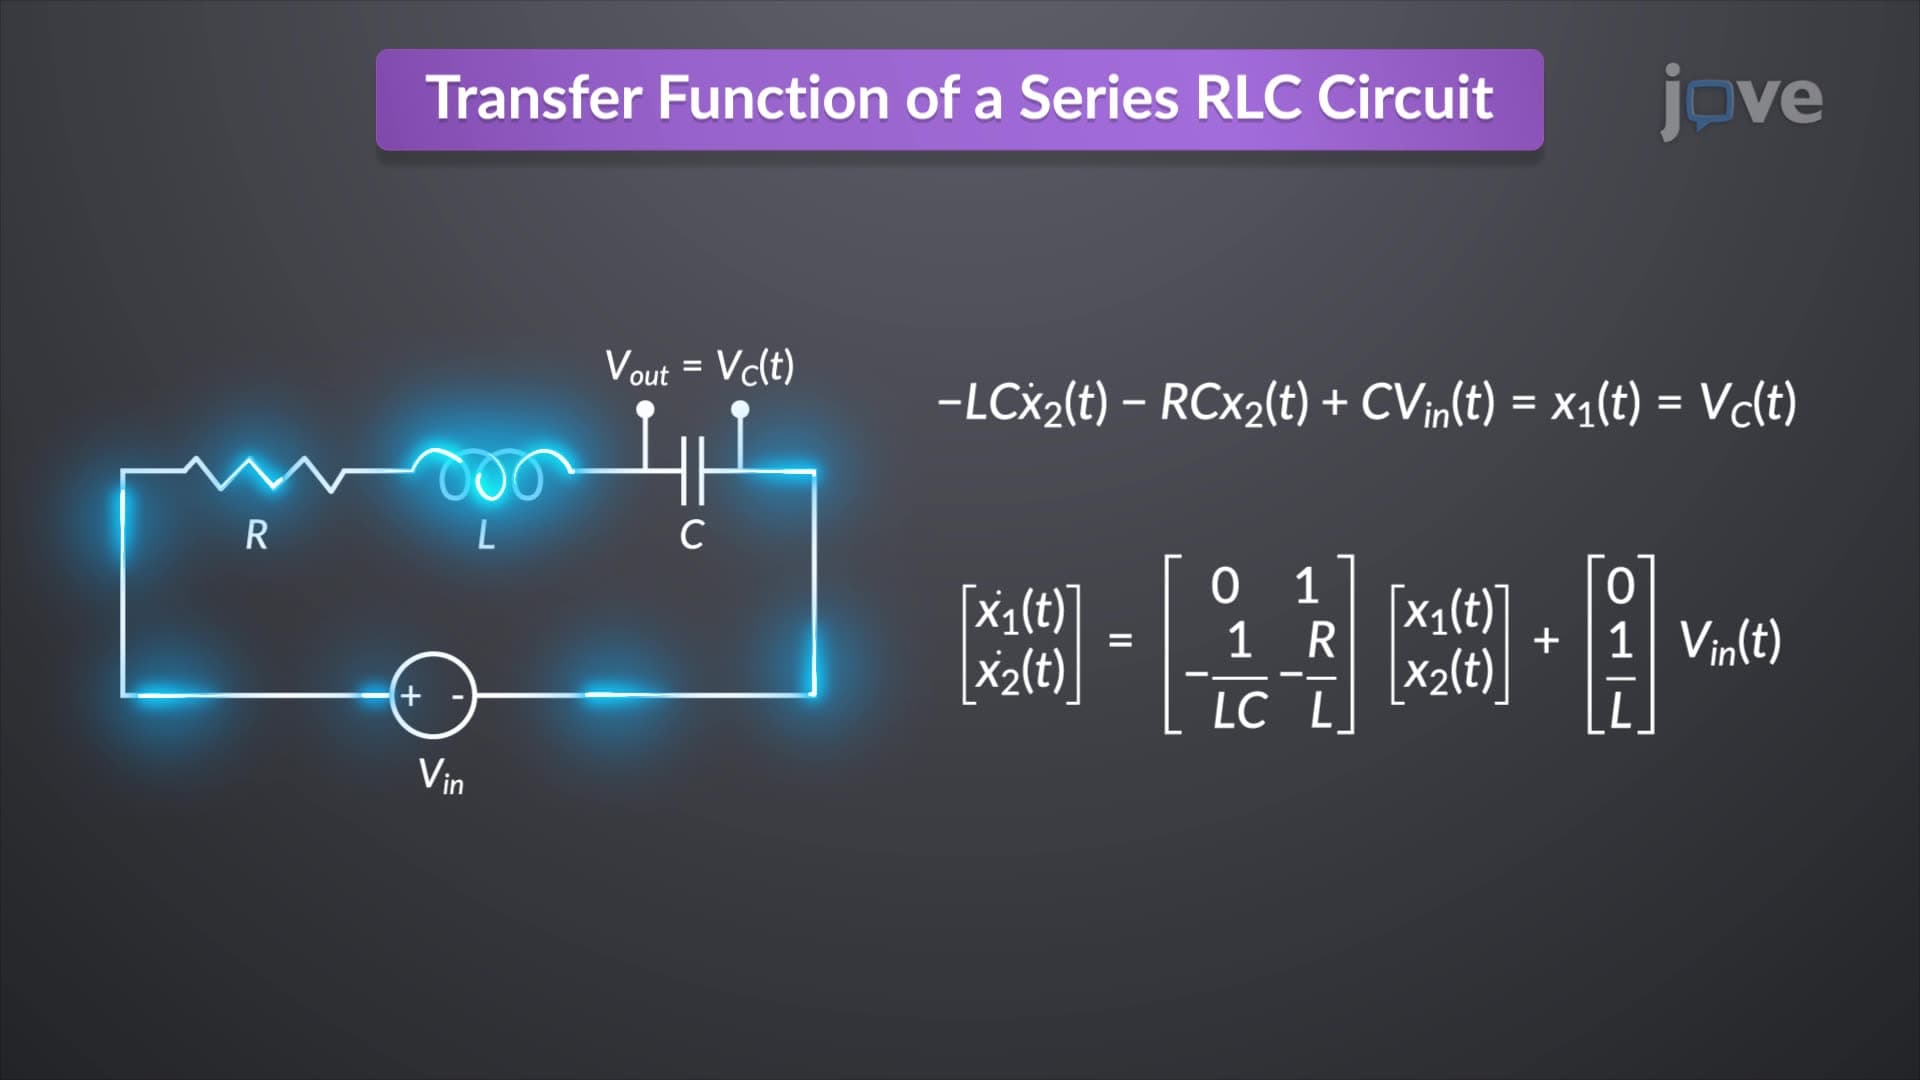
Transfer Function to State Space
In an RLC...
 01:29
Mechanistic Models: Compartment Models in Algorithms for Numerical Problem Solving
In individual population analyses, different algorithms are employed, such as Cauchy's method, which uses a...