Related Experiment Video
Updated: Dec 11, 2025
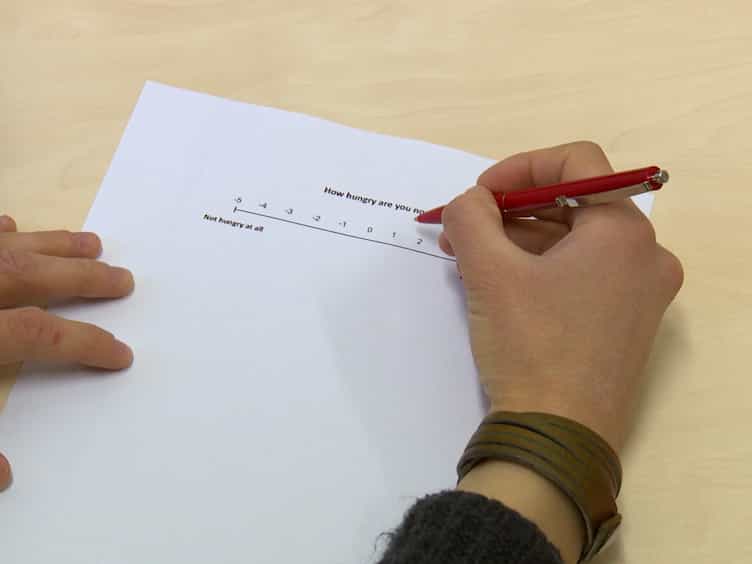

Errors as a Means of Reducing Impulsive Food Choice
Published on: June 5, 2016
Loss aversion and market crashes
1Department of Finance, NEOMA Business School, 59 Rue Pierre Taittinger, 51100, Reims, France.

Abstract:
This study proposes a rational expectation equilibrium model of stock market crashes with information asymmetry and loss averse speculators. We obtain a state-dependent linear optimal trading strategy, which makes the equilibrium price tractable. The model predicts nonlinear market depth and the result that small shocks to fundamentals (e.g., supply or informational shocks) can cause abrupt price movements. We demonstrate that short-sale constraints intensify asset price collapses relative to upward movements. The model also generates contagion between uncorrelated assets. These results are consistent with the main puzzling features observed during market crashes, namely abrupt and asymmetric price movements that are not driven by major news events but coupled with a spillover effect between unrelated markets.
Related Concept Videos
 01:14
Avoidance Learning and Learned Helplessness
Avoidance learning occurs when an organism learns that a specific behavior can prevent an unpleasant outcome. For example, a student who receives a bad grade may start studying harder to avoid future poor grades. This behavior persists even when the negative outcome is no longer present. Avoidance learning is powerful because it maintains behavior in the absence of the...
 01:14
Fundamental Attribution Error
 01:05
Instinctive Drift
 01:12
Hindsight Biases
 01:25
The Anchoring-and-Adjustment Heuristic
 01:20
Lazarus's Cognitive Appraisal Theory
Primary Appraisal:...