Related Experiment Video
Updated: Dec 11, 2025
An R-Based Landscape Validation of a Competing Risk Model
Published on: September 16, 2022
Hedging crash risk in optimal portfolio selection
Shushang Zhu1, Wei Zhu1, Xi Pei2
1Department of Finance and Investment, Sun Yat-Sen Business School, Sun Yat-Sen University, Guangzhou 510275, China.

Abstract:
When almost all underlying assets suddenly lose a certain part of their nominal value in a market crash, the diversification effect of portfolios in a normal market condition no longer works. We integrate the crash risk into portfolio management and investigate performance measures, hedging and optimization of portfolio selection involving derivatives. A suitable convex conic programming framework based on parametric approximation method is proposed to make the problem a tractable one. Simulation analysis and empirical study are performed to test the proposed approach.
Related Concept Videos
 01:12
Hazard Ratio
For example, in a clinical trial...
 01:19
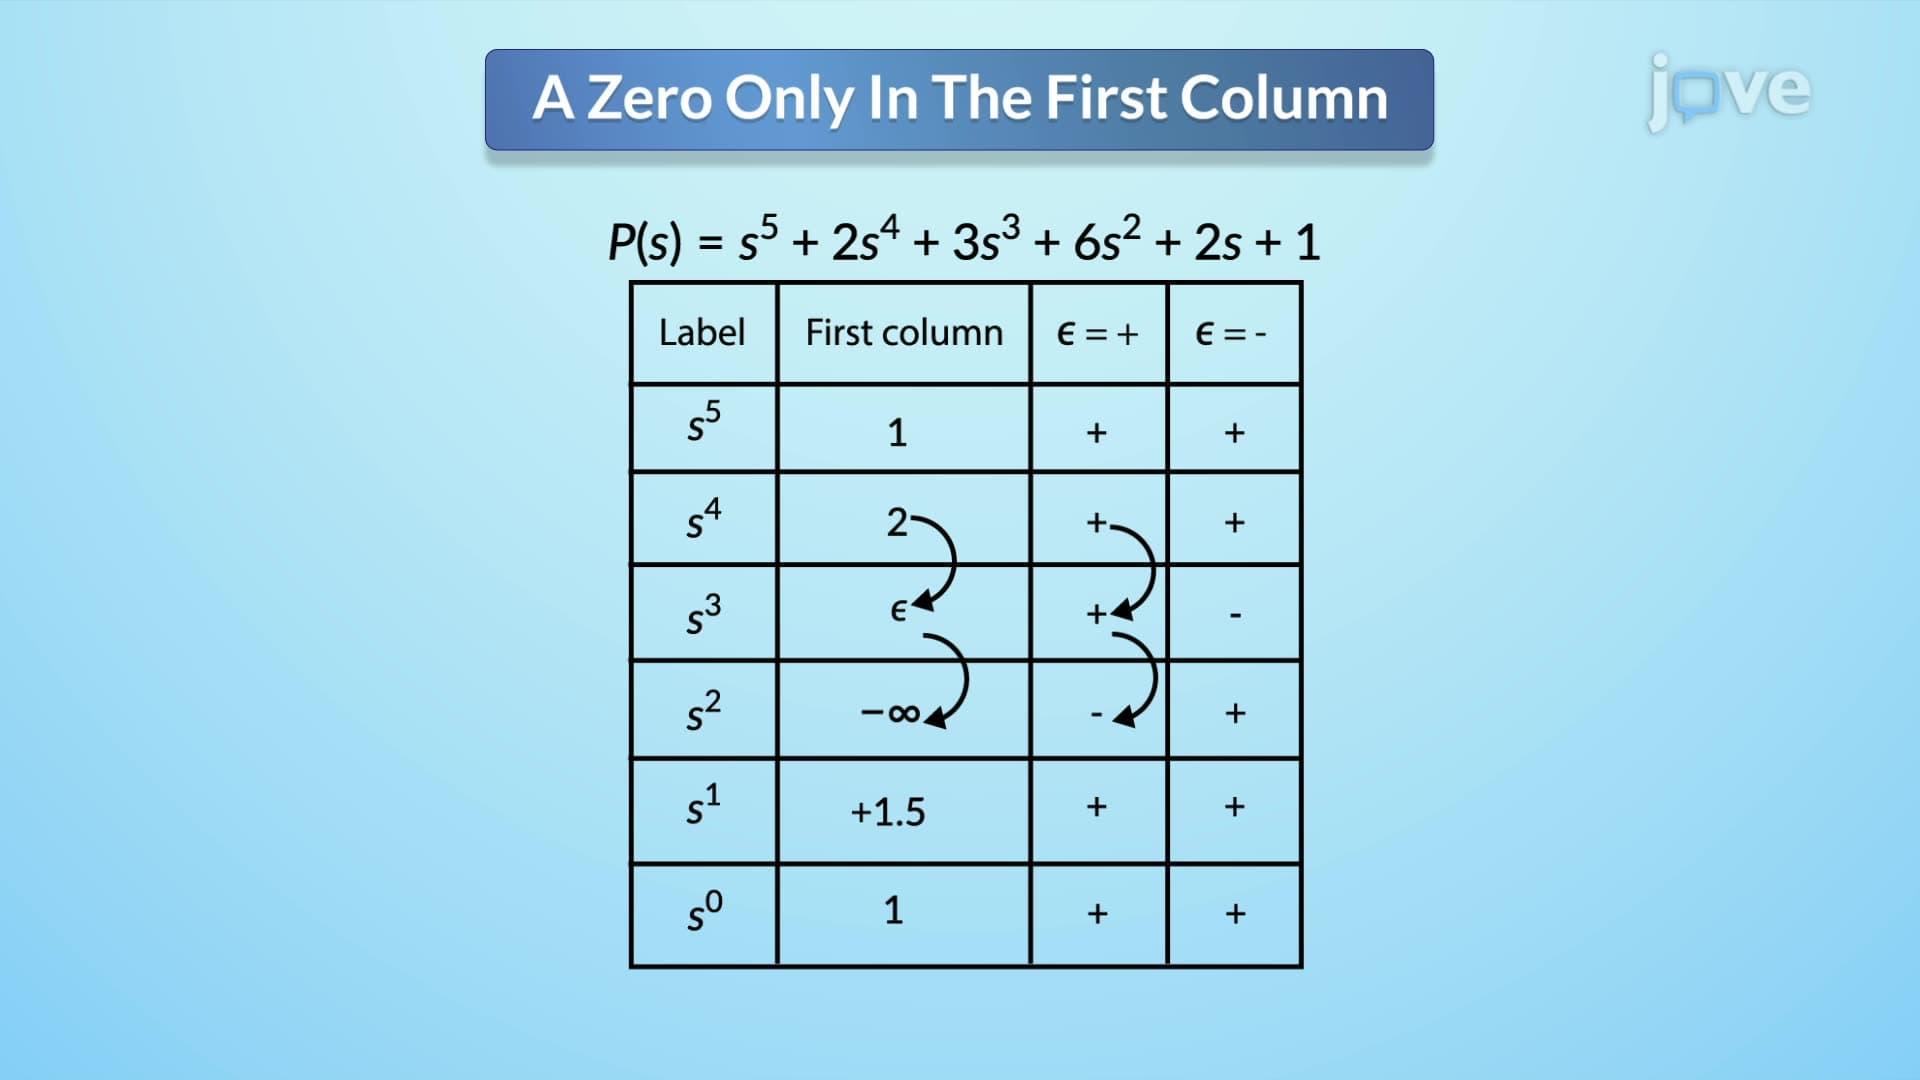
Routh-Hurwitz Criterion II
The first scenario occurs when a singular zero appears in the first column of the Routh table. This situation creates a division by zero issues. To resolve this, a small positive or negative number, denoted as epsilon (∈), is substituted for the zero. The stability analysis proceeds by assuming a sign for ∈. If ∈ is positive, any sign change in the first...
 01:09
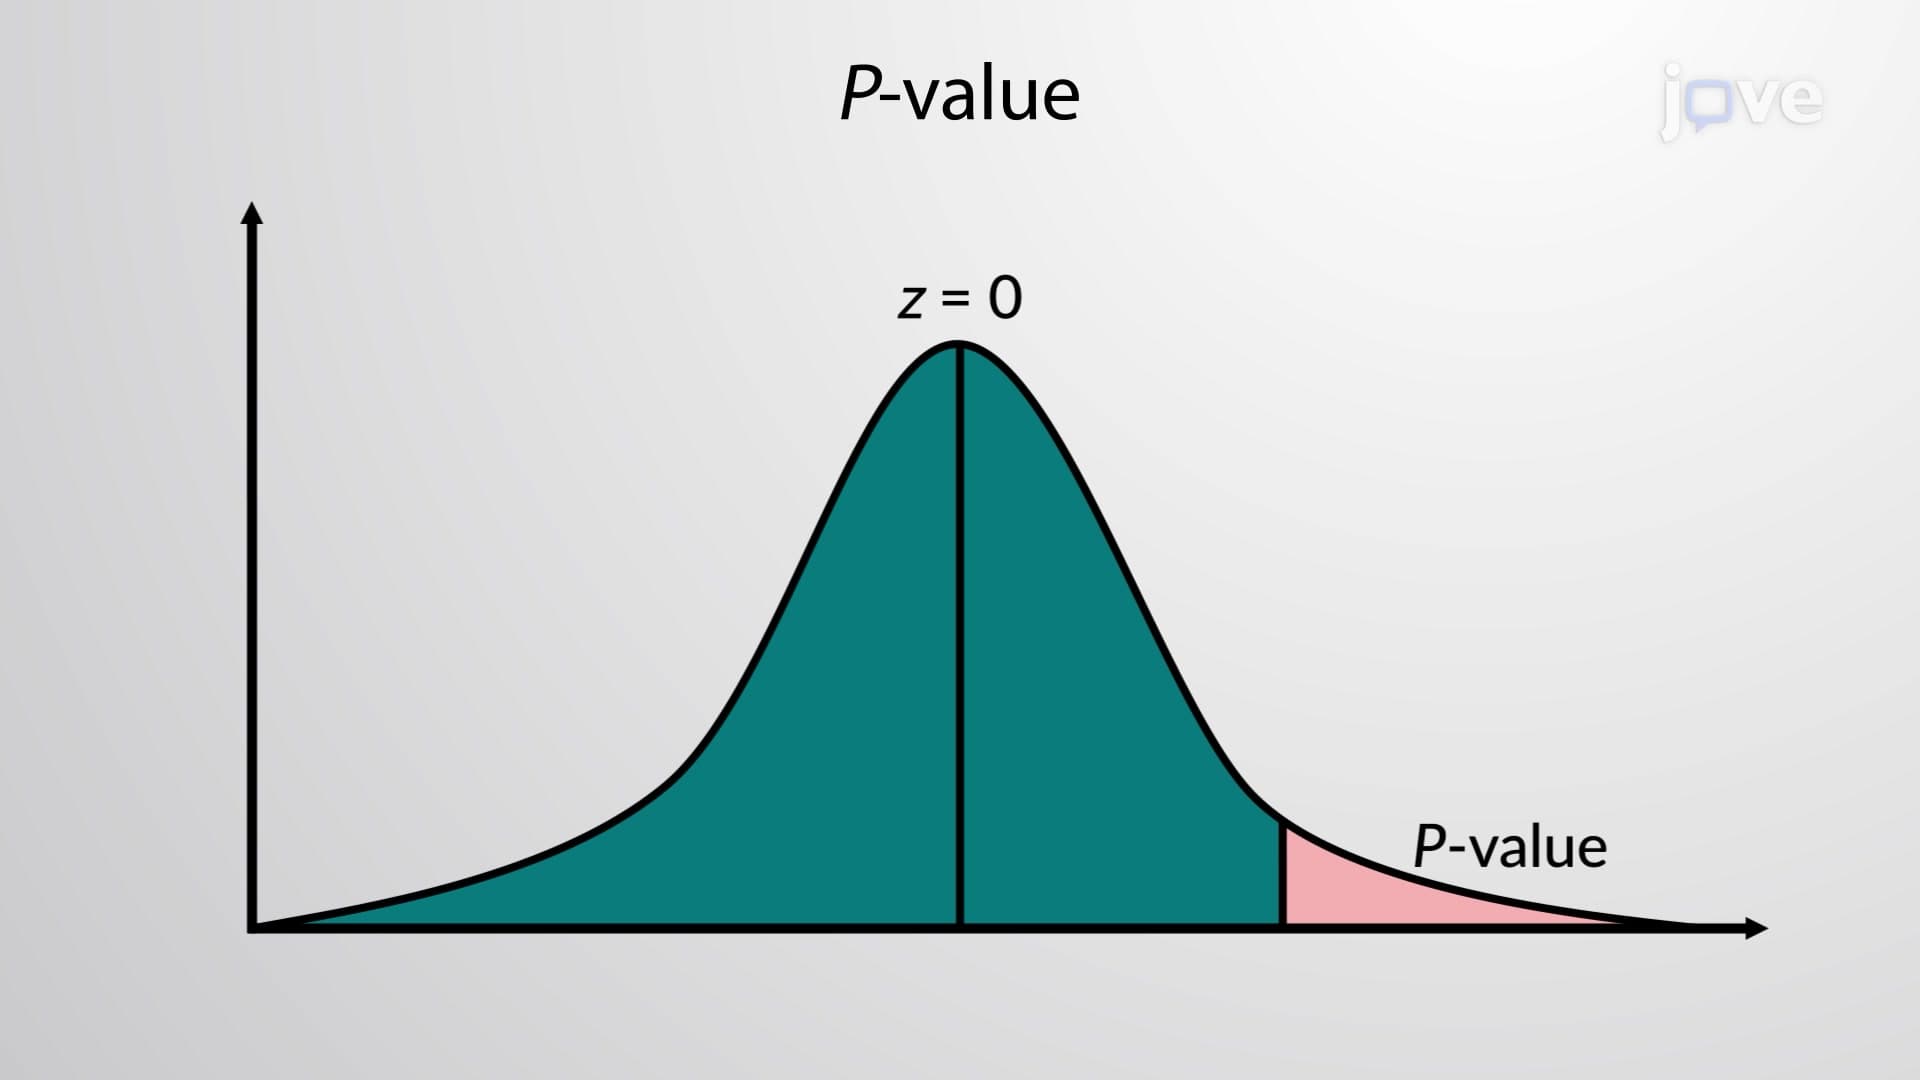
Decision Making: P-value Method
First, a specific claim about the population parameter is proposed. The claim is based on the research question and is stated in a simple form. Further, an opposing statement to the claim is also stated. These statements can act as null and alternative hypotheses: a null hypothesis would be a neutral statement while the alternative hypothesis can...
 01:11
Hazard Rate
 01:23
Types of Biopharmaceutical Studies: Controlled and Non-Controlled Approaches
Non-controlled studies, commonly employed for initial exploration, lack a control group, rendering them susceptible to biases and external influences. In contrast,...
 00:48
Optimal Foraging