Related Experiment Video
Updated: Dec 9, 2025
O-cresol Concentration Online Measurement Based On Near Infrared Spectroscopy Via Partial Least Square Regression
Published on: November 8, 2019
Examining the predictive information of CBOE OVX on China's oil futures volatility: Evidence from MS-MIDAS models
Xinjie Lu1, Feng Ma1, Jiqian Wang1
1School of Economics and Management, Southwest Jiaotong University, Chengdu, China.

Abstract:
This study evaluates whether CBOE crude oil volatility index (OVX) owns forecasting ability for China's oil futures volatility using Markov-regime mixed data sampling (MS-MIDAS) models. In-sample empirical result shows that, OVX can significantly lead to high future short-term, middle-term and long-term volatilities with regard to Chinese oil futures market. Moreover, our proposed model, the Markov-regime MIDAS with including the OVX (MS-MIDAS-RV-OVX), significantly outperforms the MIDAS and other competing models. Unsurprising results further confirm that OVX indeed contain predictive information for oil realized volatility (especially significant and robust in middle-term and long-term horizons) and regime switching is useful to deal with the structural break within the energy market. We carry out economic value analysis and discuss OVX's asymmetric effects concerning different trading hours and good (bad) OVX, and find OVX performs better in day-time trading hours and the good OVX is more predictive for the oil futures RV than the bad OVX. The further discussion also confirms our previous conclusions are robust during the highly volatile period of the COVID-19 pandemic.
More Related Videos
 10:58
Parametric Optimization Design Method for Friction Plates of Hydro-Viscous Clutches
Published on: July 22, 2025
 10:25
Construction of Models for Nondestructive Prediction of Ingredient Contents in Blueberries by Near-infrared Spectroscopy Based on HPLC Measurements
Published on: June 28, 2016
Related Concept Videos
 01:03
Prediction Intervals
However, the point estimate is most likely not the exact value of the population parameter, but close to it. After calculating point estimates, we construct interval estimates, called confidence intervals or prediction intervals. This prediction interval comprises a range of values unlike the point estimate and is a better predictor of the observed sample value, y.
 01:07
Midrange
Simply put, the midrange is half of the data set’s range. Similar to the mean, the midrange is sensitive to the extreme values and hence the prospective outliers. However, unlike the mean, the midrange is not sensitive to all the values of the data set that lie in the middle. Thus, it is prone to...
 01:07
Residual Plots
When the residual values are plotted against the variable x, it is called a residual...
 01:18
Microsoft Excel: Regression Analysis
To perform regression...
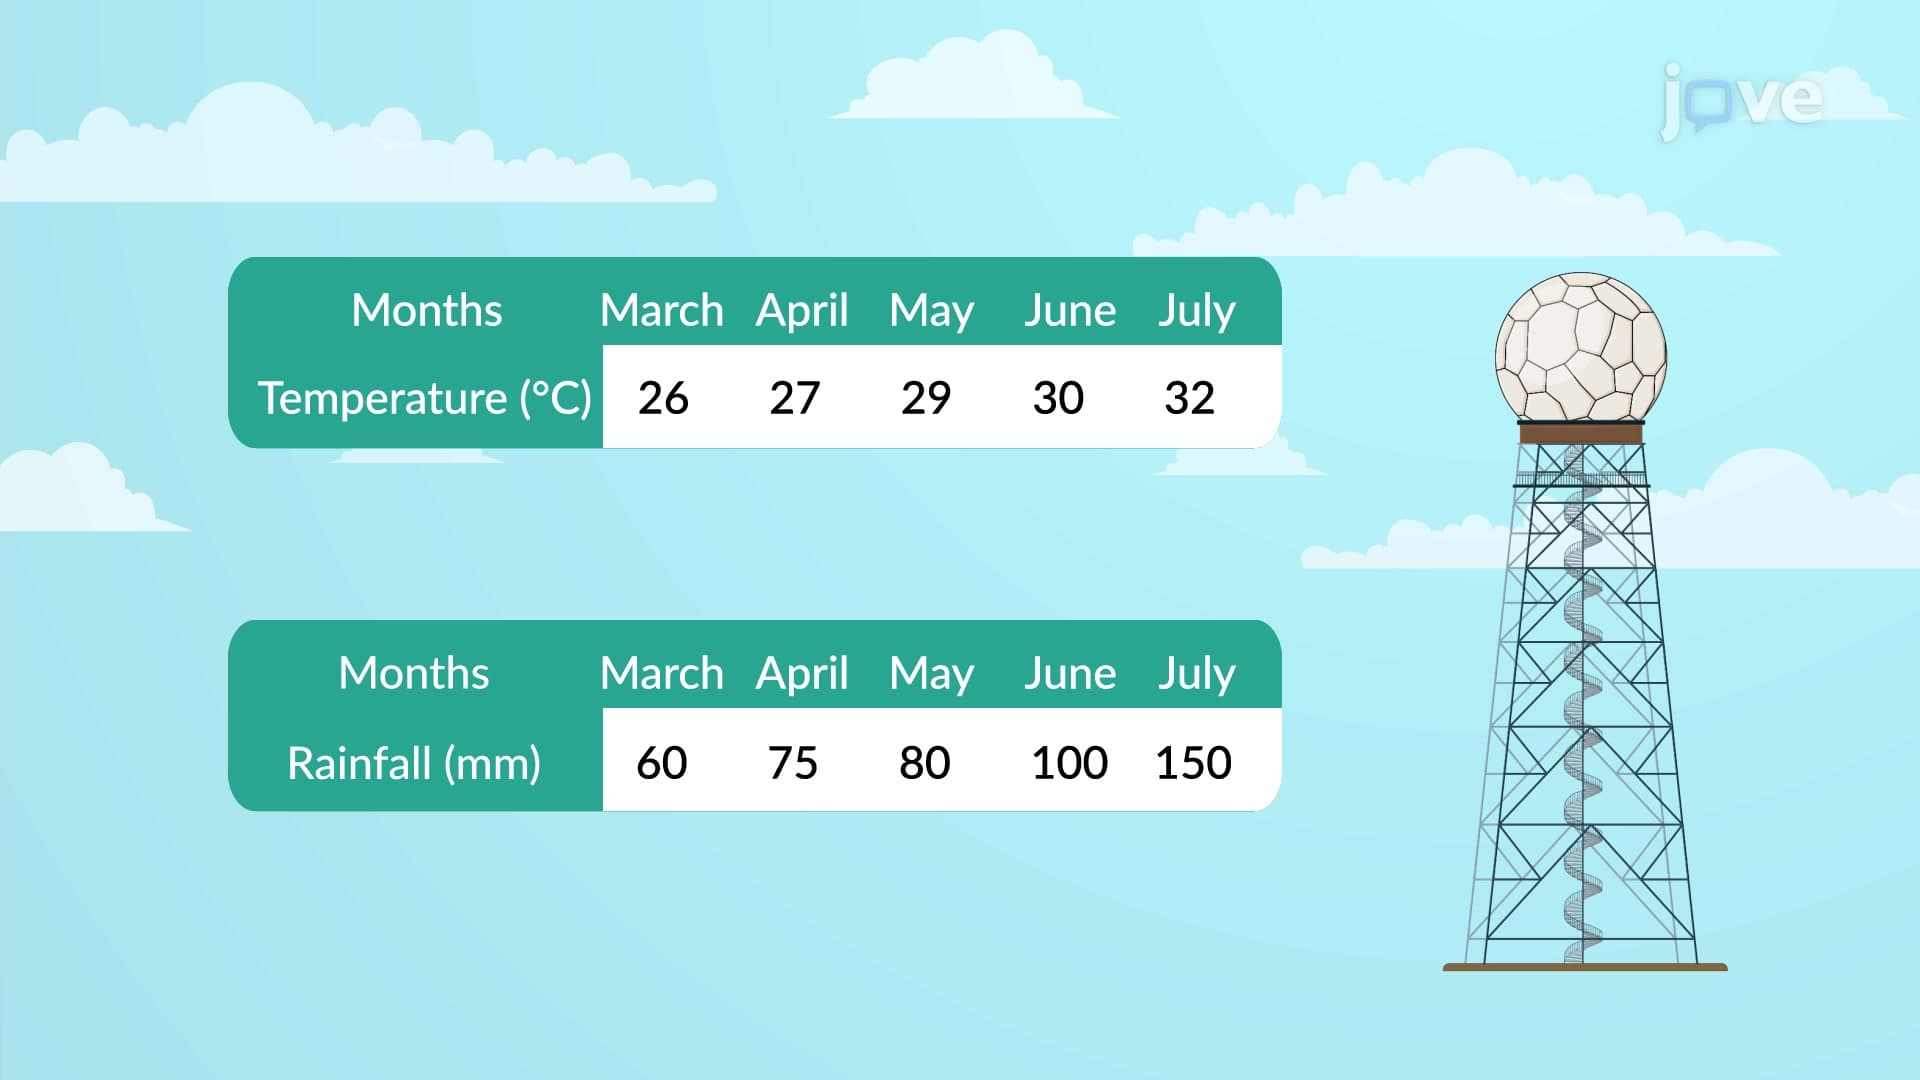 01:10
Coefficient of Variation
The coefficient of variation is a practical statistical tool in finance. It allows investors to assess the volatility or...
 01:27
Margin of Error