Related Experiment Video
Updated: Dec 8, 2025

Controlled Synthesis and Fluorescence Tracking of Highly Uniform PolyN-isopropylacrylamide Microgels
Published on: September 8, 2016
Integral representation of generalized grey Brownian motion
Wolfgang Bock1, Sascha Desmettre2, José Luís da Silva3
1Department of Mathematics, TU Kaiserslautern (TUK), Kaiserslautern, Germany.

Abstract:
In this paper, we investigate the representation of a class of non-Gaussian processes, namely generalized grey Brownian motion, in terms of a weighted integral of a stochastic process which is a solution of a certain stochastic differential equation. In particular, the underlying process can be seen as a non-Gaussian extension of the Ornstein-Uhlenbeck process, hence generalizing the representation results of Muravlev, Russian Math. Surveys 66 (2), 2011 as well as Harms and Stefanovits, Stochastic Process. Appl. 129, 2019 to the non-Gaussian case.
Related Concept Videos
 01:24
Reynolds Transport Theorem
 01:11
Angular Momentum about an Arbitrary Axis
The velocity of a mass element comprises its translational velocity and the relative velocity instigated by the body's rotation. Substituting the velocity equation into...
 01:17
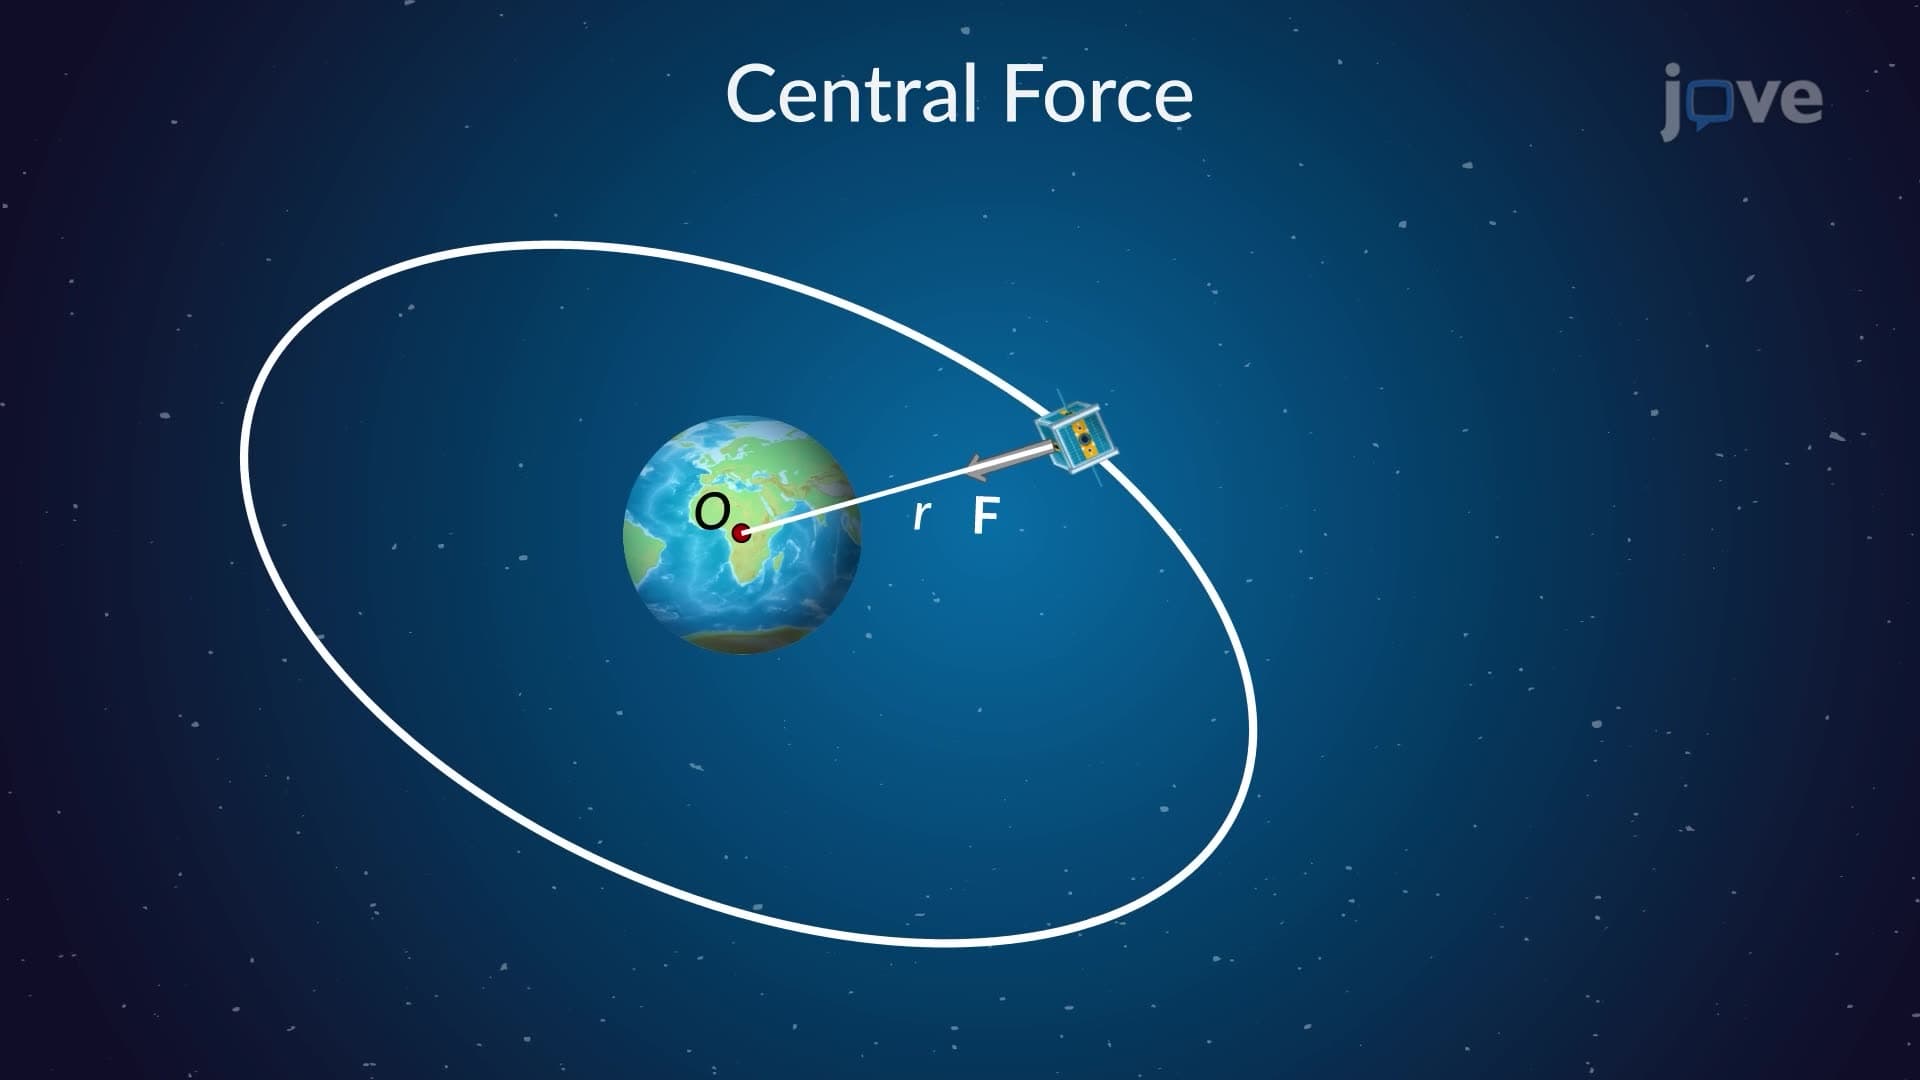
Central-Force Motion
 01:10
Entropy Change in Reversible Processes
The statement can be further generalized to prove that entropy is a state function. Take a cyclic process between any two points on a p-V diagram.
 01:23
Curvilinear Motion: Rectangular Components
As the car advances, its position evolves over time. Quantifying the car's velocity involves computing the...
 01:17
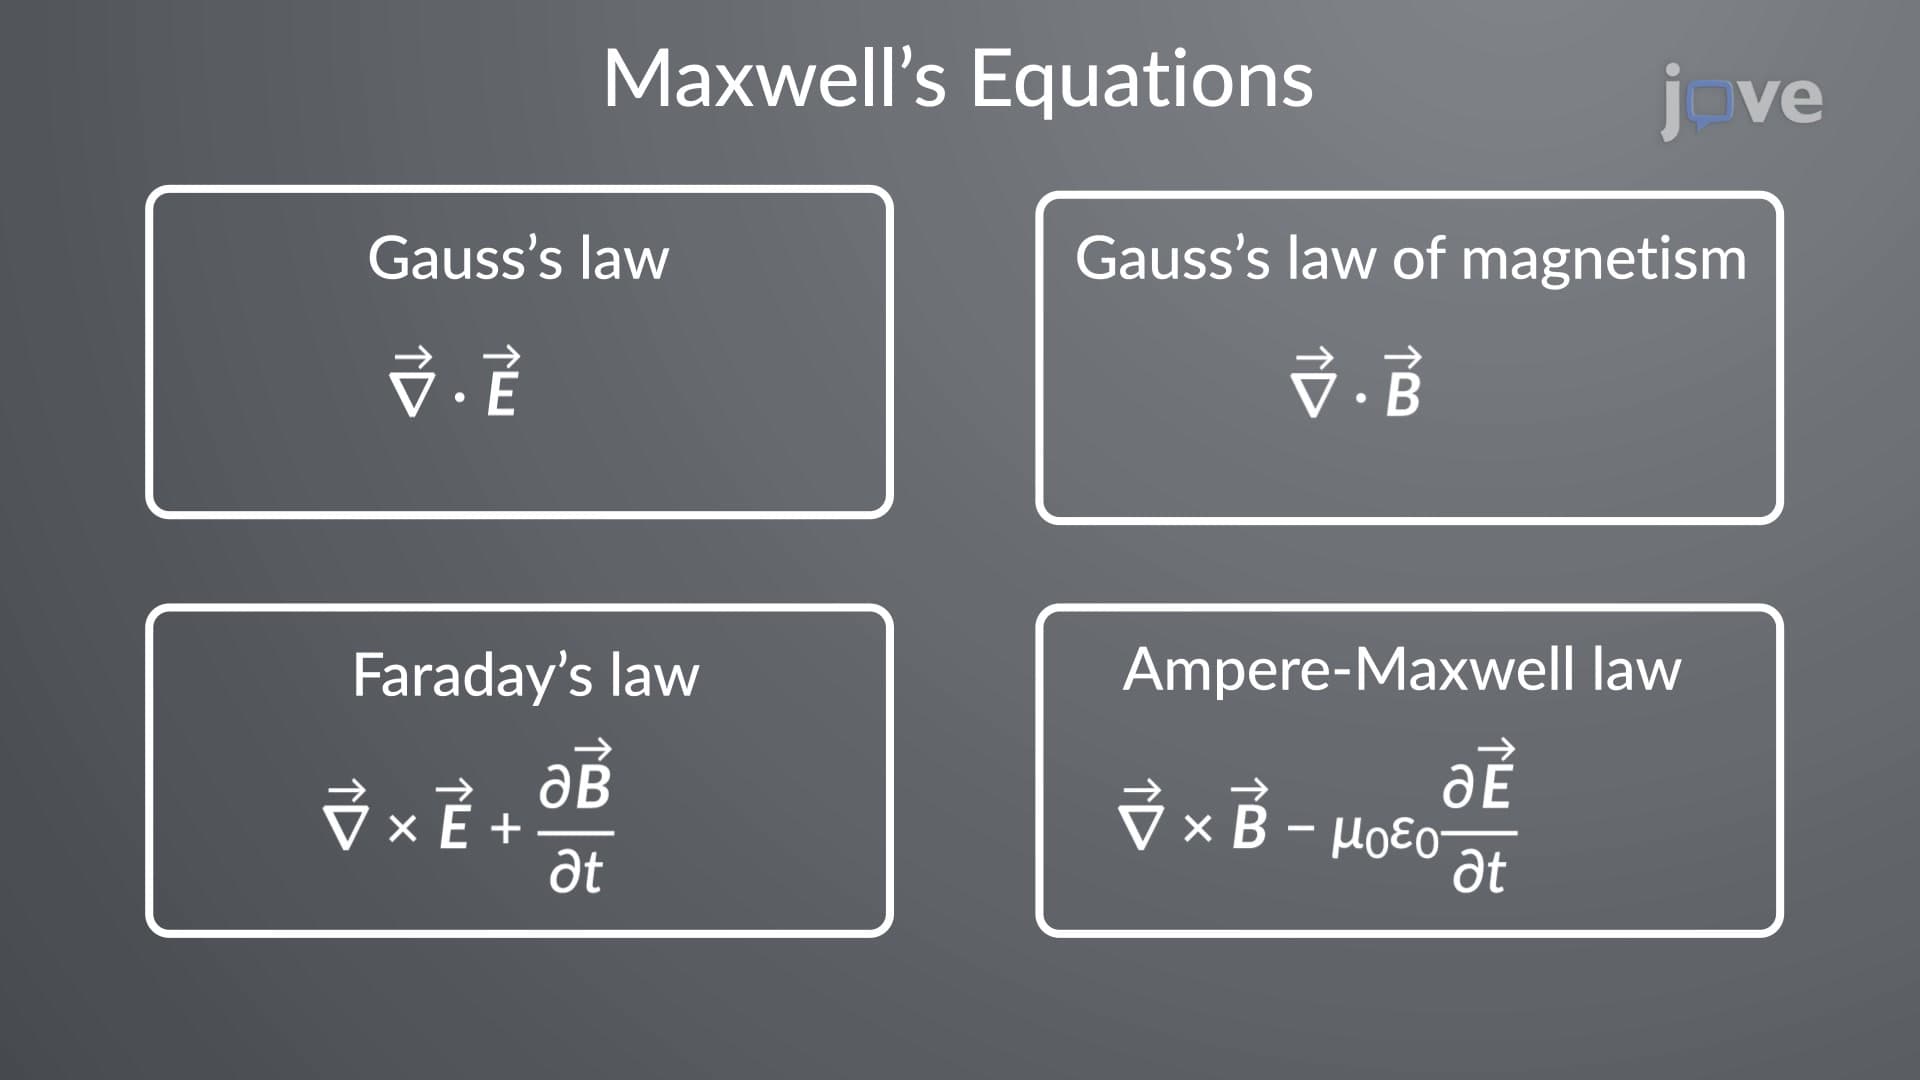
Differential Form of Maxwell's Equations