Related Experiment Video
Updated: Dec 8, 2025

A Method of Trigonometric Modelling of Seasonal Variation Demonstrated with Multiple Sclerosis Relapse Data
Published on: December 9, 2015
Segmentation of time series in up- and down-trends using the epsilon-tau procedure with application to USD/JPY
Arthur Matsuo Yamashita Rios de Sousa1, Hideki Takayasu1,2, Misako Takayasu1,3
1Institute of Innovative Research, Tokyo Institute of Technology, Yokohama, Kanagawa, Japan.

Abstract:
We propose the epsilon-tau procedure to determine up- and down-trends in a time series, working as a tool for its segmentation. The method denomination reflects the use of a tolerance level ε for the series values and a patience level τ in the time axis to delimit the trends. We first illustrate the procedure in discrete random walks, deriving the exact probability distributions of trend lengths and trend amplitudes, and then apply it to segment and analyze the trends of U.S. dollar (USD)/Japanese yen (JPY) market time series from 2015 to 2018. Besides studying the statistics of trend lengths and amplitudes, we investigate the internal structure of the trends by grouping trends with similar shapes and selecting clusters of shapes that rarely occur in the randomized data. Particularly, we identify a set of down-trends presenting similar sharp appreciation of the yen that are associated with exceptional events such as the Brexit Referendum in 2016.
Related Concept Videos
 00:54
Time-Series Graph
 01:20
Discrete-Time Fourier Series
For a discrete-time periodic signal x[n]...
 01:18
Increasing Function
 01:22
Upsampling
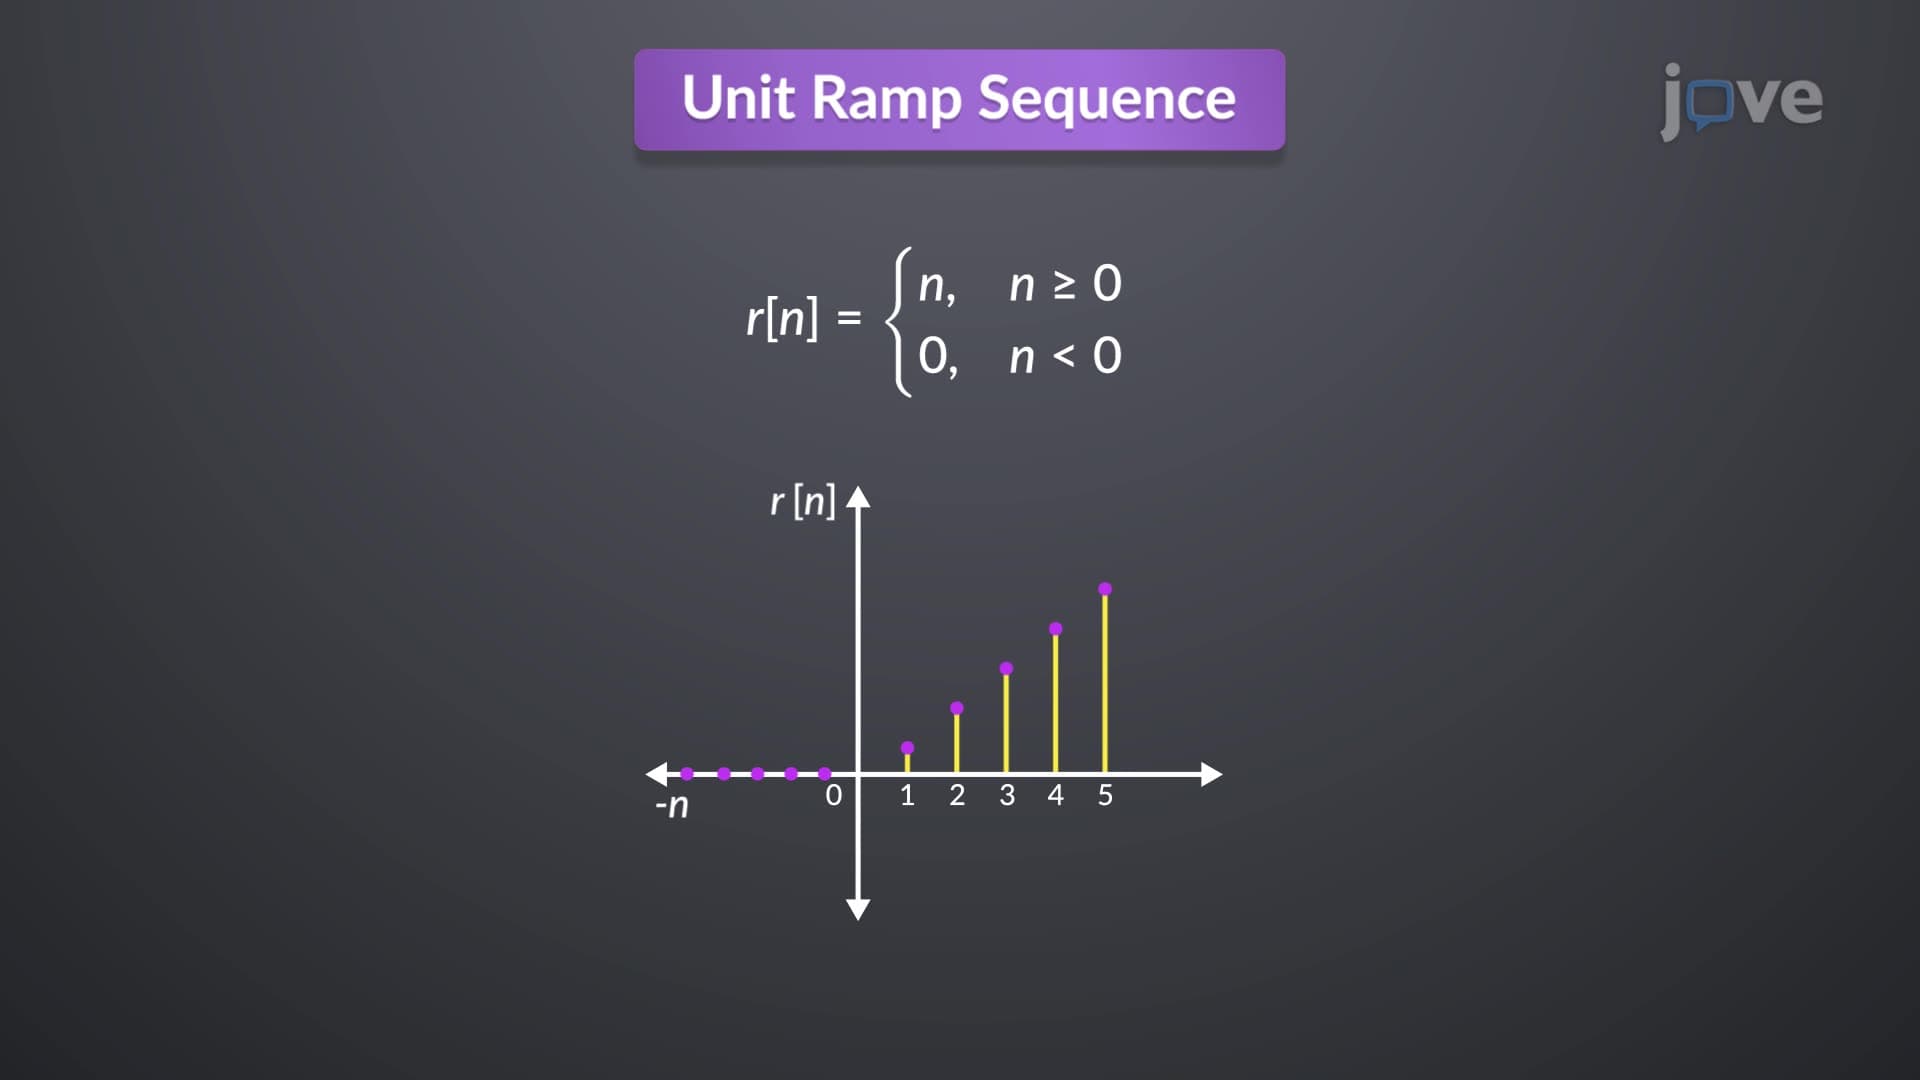 01:16
Basic Discrete Time Signals
The unit impulse or sample sequence is mathematically expressed as zero for all n values except at n=0, where it is one. The unit impulse sequence, denoted by δ(n), is the first difference of the unit step sequence, while the unit step sequence u(n) is the...
 01:29
Econometric Views (EViews)