Related Experiment Video
Updated: Dec 6, 2025

A Method of Trigonometric Modelling of Seasonal Variation Demonstrated with Multiple Sclerosis Relapse Data
Published on: December 9, 2015
Quantifying Insurance Agency Channel Dynamics Using Premium Sales Big Data and External Factors
Erdem Kaya1, Eray Alpan1, Selim Balcisoy1
1Faculty of Engineering and Natural Sciences, Sabanci University, Istanbul, Turkey.

Abstract:
In insurance business, product sales can be realized over a variety of channels such as independent agencies, or bank branches. In 2017, 55% of premium production was generated over insurance agencies in Turkey making independent agency evaluation prominent in the domain. Unfortunately lacking attention from the scientific community, agency evaluation problem is usually tackled in the industry by utilizing internal business dynamics data. To incorporate the external facts to the agency evaluation process, we propose a computational approach to model behavior traits reflecting insurance agency channel dynamics based on not only premium sales big data but also external facts. We demonstrate how we translate these behavior traits into useful features, namely, utilization, response, and governance, so that each agency can be positioned in a space whose dimensions are determined by these features allowing easy visual detection of segments. Utilization model suggests that each agency has a potential based on its location, determined by several local socioeconomic factors, and it explains the capability of converting potential to profit. To compute utilization scores, we adapt point-of-interest data as a parameter to the segmentation model, a novel approach not only in the insurance business but also in the literature. The response model suggests that a responsive agency must follow overall profit trends of the company. Finally, the governance model explains agency/company cooperation in terms of premium production. All together, we propose a segmentation-based agency evaluation model providing understanding of insurance agency behavior that could be explained and formulated along these three dimensions. Based on the findings from a year-long case study and a proceeding implementation period of our models on an actual analytic system of the insurance company donating the data, we reflect on the performance and usability of our behavioral models that were fit on premium sales big data comprising 127 million transactions. Our results suggest that (1) our approach is quite efficient in extracting features from production logs, (2) behavioral models are quite intuitive resulting in straightforward application steps, and (3) the adoption of behavior models in agency segmentation and evaluation processes is an improvement over commonplace approaches in which premium production is used as the sole metric.
Related Concept Videos
 01:20
Actuarial Approach
Consider the example of a high-risk surgical procedure with significant early-stage mortality. A two-year clinical study is conducted,...
 01:17
Factors Affecting Activity Coefficient
The activity coefficient value for an ion is close to one when the solution has almost zero ionic strength, i.e., when the solution shows close to ideal behavior. As the ionic strength of the solution increases from 0 to 0.1 mol/L, a...
 01:09
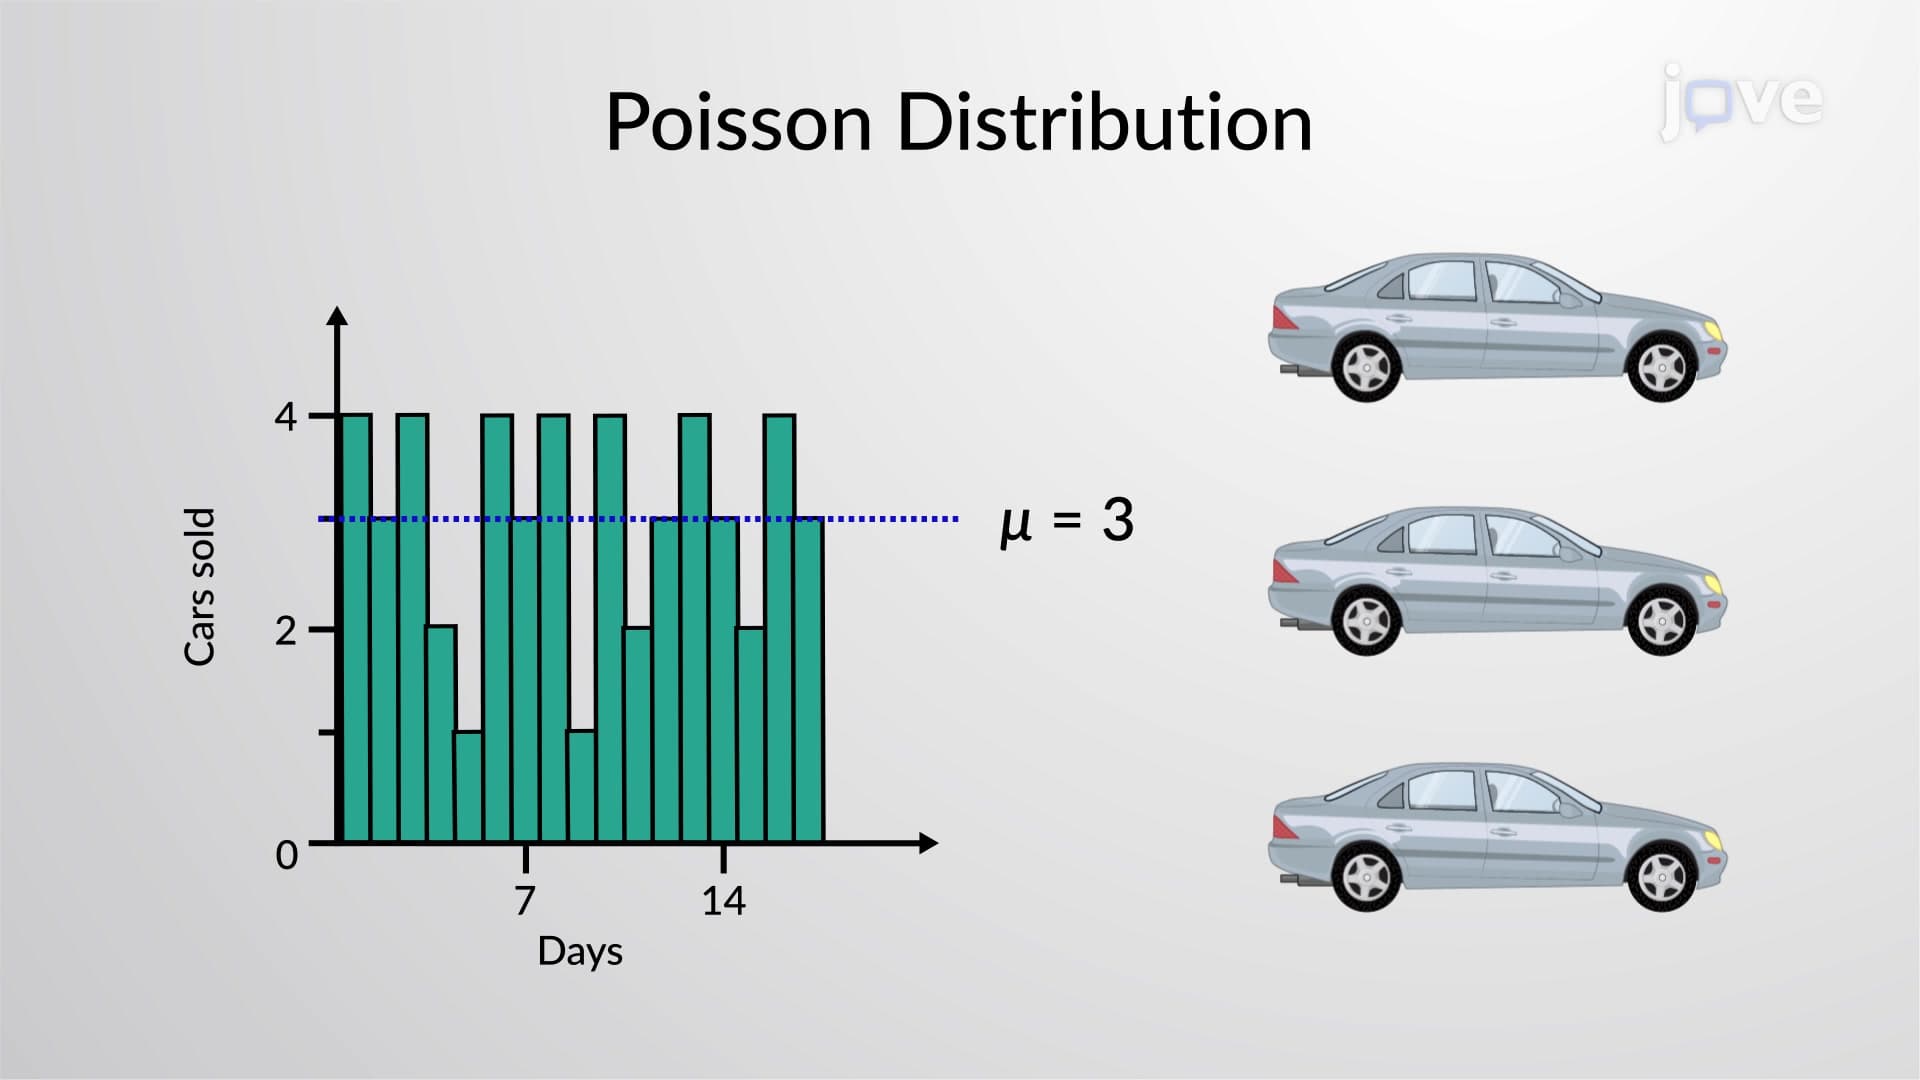
Poisson Probability Distribution
The...
 01:17
Design Example: Analyzing Capacity Contours for Flood Risk Assessment
 01:18
Steps in Outbreak Investigation
 01:09
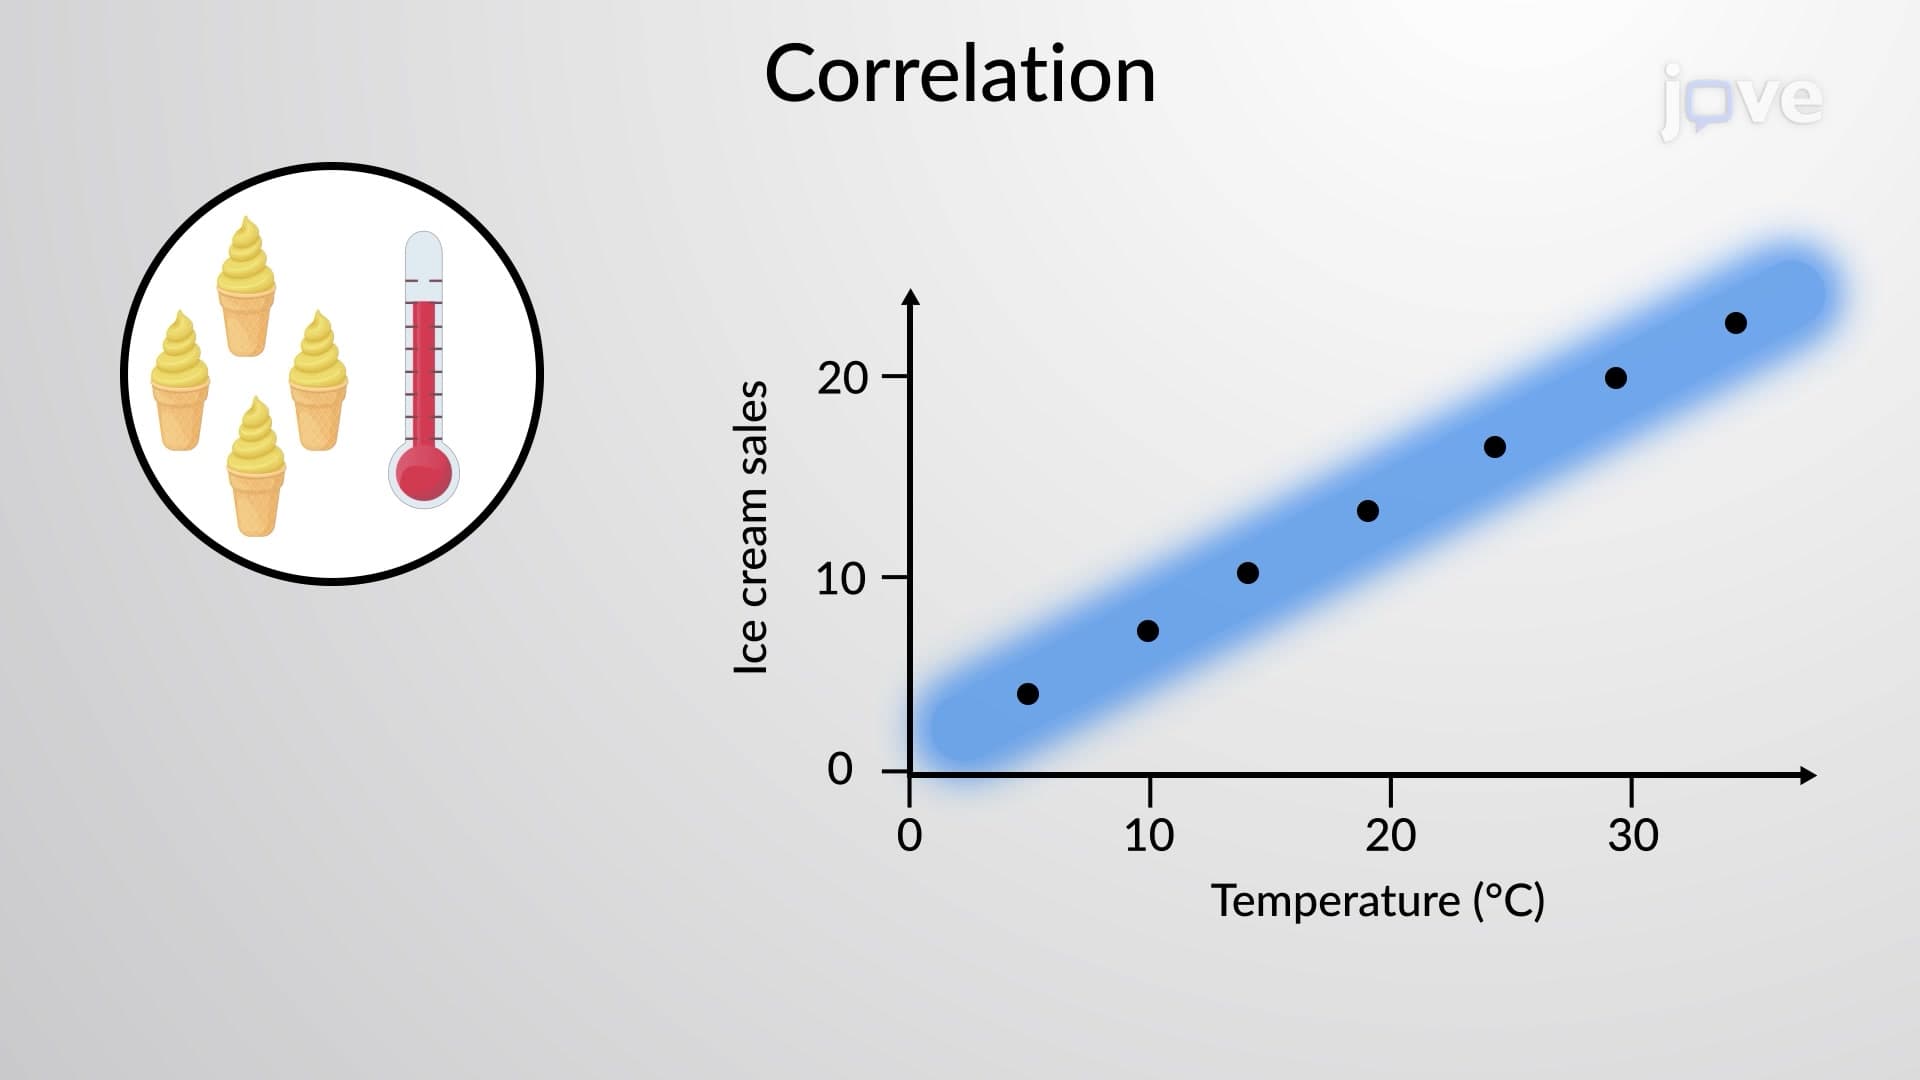
Correlation
Two variables, for example, a and b, are said to be positively correlated if both variables move in the same direction. In other words, a positive correlation exists between two variables, a and b, if: