Related Experiment Video
Updated: Dec 5, 2025
Author Spotlight: Advancements in Multiplex Detection of Respiratory Viruses
Published on: November 10, 2023
Learning from SARS: Return and volatility connectedness in COVID-19
Emawtee Bissoondoyal-Bheenick1, Hung Do2, Xiaolu Hu1
1School of Economics, Finance and Marketing, RMIT University, Melbourne, Australia.

Abstract:
Using a sample of the G20 countries, we examine the impact of COVID-19 on stock return and volatility connectedness, and whether the connectedness measures behave differently for countries with SARS 2003 experience. We find that both stock return and volatility connectedness increase across the phases of the COVID-19 pandemic which is more pronounced as the severity of the pandemic builds up. However, the degree of connectedness is significantly lower in countries with SARS 2003 death experience. Our results are robust to different measures of COVID-19 severity and controlling for a number of cross-country differences in economic development.
More Related Videos
Related Concept Videos
 01:21
Causality in Epidemiology
 01:27
Correlation and Causation
Correlation versus Causation
If the dependent variable increases or decreases when the independent variable increases, there is a positive or negative...
 01:18
Steps in Outbreak Investigation
 01:11
Residuals and Least-Squares Property
If the observed data point lies above the line, the residual is positive, and the line underestimates the actual data value for y. If the observed data point lies below the line, the residual is negative, and the line overestimates the actual data value for y.
The process of fitting the best-fit...
 01:11
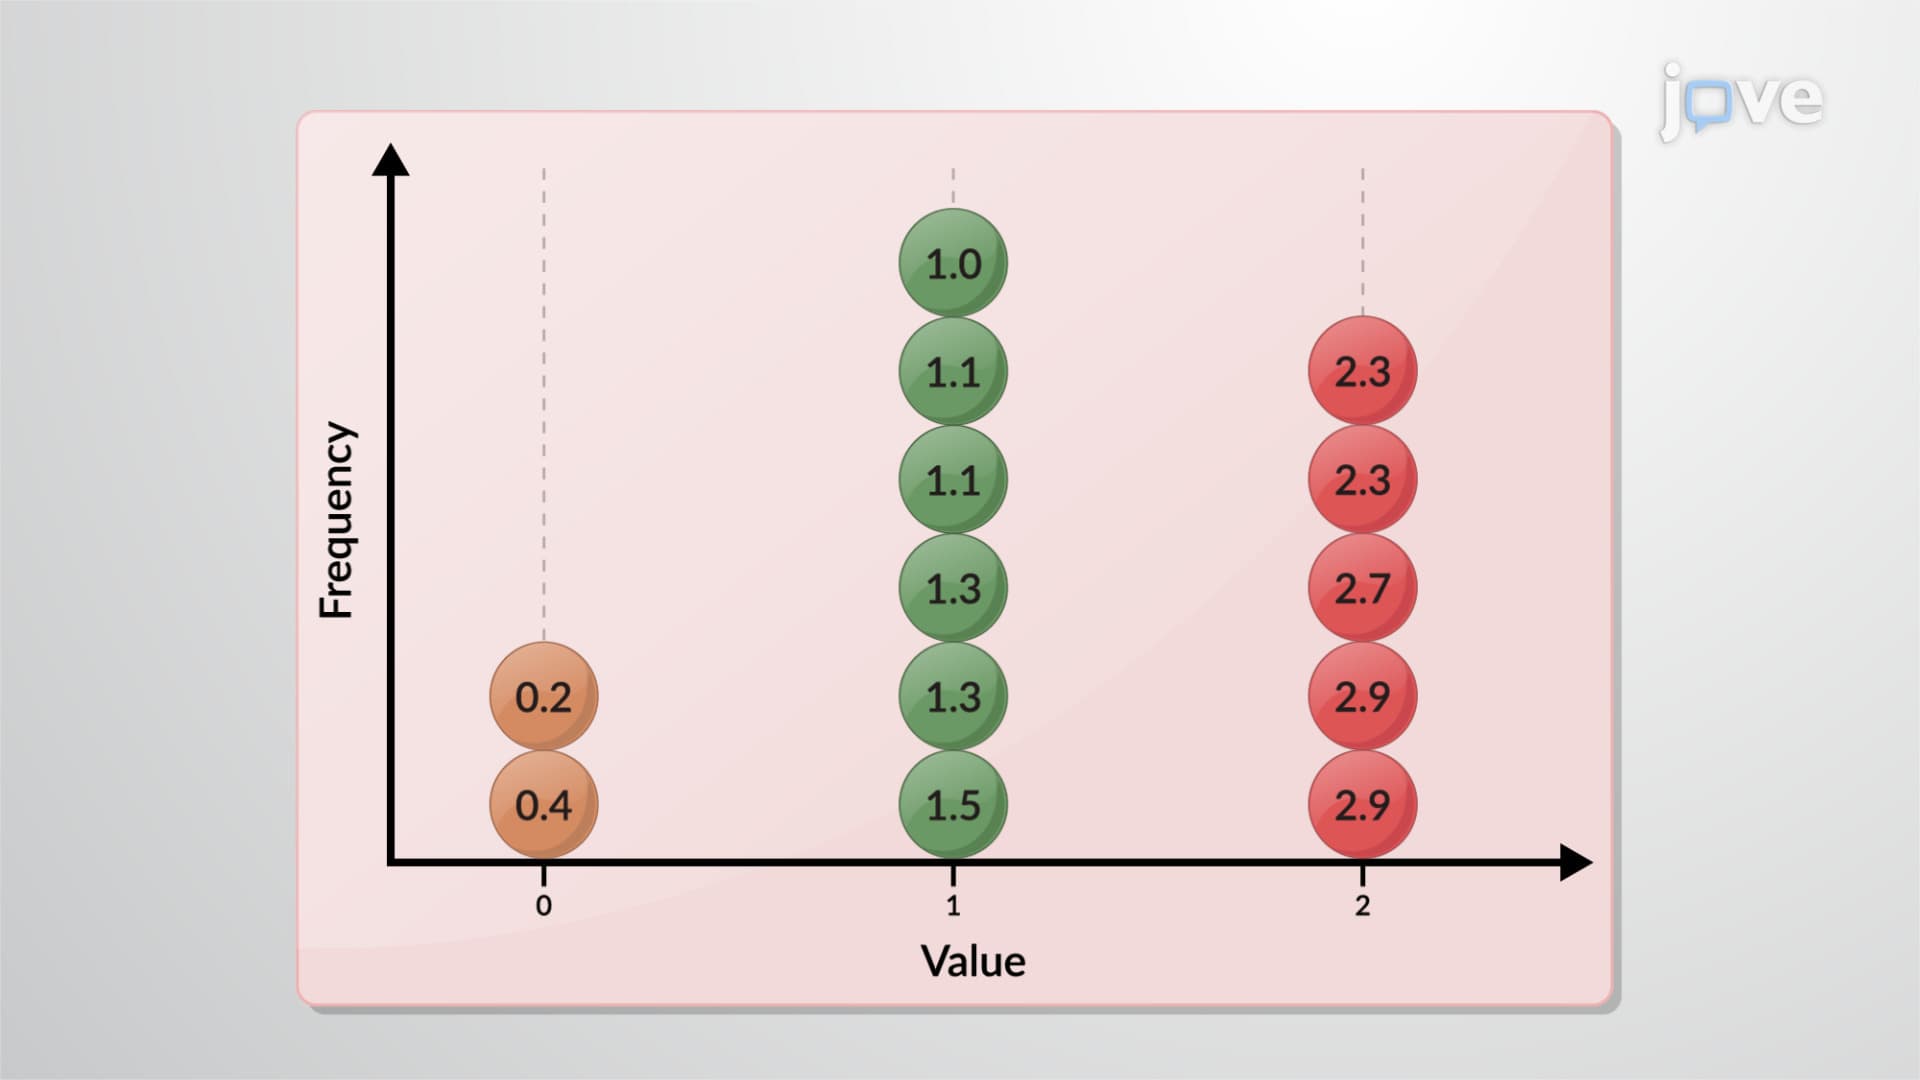
Variability: Analysis
The range is a simple measure of variability, indicating the difference between the highest and...
 01:10
Standard Deviation