Related Experiment Video
Updated: Nov 29, 2025

Measuring the Subjective Value of Risky and Ambiguous Options using Experimental Economics and Functional MRI Methods
Published on: September 19, 2012
Learning agents in Black-Scholes financial markets
Tushar Vaidya1, Carlos Murguia2, Georgios Piliouras1
1Singapore University of Technology and Design, 8 Somapah Road, Singapore 487372, Singapore.

Abstract:
Black-Scholes (BS) is a remarkable quotation model for European option pricing in financial markets. Option prices are calculated using an analytical formula whose main inputs are strike (at which price to exercise) and volatility. The BS framework assumes that volatility remains constant across all strikes; however, in practice, it varies. How do traders come to learn these parameters? We introduce natural agent-based models, in which traders update their beliefs about the true implied volatility based on the opinions of other agents. We prove exponentially fast convergence of these opinion dynamics, using techniques from control theory and leader-follower models, thus providing a resolution between theory and market practices. We allow for two different models, one with feedback and one with an unknown leader.
Related Concept Videos
 01:29
Mathematical Modeling: Problem Solving
 01:26
Equity Theory
 01:20
Actuarial Approach
Consider the example of a high-risk surgical procedure with significant early-stage mortality. A two-year clinical study is conducted,...
 01:12
Observational Learning
 01:18
Introduction to Learning
In contrast to learned behaviors, unlearned behaviors such as crying, sexual...
 01:09
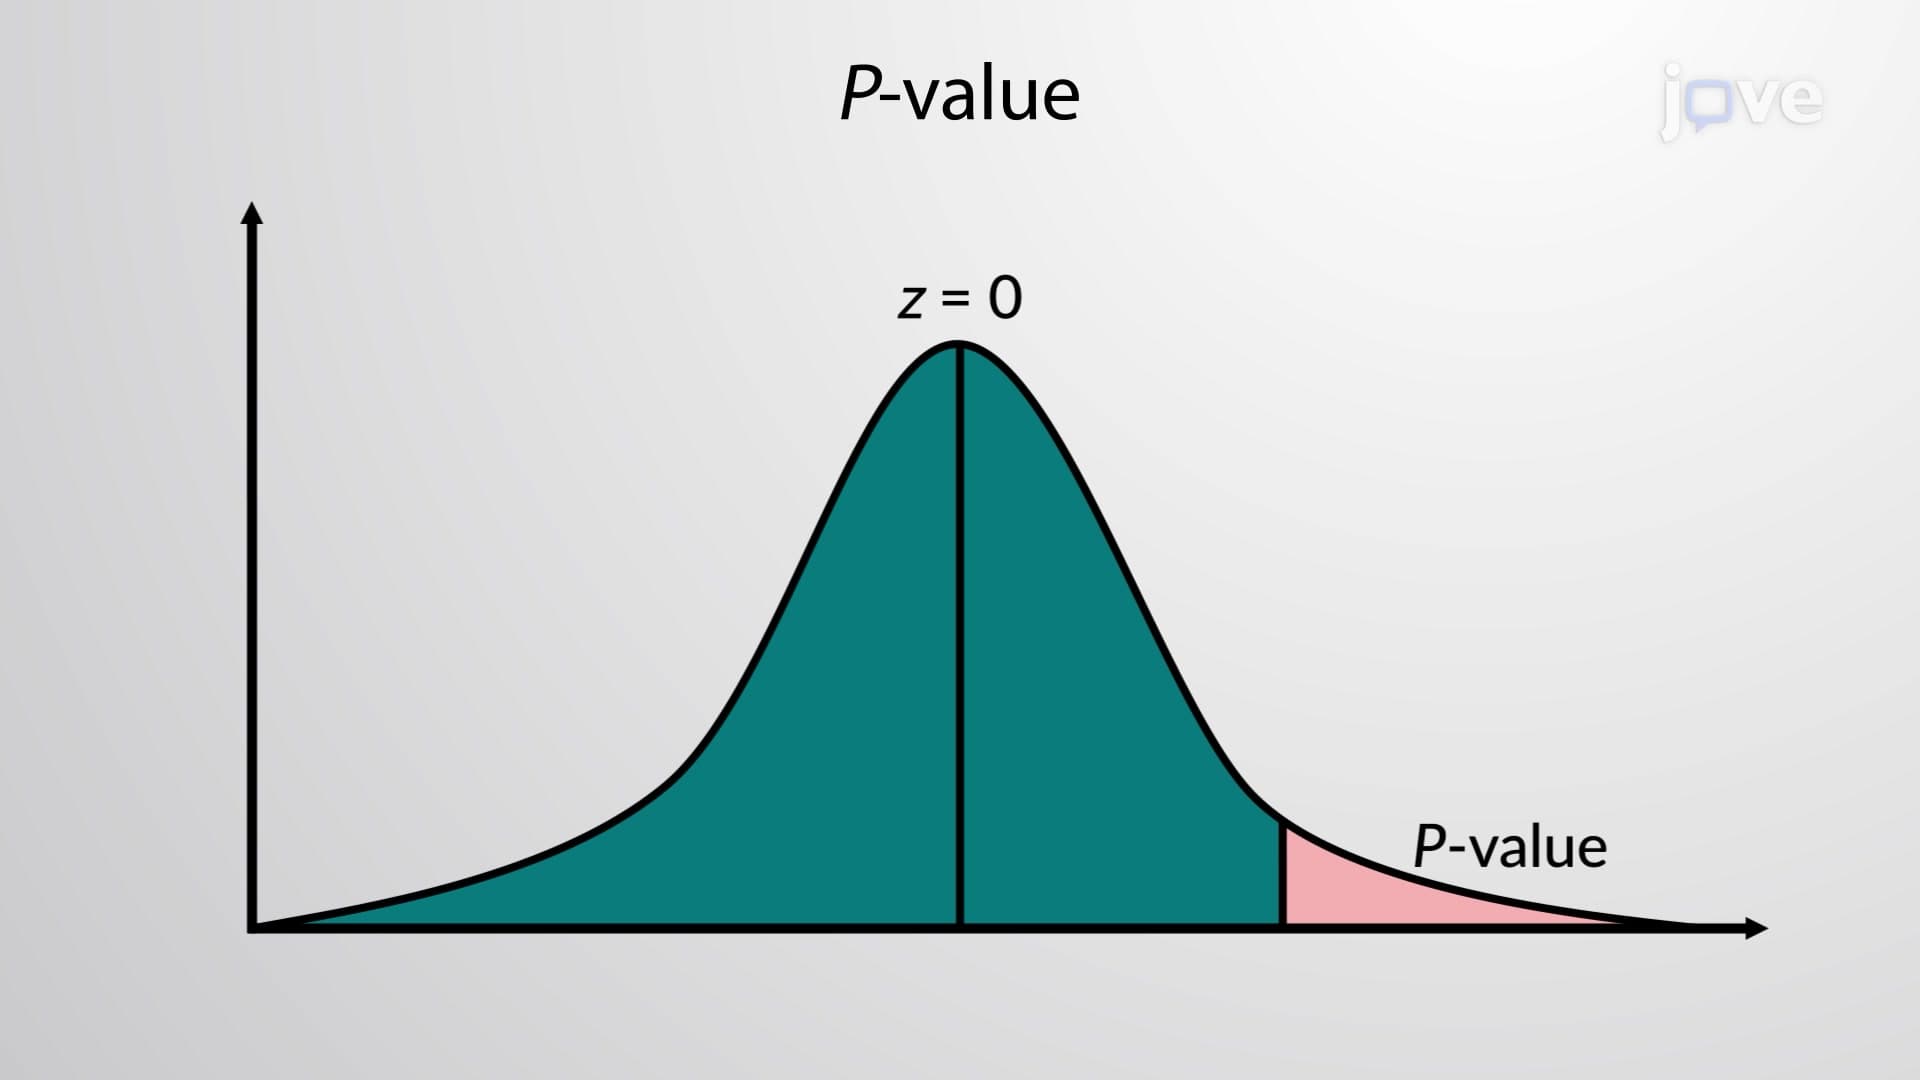
Decision Making: P-value Method
First, a specific claim about the population parameter is proposed. The claim is based on the research question and is stated in a simple form. Further, an opposing statement to the claim is also stated. These statements can act as null and alternative hypotheses: a null hypothesis would be a neutral statement while the alternative hypothesis can...