Related Experiment Video
Updated: Nov 12, 2025
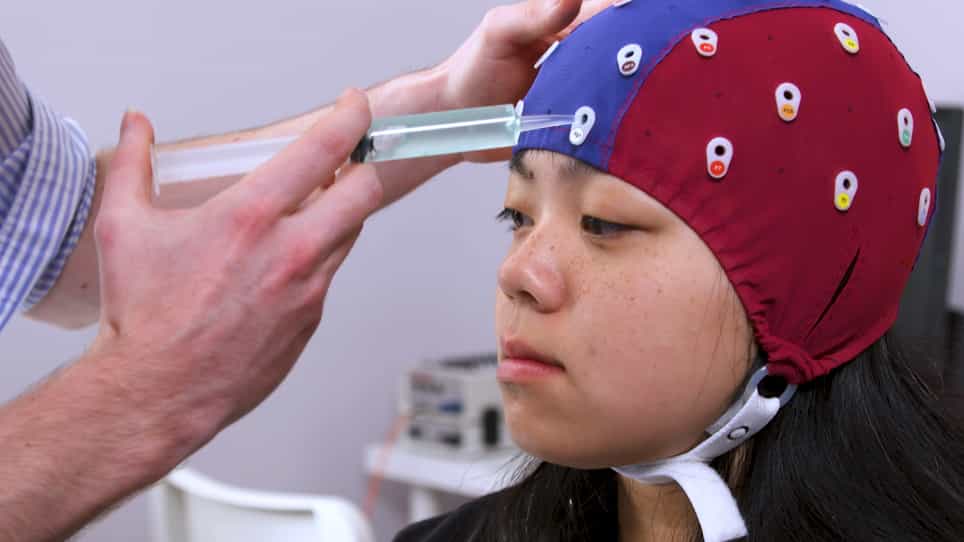

Statistical Modelling of Cortical Connectivity Using Non-invasive Electroencephalograms
Published on: November 1, 2019
Model averaging estimation for high-dimensional covariance matrices with a network structure
Rong Zhu1, Xinyu Zhang2, Yanyuan Ma3
1School of Mathematics, Statistics and Physics, Newcastle University, Newcastle upon Tyne NE1 7RU, UK.

Abstract:
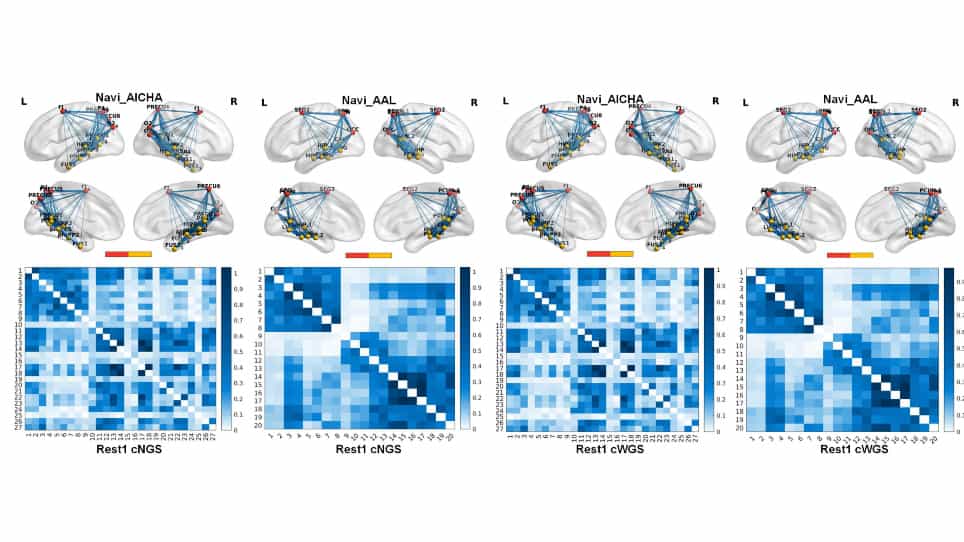
In this paper, we develop a model averaging method to estimate a high-dimensional covariance matrix, where the candidate models are constructed by different orders of polynomial functions. We propose a Mallows-type model averaging criterion and select the weights by minimizing this criterion, which is an unbiased estimator of the expected in-sample squared error plus a constant. Then, we prove the asymptotic optimality of the resulting model average covariance estimators. Finally, we conduct numerical simulations and a case study on Chinese airport network structure data to demonstrate the usefulness of the proposed approaches.
Related Concept Videos
 01:24
One-Compartment Open Model: Wagner-Nelson and Loo Riegelman Method for ka Estimation
On...
 01:22
Estimating Population Mean with Unknown Standard Deviation
William S. Gosset (1876–1937) of the...
 01:06
Model Approaches for Pharmacokinetic Data: Distributed Parameter Models
The distributed parameter models are specifically designed to account for variations and differences in some drug classes. This model is particularly useful for assessing regional concentrations of anticancer or...
 01:16
Estimating Population Mean with Known Standard Deviation
The confidence interval estimate will have the form as follows:
(point estimate - error bound, point estimate +...
 01:30
Typical Model Studies
 01:14
Multicompartment Models: Overview
These models offer a more comprehensive representation of drug behavior in the body than one-compartment models. They accommodate the complexity of drug distribution,...