Related Experiment Video
Updated: Nov 9, 2025

Statistical Modelling of Cortical Connectivity Using Non-invasive Electroencephalograms
Published on: November 1, 2019
Asymptotics of eigenstructure of sample correlation matrices for high-dimensional spiked models
David Morales-Jimenez1, Iain M Johnstone2, Matthew R McKay3
1ECIT Institute, Queen's University Belfast, UK.

Abstract:
Sample correlation matrices are widely used, but for high-dimensional data little is known about their spectral properties beyond "null models", which assume the data have independent coordinates. In the class of spiked models, we apply random matrix theory to derive asymptotic first-order and distributional results for both leading eigenvalues and eigenvectors of sample correlation matrices, assuming a high-dimensional regime in which the ratio p/n, of number of variables p to sample size n, converges to a positive constant. While the first-order spectral properties of sample correlation matrices match those of sample covariance matrices, their asymptotic distributions can differ significantly. Indeed, the correlation-based fluctuations of both sample eigenvalues and eigenvectors are often remarkably smaller than those of their sample covariance counterparts.

Related Concept Videos
 01:12
Coefficient of Correlation
If you suspect a linear relationship between x and y, then r can measure how strong the linear relationship is.
What the VALUE of r tells us:
The value of r is always between –1 and +1: –1 ≤ r ≤ 1.
The size of the correlation r indicates the...
 01:24
One-Compartment Open Model: Wagner-Nelson and Loo Riegelman Method for ka Estimation
On...
 01:23
Quadratic Models
 00:56
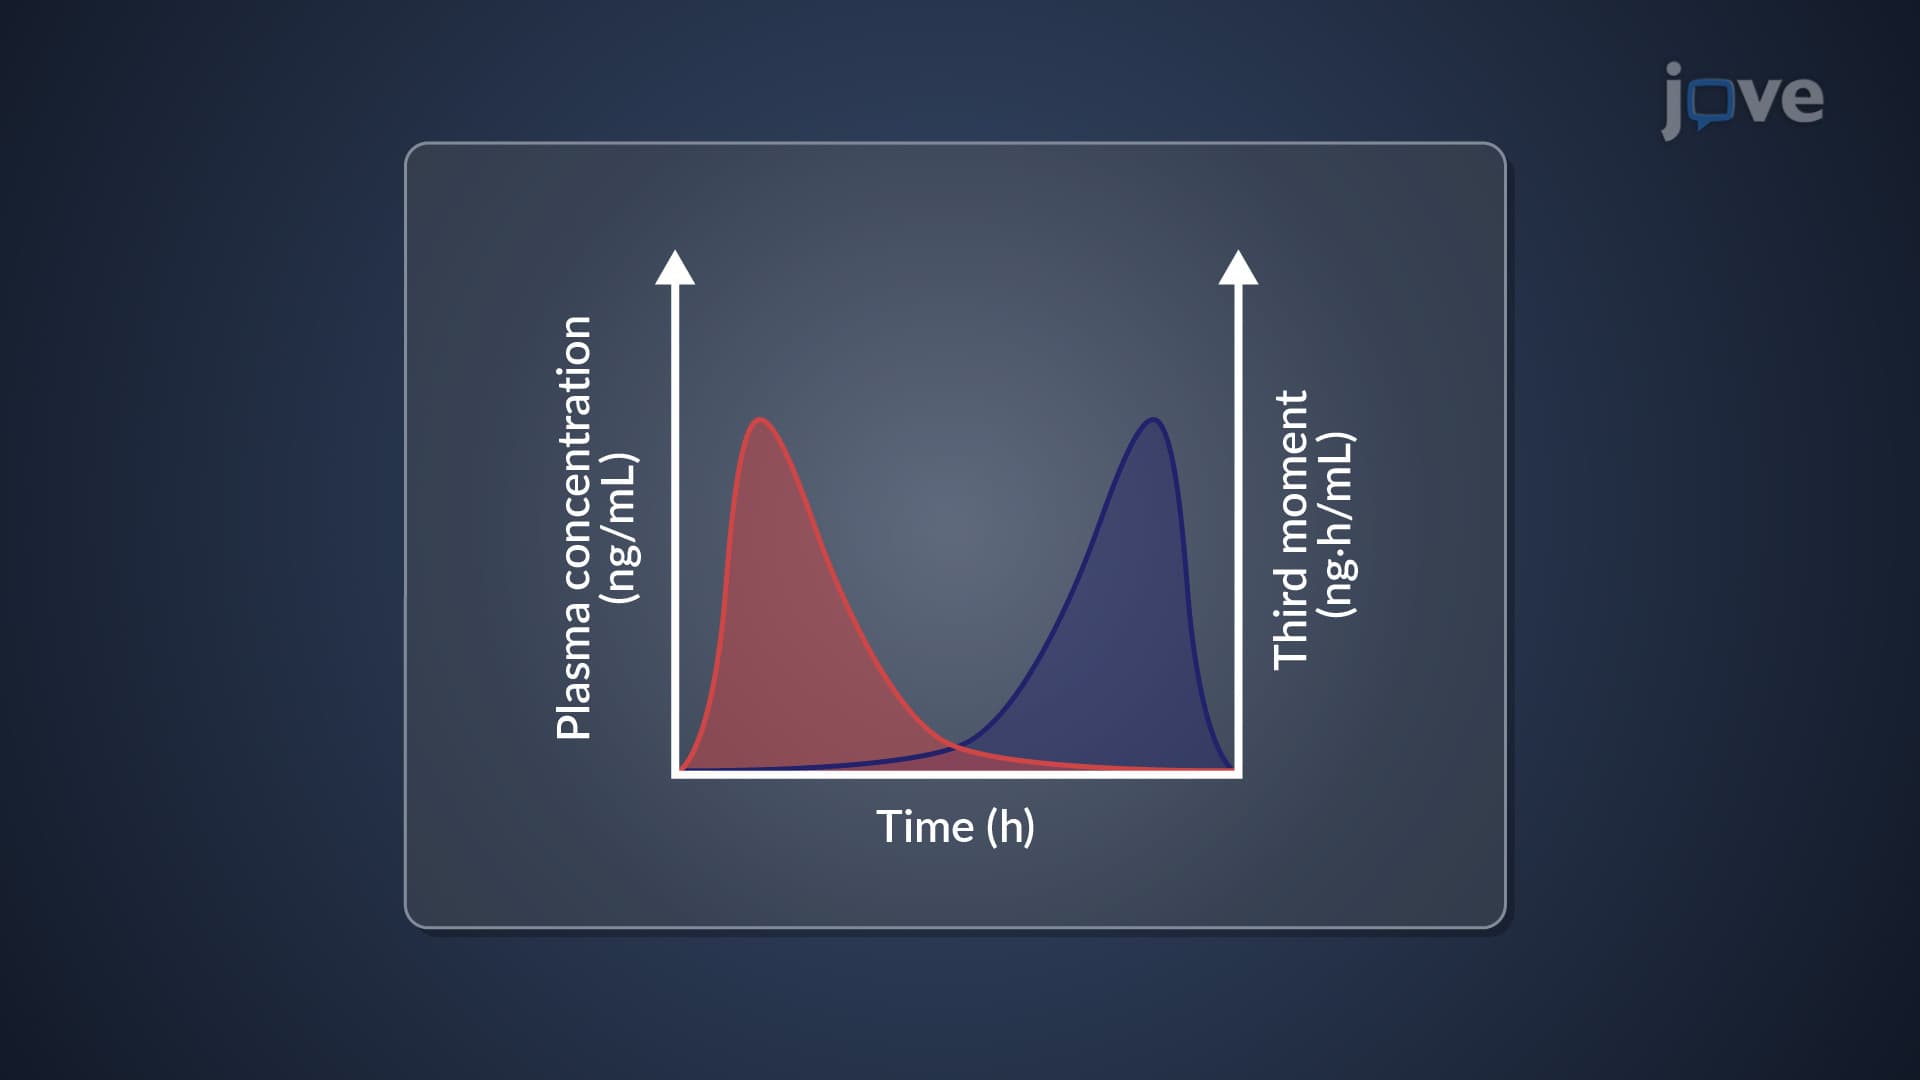
Noncompartmental Analysis: Statistical Moment Theory
 01:23
Correlation of Experimental Data
For example, a spherical particle moving through a viscous fluid experiences drag. Dimensional analysis shows that the drag force depends on the particle's diameter, velocity,...
 01:14
Stability of structures