l1-Norm Quantile Regression Screening Rule via the Dual Circumscribed Sphere
Related Experiment Video
Updated: Nov 2, 2025

An R-Based Landscape Validation of a Competing Risk Model
Published on: September 16, 2022

Abstract:
l1-norm quantile regression is a common choice if there exists outlier or heavy-tailed error in high-dimensional data sets. However, it is computationally expensive to solve this problem when the feature size of data is ultra high. As far as we know, existing screening rules can not speed up the computation of the l1-norm quantile regression, which dues to the non-differentiability of the quantile function/pinball loss. In this paper, we introduce the dual circumscribed sphere technique and propose a novel l1-norm quantile regression screening rule. Our rule is expressed as the closed-form function of given data and eliminates inactive features with a low computational cost. Numerical experiments on some simulation and real data sets show that this screening rule can be used to eliminate almost all inactive features. Moreover, this rule can help to reduce up to 23 times of computational time, compared with the computation without our screening rule.
More Related Videos


Related Concept Videos
 01:19
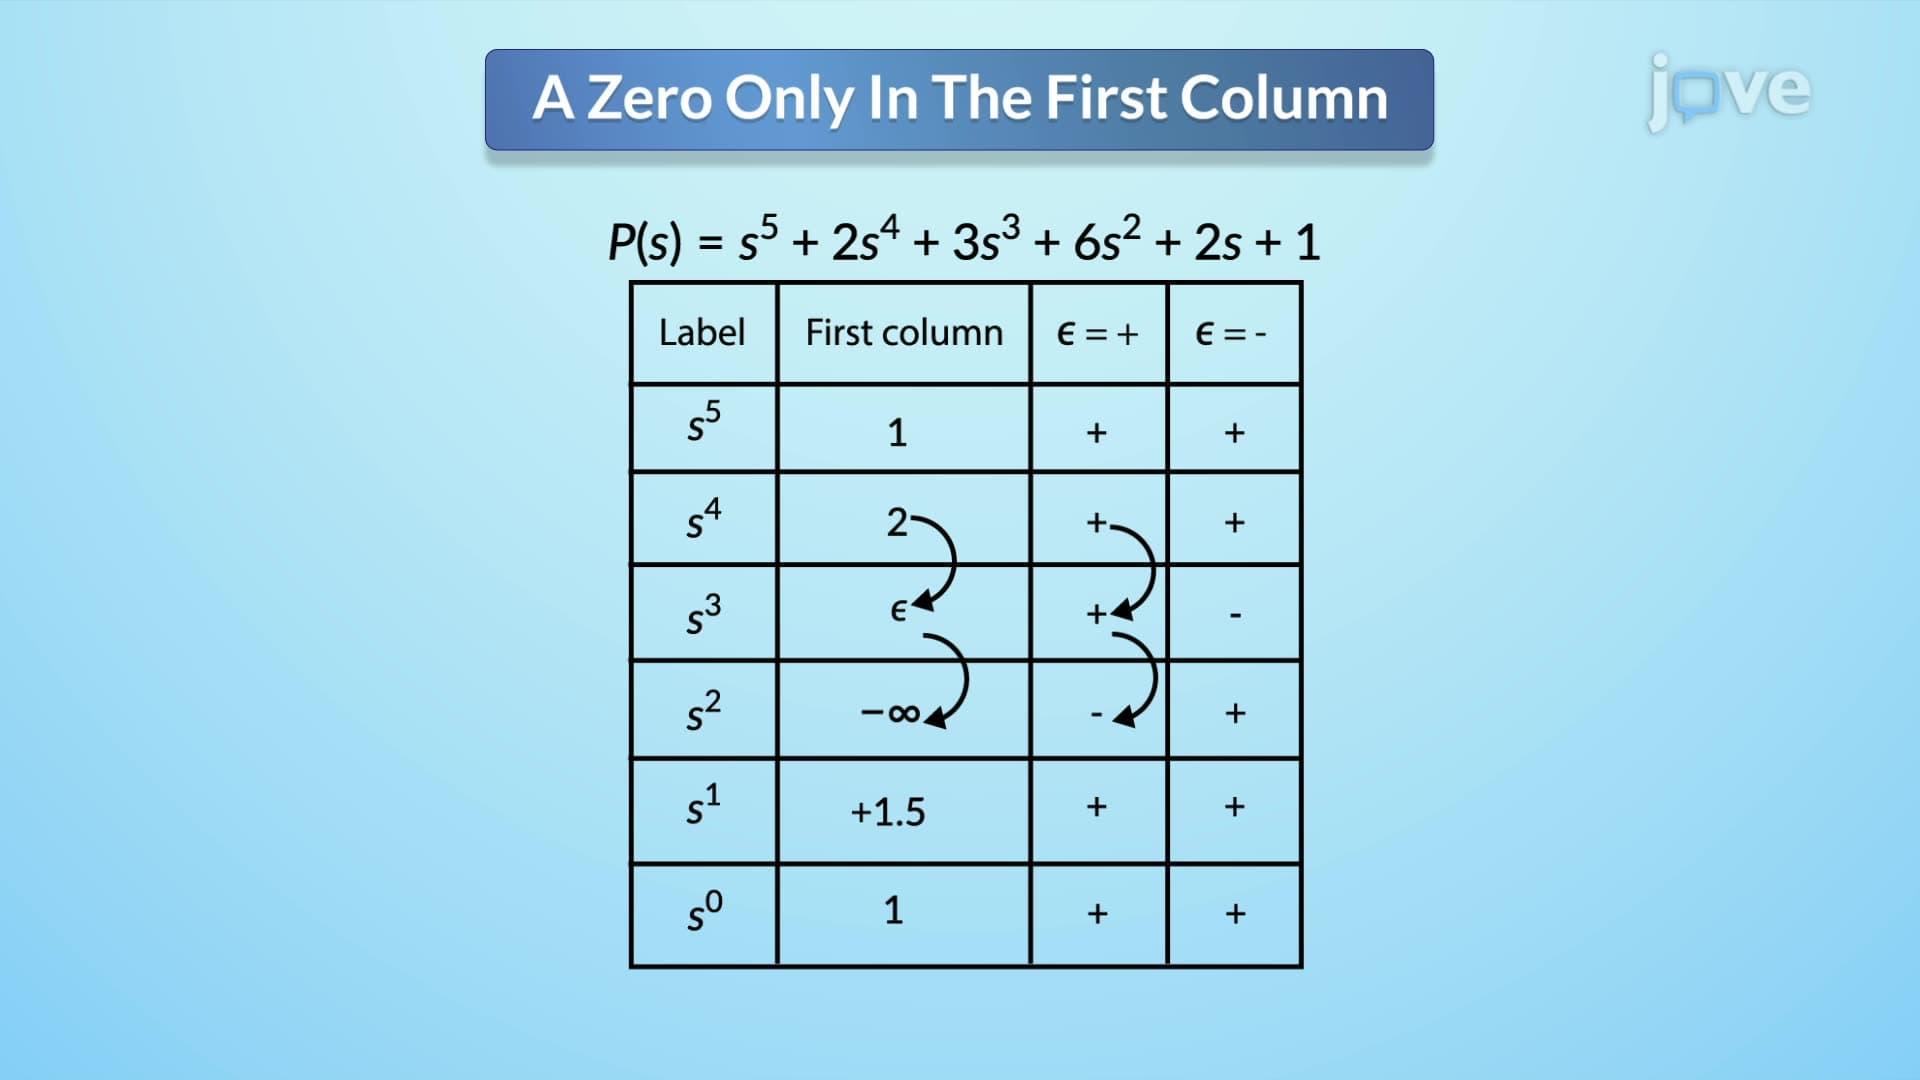
Routh-Hurwitz Criterion II
The first scenario occurs when a singular zero appears in the first column of the Routh table. This situation creates a division by zero issues. To resolve this, a small positive or negative number, denoted as epsilon (∈), is substituted for the zero. The stability analysis proceeds by assuming a sign for ∈. If ∈ is positive, any sign change in the first...
 01:15
Routh-Hurwitz Criterion I
To apply the Routh-Hurwitz criterion, a Routh table is constructed. The table's rows are labeled with powers of the complex frequency variable s, starting from the...
 01:02
Quantifying and Rejecting Outliers: The Grubbs Test
 01:14
Central Limit Theorem
The sample size, n, that...
 01:17
z Scores and Area Under the Curve
 01:00
Detection of Gross Error: The Q Test